


 Be The Investor Research
Tempus AI Raises Its 2026 Outlook as Diagnostics and Data Sales Grow
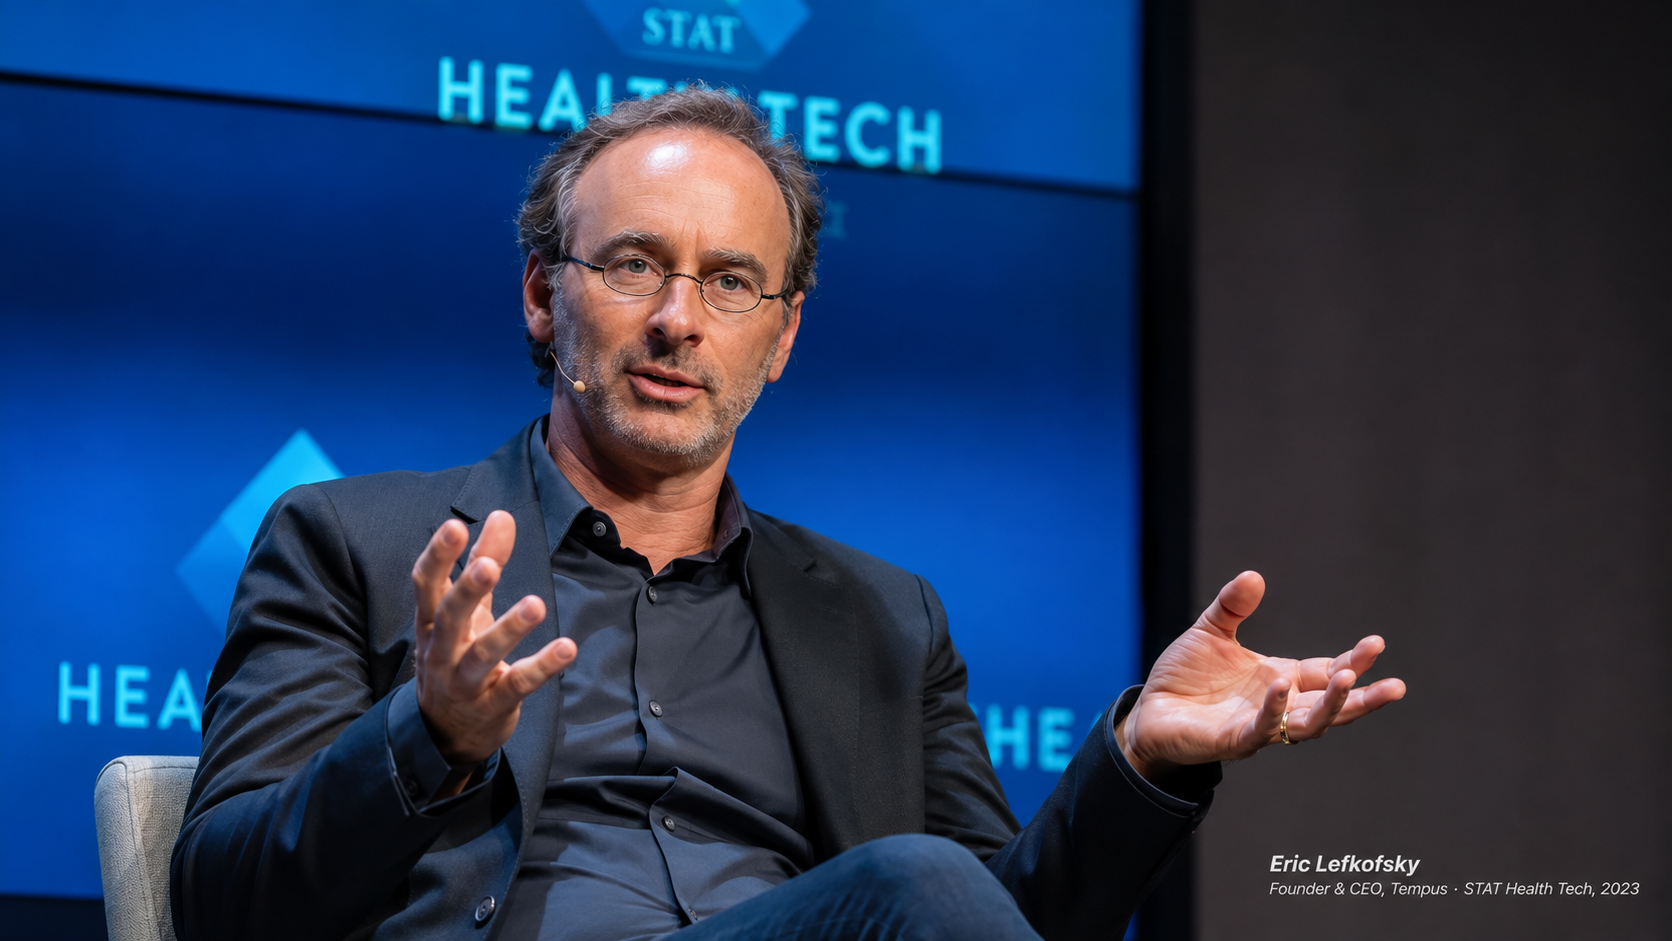
Tempus AI's third-quarter revenue rose 23% to $411.5 million, with growth in both diagnostics and Data & Applications. Higher guidance and positive adjusted EBITDA strengthen the story, though the company still reported a GAAP net loss.
Tempus AI raised its full-year outlook after both of its main businesses grew in the third quarter, giving investors more than a one-segment revenue beat. Revenue rose 23% from a year earlier to $411.5 million. Diagnostics revenue increased 20% to $303.5 million, while Data & Applications revenue grew 33% to $108.1 million.
The mix matters because Tempus is trying to build a reinforcing model. Diagnostic testing produces clinical data, while the Data & Applications business licenses data and software to biopharma customers. Growth in both suggests that the company is expanding the testing platform and finding additional ways to monetize the information it generates. Management also reported 32% unit growth in oncology, the largest diagnostics area.
Profitability improved on the company's adjusted measure, but the accounting distinction is important. Adjusted EBITDA was $25.6 million and adjusted earnings were reported at $0.07 a share, ahead of the loss expected by analysts cited in the original report. On a GAAP basis, Tempus still posted a $14.9 million net loss. Investors should not treat adjusted EBITDA as cash available to shareholders, particularly while the company is integrating acquisitions and investing in growth.
Tempus now expects 2026 revenue of $1.60 billion to $1.605 billion and adjusted EBITDA of about $65 million. The revised range is narrow, so fourth-quarter execution will determine whether the company finishes at the high or low end. The official release also reported $854.4 million of cash and marketable securities, providing room for integration and product investment.
Several operating milestones make the quarter more consequential than a simple beat. Tempus said regulatory review of its Personalis acquisition had cleared, the Food and Drug Administration granted two 510(k) clearances for ECG-PH and ECG-MR, and the company plans to expand a research initiative to 100,000 whole genomes. It also reported more than $550 million in year-to-date data licensing bookings, including two Bristol Myers Squibb agreements with potential values of up to $137.5 million and $55 million.
The next question is conversion. Bookings are not the same as recognized revenue, and regulatory clearance does not guarantee commercial adoption. Investors should watch whether Data & Applications growth remains above diagnostics growth, whether the GAAP loss continues to narrow, and whether Personalis adds revenue without pushing expenses back up.
Image references: · Tempus AI / STAT (Official factual visual reference; copyright retained. No Creative Commons grant claimed.)
Frequently asked questions
What is "Tempus AI Raises Its 2026 Outlook as Diagnostics and Data Sales Grow" about?
Tempus AI grew Q3 revenue 23%, raised guidance and posted positive adjusted EBITDA, while GAAP profitability remains unfinished.
What is the market context?
Tempus AI raised its full-year outlook after both of its main businesses grew in the third quarter, giving investors more than a one-segment revenue beat. Revenue rose 23% from a year earlier to $411.5 million. Diagnostics revenue increased 20% to $303.5 million, while Data & Applications revenue grew 33% to $108.1 million. The mix matters because Tempus is trying to build a reinforcing model.…
When was this article published?
It was published on 04 / 11 / 2026 by Be The Investor Research.