 Be The Investor Research
Hot CPI Data Turns a Chip Selloff Into a Broader Market Rout
September inflation accelerated to 3.7%, pushing rate expectations higher as chip stocks were already weakening. The Nasdaq 100 fell 2% and semiconductor ETFs dropped more sharply, revealing concentrated sensitivity to financing conditions.
A semiconductor selloff spread across the U.S. market on October 14 after September inflation came in hotter than expected. The S&P 500 fell 1.1%, the Nasdaq 100 lost 2.0%, and the Russell 2000 dropped 2.0%, their sharpest broad pullback in more than two months.
The inflation report supplied the macro trigger. The Bureau of Labor Statistics said consumer prices rose 0.6% from August and 3.7% from a year earlier. Core prices, excluding food and energy, increased 0.3% for the month and 2.6% over 12 months. The figures strengthened the case for the Federal Reserve to keep policy restrictive or raise rates again.
Technology bore the largest pressure because a higher discount rate weighs most heavily on companies whose expected cash flows sit far in the future. The Invesco QQQ Trust fell 2.8%, while the VanEck Semiconductor ETF lost 4% and the iShares Semiconductor ETF fell 5%, according to Stocktwits. The scale of those moves shows that investors were repricing both inflation and the financing assumptions behind the AI capital-spending cycle.
That does not mean the inflation report changed every company’s operating outlook. It changed the price investors were willing to pay for those outlooks. Chipmakers and infrastructure providers also face different balance sheets, contract visibility and margins, so a sector-wide decline should not be treated as evidence that every AI investment is equally risky.
Energy was a major contributor to the headline inflation increase, which introduces another complication. If the shock fades, annual inflation could ease even while underlying demand remains firm. If higher energy costs persist, they can feed transport and production expenses and keep the Fed cautious.
The next test is whether earnings and cash generation validate the capital spending already embedded in valuations. Companies with funded backlogs and strong balance sheets can absorb a higher-rate environment more easily than businesses relying on continuous refinancing.
For index investors, the lesson is concentration rather than panic. The market decline was broad, but the damage was deepest where valuations, semiconductor cyclicality and AI financing risk overlap. A single inflation print does not set the trend, yet it can expose which parts of the market have the least room for disappointment.
Continue your SPY research
Related News

Big Tech Rebounds, but Earnings Must Justify the AI Spending Cycle
Technology shares recovered ahead of major earnings reports after a sharp weekly decline. Strong early profit growth supports the market, while elevated expectations leave little tolerance for weak guidance.
AI Stocks Rebound After a Rate Shock, but Valuation Risk Remains
A broad technology rebound followed a sharp AI selloff driven by rising yields and profit-taking. The recovery can last only if earnings support the spending and valuation assumptions already embedded in prices.
Palantir and Knox Build a Faster Route Into Secure Federal Clouds
Knox Systems will use Palantir's accredited infrastructure to help software vendors reach FedRAMP and IL5 environments. The partnership strengthens Palantir's federal distribution role, but disclosed financial terms and customer commitments are absent.

TJX Rebound Prompts a Hold Call as AI Stocks Extend Their Slide
A CNBC Investing Club update downgraded TJX to hold after a rebound pushed the position above 4% of its portfolio. The same session showed investors rotating away from capital-intensive AI stocks into defensives.

NYSE Extends Options Trading, but Early Volume Shows the Limits
NYSE added premarket and post-close options sessions for 29 heavily traded stocks and funds. The launch answers demand for longer trading access, but thin initial volume highlights liquidity and execution risks.
Apple Sets Oct. 28 Product Event as Touchscreen MacBook Speculation Builds
Apple confirmed an Oct. 28 event in Los Angeles, with reports pointing to a touchscreen MacBook Pro and other hardware updates. The event arrives as investors debate how much premium devices can extend Apple's growth.
Lilly's Obesity Pill Gains Traction as Chip Stocks Attempt a Rebound

Monday's market rebound carried two different signals for investors. Semiconductor shares tried to end a bruising stretch, while fresh physician data strengthened the case that Eli Lilly's oral obesity treatment can enlarge the GLP-1 market.
The iShares Semiconductor ETF was on course to break a nine-session losing streak, its worst run since May 2006. Yet the recovery was unconvincing: the fund faded from its intraday high, and CoreWeave turned lower and set a new 2026 low below $60. The Nasdaq gained about 1%, but defensive health-care and consumer-staples shares gave back some of the prior week's gains as money rotated back toward chips.
Oil added another macro complication. West Texas Intermediate rose roughly $2 to around $103 a barrel, reviving inflation concerns and pushing Treasury yields higher as bond prices fell. That combination matters because expensive energy and higher yields can make richly valued technology shares harder to support.
Lilly's news was more company-specific. Bank of America raised its price target to $1,397 from $1,341 after a third-quarter physician survey found that about 70% of oral GLP-1 and Medicare Bridge volumes came from patients who were new to treatment or restarting it. That supports Lilly's argument that pills and broader reimbursement are adding patients rather than simply moving people away from injections.
Lilly launched Foundayo in April, about three months after Novo Nordisk introduced an oral version of Wegovy, and Medicare coverage began July 1. The survey put Foundayo at 27% of new oral GLP-1 starts and indicated physicians expect a 40% share by 2028 or 2029.
The next hard test is Lilly's Oct. 29 earnings report. Investors will need prescription trends and management commentary to show whether survey intentions are turning into durable demand, especially as Novo's pill remains a credible competitor despite food-and-water restrictions.
VIX Options Show Investors Paying for Protection Beyond the AI Sell-Off

The Cboe Volatility Index rose above 22 for the first time in four months as selling in AI-related shares spread across the Nasdaq. Options activity then showed investors paying to keep protection in place beyond the immediate decline.
One trader bought 9,200 November 18 calls with a 20 strike for $1.7 million and 12,500 calls with a 23 strike for $1.1 million, according to CNBC. Across the ten most actively purchased VIX contracts that Friday, nine were calls and six had strikes above the index after its initial spike. Nearly $27 million of premium changed hands across those nine contracts, about 36% of all VIX options premium for the session.
The VIX reflects expected S&P 500 volatility derived from options prices over roughly the next 30 days. Buying calls can profit from a higher VIX or offset losses elsewhere, but the motive of any individual trader is not observable. The activity therefore demonstrates demand for protection, not certainty about the market's direction.
The trigger was concrete. The Nasdaq fell 2% in its worst session since June 5, and CoreWeave lost about 13% as investors focused on debt and financing risk across the AI infrastructure build-out. Upcoming results from Tesla and Meta add event risk because spending plans and guidance can quickly change expectations for the broader technology complex.
A high VIX can also fall quickly if earnings reduce uncertainty or stocks rebound. Investors should watch whether protection remains expensive after the reports, rather than treating one day's call purchases as a forecast. The durable signal would be sustained volatility alongside weaker earnings guidance or tighter credit, not the option volume by itself.
Nasdaq Rebound Ends a Brutal AI Week, but Expectations Still Set the Risk
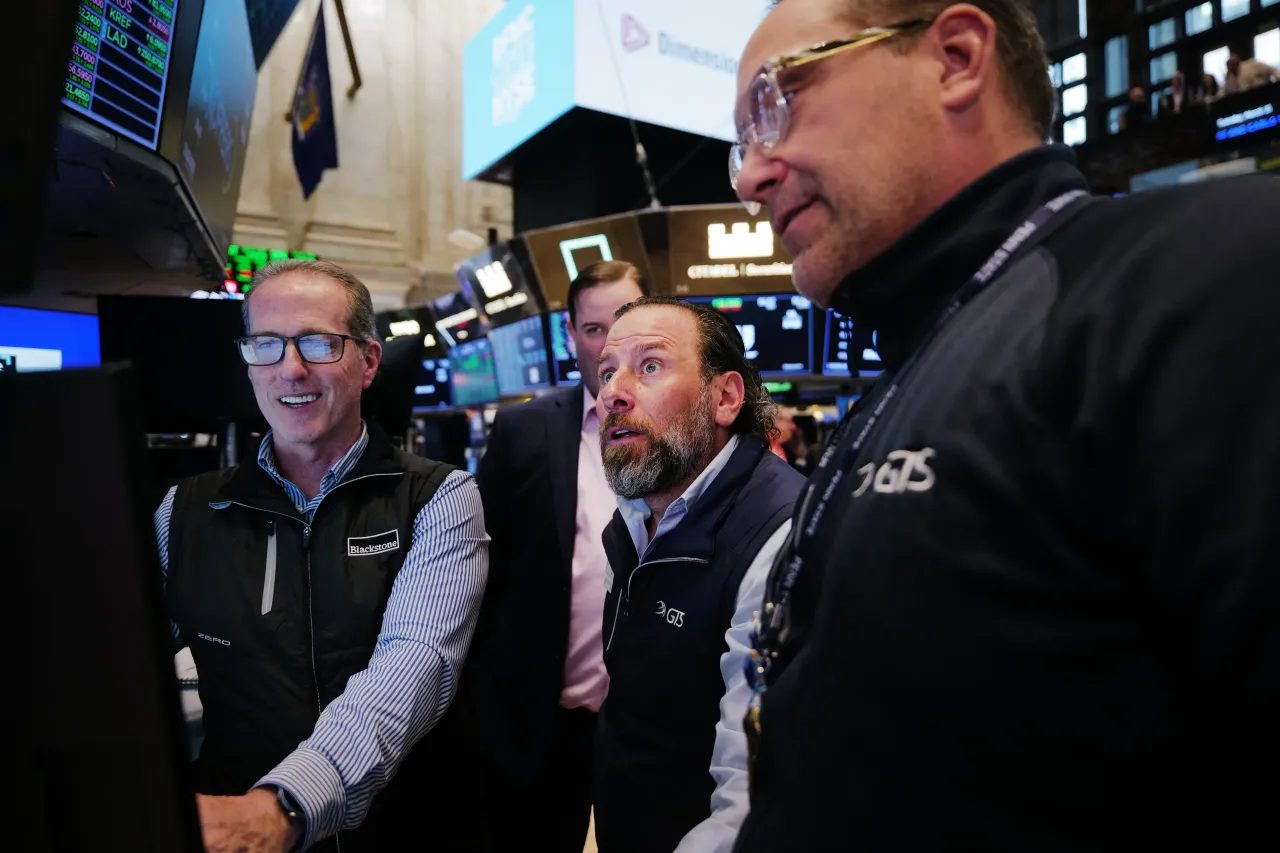
Technology shares rebounded sharply on Monday, giving the Nasdaq 100 its best day in nearly a month after a week that punished many of the market’s most crowded AI trades. Amazon, Apple and Palantir rose, while CoreWeave and other volatile infrastructure names recovered part of their recent losses. The move was broad enough to cool fears that the prior week’s decline had become a disorderly exit.
One session does not erase the damage. The Nasdaq Composite had fallen about 4.5% in the previous week, and semiconductor shares had endured a nine-session losing streak. CoreWeave, a focal point in the debate over AI capital spending, had dropped nearly 12% on Friday alone. Monday’s gains therefore looked partly like short-covering and bargain hunting after a rapid repricing.
The more durable support came from earnings. According to LSEG figures cited by CNBC, 47 S&P 500 companies had reported by Monday morning and 85% had beaten earnings estimates. Blended earnings growth was running near 29%. That is a strong start, but it also explains why investors are unforgiving: valuations embed continued profit growth, especially among the largest technology companies.
The key question is whether the rebound can move beyond a handful of megacaps and speculative AI names. A healthier recovery would combine stronger market breadth with company results that validate capital spending. For Amazon and other hyperscalers, investors need evidence that cloud and AI revenue can scale alongside depreciation and data-center costs. For infrastructure providers such as CoreWeave, financing costs and the pace of capacity delivery matter as much as booked demand.
The day’s rally is therefore best read as a reset in positioning, not proof that the AI correction has ended. Upcoming megacap earnings can support the market if revenue, margins and guidance justify expectations. They can also expose the same asymmetry that drove the selloff: when forecasts are already optimistic, even solid results may not be enough.
Earnings Week Tests Credit, AI Spending and the Consumer

The week of October 19 shifts attention from macro data to company execution. Capital One, Meta, Tesla, Netflix and a broad group of industrial, semiconductor, airline and consumer companies report while the economic calendar is relatively light.
Capital One will test consumer credit, funding spreads and Discover integration. Meta will put AI engagement against capital spending. Other reports make those events more informative: airlines and American Express can show whether consumers are absorbing higher fuel and borrowing costs, while Lam Research, Texas Instruments and Western Digital can reveal whether AI infrastructure demand is broadening.
The backdrop raises the standard for a positive reaction. The source report noted that some banks sold off despite headline beats as investors focused on margins, expenses and credit. Higher bond yields reduce the present value of future earnings, while hot inflation can keep the Fed restrictive.
This is more than an earnings calendar. The week provides connected tests of household resilience, AI monetization and industrial demand. Investors should compare credit losses, capital budgets and order trends across companies before drawing a broad conclusion from any single stock move.
Trump Media and Rumble Fell Faster Than the Market as Merger Risk Loomed
Trump Media fell 6% and Rumble dropped 8% during an October 16 market selloff, compared with a 1.4% decline in the S&P 500 proxy cited by the source. The gap is consistent with both stocks' smaller size and high sensitivity to changes in risk appetite, but the companies have different fundamental catalysts.
Trump Media's central event is its proposed all-stock merger with TAE Technologies. A September 30 SEC registration statement advances the approval process but remains preliminary. The filing says roughly 292.6 million new Trump Media shares are expected to be issued to TAE stakeholders based on then-current awards and warrants.
That share issuance would transform the company. TAE develops fusion energy, power management and cancer-therapy technology, while Trump Media operates Truth Social, streaming and financial brands. The merger could provide capital for TAE's development, but commercial fusion remains unproven and the transaction still requires approvals and completion conditions.
Rumble's exposure is more conventional. Its revenue depends on advertising, subscriptions, licensing and creator activity. A market selloff can pressure the shares, but its operating test is whether users, monetization and cash generation improve.
The one-day declines do not prove either business deteriorated that afternoon. They show how quickly valuation risk can surface when investors retreat from speculative equities. For DJT holders, the decisive evidence is the final merger terms, shareholder approval and the combined company's financing plan.
Latest comments