


 Be The Investor Research
AST SpaceMobile’s Launch Bottleneck Fuels Acquisition Speculation
An analyst argues AST SpaceMobile may need launch capacity or spectrum acquisitions, but no transaction has been announced and its deployment schedule remains the measurable issue.
AST SpaceMobile’s dependence on outside launch providers has become the basis for acquisition speculation, but the company has not announced a deal. Satellite consultant Tim Farrar suggested Firefly Aerospace as a possible smaller target and argued that buying a satellite operator would be a more ambitious move.
The comparison is Rocket Lab, which agreed to acquire Iridium in a transaction carrying an implied enterprise value of $8 billion. That deal would add established cash flow and network services to Rocket Lab’s launch and space-systems operations. Farrar’s argument is that AST SpaceMobile did not use its earlier equity valuation to make a similar move.
AST has left the door open. Its July convertible-note announcement said proceeds could support partnerships or acquisitions that vertically integrate the business and reduce reliance on third-party launch providers. That language is permission, not evidence that negotiations are underway.
The operational constraint is clearer than the acquisition theory. AST moved its 45-satellite deployment goal from the end of 2026 to early 2027, citing launch availability. The source report said BlueBird satellites 14 through 16 had reached Cape Canaveral, but the update did not include a firm launch date. Piper Sandler also cut its target and downgraded the stock, citing schedule concerns.
Investors should separate a consultant’s proposed strategy from company action. A signed launch contract, dated deployment plan or announced transaction would change the evidence. Until then, launch capacity and the pace of satellite deployment matter more than speculation about who AST might buy.
Continue your RKLB research
Related News
10x Genomics Led ARK's Q3 Gains While Tesla Dragged Across Funds
ARK's third-quarter attribution shows 10x Genomics as the biggest contributor to ARKG and a major boost to ARKK, while Tesla weighed on three funds. The figures measure portfolio contribution, not standalone stock returns.
SpaceX Profit and Tesla Merger Talks Send Shares Higher
SpaceX reported $14.6 billion of quarterly revenue and $4.4 billion of net income, while independent committees began studying a possible Tesla combination. No deal has been agreed.
Meta's New Share Class Prepares for an AI Funding Gap
Meta's planned non-voting Class C shares raise no cash initially, but they create a future equity-funding option as AI spending pushes quarterly free cash flow negative. The structure preserves Mark Zuckerberg's voting control.
Salesforce Pays a 58% Premium for Braze's Real-Time Data
Salesforce agreed to acquire Braze for $47.50 a share in cash, a $5.66 billion transaction that strengthens Marketing Cloud. The strategic fit is clear, but the premium and integration burden explain investors' caution.
Rocket Lab's Neutron Delay Leaves a Valuation Problem
Rocket Lab pushed Neutron's first launch into 2027 after finding defects in a composite propellant-tank dome. The company is fixing the process, but its premium valuation now depends on passing tests and setting a credible launch date.
Applied Digital's Growth Is Real, but So Is the Funding Risk
Applied Digital's first-quarter revenue surged as AI data-center capacity entered service, yet losses, debt and construction spending remain high. The next test is whether contracted capacity converts into recurring rent on schedule.
ServiceNow's $1 Billion AI Contract Milestone Raises the Bar
ServiceNow has crossed an important commercial threshold for its artificial-intelligence products: annual contract value tied to AI exceeded $1 billion in the second quarter. That milestone suggests enterprise demand has moved beyond pilots, but it also raises the standard the company must meet in its next results.
Second-quarter subscription revenue rose 24.5% to $3.88 billion, while total revenue increased 24% to $3.99 billion. Current remaining performance obligations, which represent contracted revenue expected within 12 months, grew 21% to $13.2 billion. Management raised full-year subscription revenue guidance to a range of $15.76 billion to $15.78 billion.
The product strategy is built around governing and coordinating AI agents across business processes. ServiceNow's AI Workflow Factory combines process mining, agent and application development, and a control layer intended to monitor what those agents can do. The company is arguing that enterprises need a common operating system for AI work, not a collection of disconnected tools.
That pitch is commercially plausible because security and governance are major barriers to deployment. It is still too early, however, to assume every AI contract represents entirely new spending. Some customers may be upgrading or reclassifying existing workflow budgets.
Valuation makes that distinction important. After a strong three-month rally, the shares trade at a much higher forward earnings multiple than they did in late June. The market is already assigning value to sustained AI demand, so ordinary subscription growth may not be enough to extend the move.
The next earnings report should answer two practical questions. First, can current remaining performance obligations continue growing near 20%? Second, will ServiceNow provide another clear measure of AI contract value or customer adoption? Continued gains in both would support the view that AI is expanding the platform's economics. Slower contract growth would suggest the share-price rally has moved ahead of the evidence.
Nokia’s AI and Cloud Orders Turn Network Growth Into a Measurable Business
Nokia’s third-quarter results gave investors concrete evidence that artificial intelligence demand is moving beyond chipmakers and into networking equipment. Net sales rose 10% from a year earlier to €5.15 billion, while comparable operating profit increased 35% to €605 million.
The strongest growth came from Network Infrastructure. Revenue in that division rose 15% on a constant-currency basis to €2.15 billion, with IP Networks up 43% and Optical Networks up 18%. These products carry data between servers and data centers, making them essential when AI workloads require larger and faster networks.
Nokia said revenue from AI and cloud customers increased 123%, while orders from those customers rose 118%. The company secured €1.5 billion of new AI and cloud orders during the quarter. That order figure is particularly useful because it shows demand beyond revenue already recognized.
The €1.5 billion of AI and cloud orders gives Nokia a measurable pipeline rather than only a long-term technology narrative.
Profitability improved, but not every indicator moved in the same direction. Comparable gross margin slipped 0.2 percentage points to 44.6%, while operating margin rose to 11.7%. The divergence suggests that volume growth and operating leverage helped offset some pressure at the gross-profit level.
Management maintained its 2026 comparable operating-profit outlook of €2.1 billion to €2.6 billion. It also expects the combined Optical and IP Networks businesses to grow between 25% and 30% in 2027. That target now has support from current orders, though investors still need to see how much of the backlog converts into revenue and cash.
Nokia is also expanding its work with Nvidia on AI-native radio access networks. The companies are combining Nokia software with Nvidia’s Aerial platform to improve signal processing, beamforming and network-resource allocation. Nokia said it completed an AI-RAN call in a live operator network with T-Mobile and Nvidia.
The investment case is becoming more specific: AI spending can benefit Nokia through data-center networking and telecom automation. The next evidence should come from backlog conversion, sustained margins and cash generation. If those measures improve together, the quarter could mark more than a temporary demand spike.
Apple Adds US Suppliers for Titanium and Advanced iPhone Camera Films
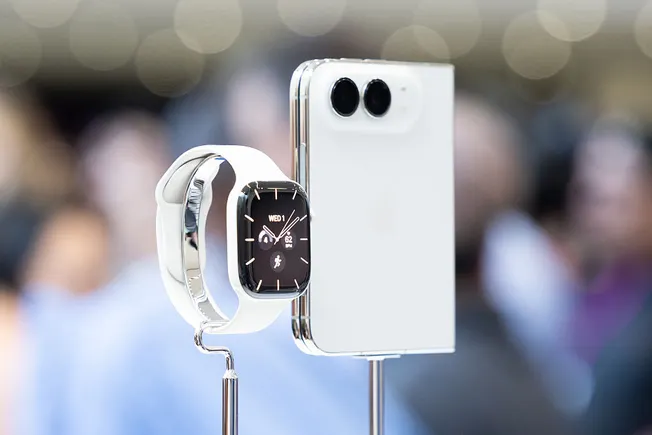
Apple is expanding its United States supplier network for materials used in the iPhone Duo and iPhone 18 Pro. The company added Perryman Company as a titanium supplier and expanded its relationship with Qnity Electronics, which produces advanced films for the iPhone 18 Pro camera system.
Apple committed up to $100 million over three years to Perryman, a Pennsylvania manufacturer that melts, forges and rolls titanium. Apple said the material contains at least 80% recycled content and will be used in iPhone Duo casings. The commitment provides a defined commercial opportunity for a domestic supplier, although Apple did not disclose unit volumes or pricing.
Qnity, based in Delaware, will supply advanced films for the variable-aperture system in the iPhone 18 Pro’s 48-megapixel main camera. A variable aperture changes how much light reaches the sensor, giving the camera more control across different conditions. The expanded agreement links a specialized US material supplier to a visible product feature rather than a generic localization pledge.
The new contracts add domestic capacity for specific components, but Apple still relies on a global network spanning more than 60 countries.
The agreements are part of Apple’s American Manufacturing Program and its four-year, $600 billion commitment to US manufacturing. Apple says it works with suppliers in all 50 states and supports more than 450,000 jobs. US companies now make nearly 100 components for the iPhone Duo and iPhone 18 Pro across more than a dozen states.
Apple has also expanded domestic sourcing for radio-frequency components, cover glass and semiconductor packaging. Broadcom announced a $1.5 billion modernization of its Fort Collins facility within a larger multiyear Apple agreement, while Corning is expected to produce all cover glass for iPhones and Apple Watches at its Kentucky site by year-end.
For investors, the strategy can reduce exposure to trade restrictions and improve political support in the United States. It may also raise costs if local manufacturing is more expensive than established Asian supply chains. Apple has not provided enough detail to calculate the margin effect of the Perryman and Qnity agreements.
The most useful evidence will be product volumes, supplier investment and any change in component costs. The announcement shows a real shift in sourcing, but not a wholesale relocation of iPhone production.
Alphabet’s AI Spending Creates More Upside and More Risk Than Apple’s
Alphabet and Apple are taking different paths through the artificial intelligence investment cycle. Alphabet is spending aggressively on data centers and models, while Apple has committed far less capital and continued returning large amounts of cash to shareholders. The contrast gives investors a clear trade between faster growth and greater financial risk.
Alphabet reported second-quarter 2026 revenue of about $119.8 billion, up 24%, while Google Cloud grew 82%. Its spending was equally dramatic. Capital expenditure reached roughly $44.9 billion in the quarter, and management’s full-year outlook rose as high as $185 billion. The company’s quarterly free cash flow turned negative in the original analysis, while long-term debt increased.
Apple’s June-quarter revenue rose 16% and management guided to 9% to 11% growth for the following quarter. Apple spent about $2.5 billion on property and equipment during the period and returned $33 billion to shareholders through dividends and buybacks. It also raised the quarterly dividend to $0.27 and authorized another $100 billion of repurchases.
Alphabet offers stronger operating growth and a cheaper forward earnings multiple, but Apple currently converts more of its scale into shareholder distributions.
The valuation gap reflects that trade. The original analysis placed Alphabet near 23 times forward earnings and Apple around 35 times. Alphabet’s trailing earnings were boosted by a large securities gain, so the forward comparison is more useful than the lower trailing multiple. Apple’s premium assumes that its brand, installed base and cash generation can offset slower AI investment.
Neither approach is free of risk. Alphabet must prove that cloud growth, advertising and AI products can earn adequate returns on unprecedented capital spending. If demand or pricing disappoints, depreciation and financing costs will remain. Apple risks falling behind in AI capabilities while paying investors less current growth for a higher valuation.
The investment choice therefore depends on time horizon and tolerance for volatility. Alphabet may offer more upside if the infrastructure produces durable revenue and margin expansion. Apple may suit investors who value buybacks, dividends and a less capital-intensive path, but its valuation provides little protection if growth slows.
Investors should watch free cash flow, capital intensity and revenue generated by new AI products. Those measures will reveal whether Alphabet’s spending advantage becomes an earnings advantage, or whether Apple’s restraint proves more valuable.
Latest comments