


MSFT Stock Forecast 2026: Is Microsoft Overvalued? AI Growth, Valuation and FCF Risk
Microsoft stock research dated October 9, 2026: verified FY2026 fundamentals, Azure expansion, AI infrastructure spending, cash-flow conversion, BTI valuation model assumptions, analyst disagreement and investor scenarios.
MSFT Stock Forecast 2026: Is Microsoft Overvalued? AI Growth, Valuation and FCF Risk
Microsoft is one of the highest-quality businesses in public markets. That does not automatically make MSFT attractive at every price.
On October 9, 2026, JINI analyzed Microsoft at a near-real-time reference price of $522.61. The conclusion was not bearish on the company. It was disciplined on the stock:
 JINI combines business fundamentals, valuation, market data, analyst expectations and portfolio context into one Microsoft research workflow.
What This MSFT Stock Forecast Will Cover
This research guide will examine:
- Microsoft's operating performance and business model;
- Azure and AI as the main growth engine;
- the gap between accounting earnings and free cash flow;
- why AI capex is the swing factor in valuation;
- BTI's EPS/FCF, Revenue and TAM model outputs;
- why model convergence can still be misleading;
- Wall Street analyst expectations;
- institutional positioning;
- key risks and catalysts;
- a practical case study for deciding whether MSFT is attractive at $522.61;
- what would cause the JINI thesis to become more bullish or more cautious.
Microsoft Stock Snapshot
The JINI research package captured the following market snapshot:

- Price: $522.61
- Session move: -1.35%
- Market cap: about $3.88 trillion
- 52-week range: $349.20 to $553.72
- P/E: about 29.1x
- Revenue growth: about 20.0%
- Beta: about 1.1
- Dividend yield: about 0.8%
The price was close to the upper end of its 52-week range, which is consistent with a market already assigning Microsoft a premium valuation.
Step One: Understand What Microsoft Actually Sells
Microsoft is not one business.

It is a portfolio of deeply integrated platforms.
Its major economic engines include Azure, Microsoft 365, Dynamics 365, LinkedIn, GitHub, Windows, Xbox, search advertising, server products and enterprise AI solutions.
Microsoft reports three broad segments:
- Productivity & Business Processes;
- Intelligent Cloud;
- More Personal Computing.
The reason this matters for valuation is diversification.
Microsoft does not depend on a single product cycle. Enterprise subscriptions, cloud consumption, software licensing, gaming, devices and advertising create several revenue streams with different economics.
Recurring subscriptions and high switching costs provide stability. Azure provides usage-based growth. Windows and Office provide distribution. GitHub and developer tools deepen Microsoft's relationship with software builders. Copilot and Agent 365 are attempts to monetize AI inside workflows Microsoft already controls.
Investor Question: Is Microsoft's AI advantage mainly a technology advantage, or a distribution and governance advantage built on existing enterprise workflows?
Azure Is the Growth Engine
Management said Azure surpassed $100 billion in fiscal 2026 and grew 41%.
This is distinct from the broader Microsoft Cloud, which surpassed $214 billion and grew 27%.
For investors, Azure matters for three reasons.
1. It Is Large Enough to Move the Entire Company
Azure is no longer a small growth business sitting inside a mature software company. It is now one of the central drivers of consolidated Microsoft growth.
2. AI Demand Is Adding Capacity Pressure
CFO Amy Hood said demand continued to exceed available supply.
That statement supports the growth narrative, but it also explains why capital expenditure has become so large.
3. AI Monetization Is Expanding Beyond Infrastructure
Microsoft is trying to monetize AI at several layers:
- Azure infrastructure;
- Copilot subscriptions;
- GitHub Copilot;
- security products;
- Agent 365 and enterprise governance;
- local AI on Windows PCs;
- developer and data tooling.
The investment thesis therefore depends on more than GPU demand.
Microsoft is attempting to become the software, identity, security and governance layer through which enterprises deploy AI.
Step Two: Read the Financial Performance
Microsoft's fiscal 2026 operating performance was strong.
JINI's financial summary shows that FY26 revenue reached approximately $331.8 billion, up about 18%, while operating income reached $155.2 billion, up about 21%.
Quarterly financial data in the research package showed:
- June 2026 revenue: $90.0B
- June 2026 net income: $35.8B
- June 2026 free cash flow: $19.6B
- June 2026 operating income: $40.6B
- June 2026 EPS: $4.80
The operating economics are difficult to criticize.
A 46.8% operating margin at Microsoft's scale is exceptional.
The debate begins after operating profit.

The Key Debate: Capex Versus Free Cash Flow
Microsoft's FY26 free cash flow fell to about $67.0 billion from $71.6 billion even as revenue and operating income increased.
The reason is capital expenditure.
FY26 capex rose to roughly $115.9 billion.
Cash-flow mechanics: The FY2026 reported cash-flow statement shows roughly $182.9 billion in operating cash flow and $115.9 billion in cash purchases of property and equipment, leaving about $67.0 billion of free cash flow. This is a cash-flow calculation, not a comparison of all capital commitments, and leases can create definitional differences.
 Reported FY2026 operating cash flow less cash purchases of property and equipment. Source: Microsoft FY2026 Q4 earnings release. Figures rounded; this is a cash-flow bridge, not total capex including finance leases.
This is a central number in the MSFT valuation debate, but definitions matter: the $115.9 billion figure represents cash additions to property and equipment, not every lease-related capital commitment.
FY26 capital expenditure compared with free cash flow. Source: JINI / BTI Microsoft research package.
Accounting earnings tell us the company is extraordinarily profitable.
Free cash flow tells us an extraordinary amount of cash is also being reinvested.
The investment question is whether that reinvestment produces future returns above Microsoft's cost of capital.
Investor Question: Is Microsoft's lower FCF margin a temporary consequence of building AI capacity ahead of demand, or the beginning of a permanently more capital-intensive business model?
Management's Argument: Capex Is More Flexible Than It Looks
Amy Hood described a shift toward what she called “short-lived assets.”
The argument is important.
If much of Microsoft's capex consists of servers, accelerators and other equipment that can be purchased or throttled relatively quickly, management may have more flexibility than a company locked into decades-long infrastructure projects.
That creates a potentially favorable feedback loop:
- demand remains strong;
- Microsoft adds capacity;
- Azure monetizes that capacity;
- if demand slows, equipment purchases can be reduced;
- free cash flow can recover.
But the thesis has to be proven.
High capex is only attractive if incremental investment generates attractive incremental cash flow.
 Illustration only, not FY2027 guidance or a forecast. FCF increases of $10B and $25B are hypothetical and do not translate directly into a share-price target.
Worked example (hypothetical): If the same revenue and operating economics allowed annual free cash flow to increase by $10 billion, FCF would rise from roughly $67 billion to $77 billion, or about 15%. A $25 billion improvement would bring it to $92 billion, about 37% above the FY2026 base. This does not mean the stock should rise by those percentages: a valuation also depends on discount rates, duration, capital intensity, share count and what the current price already anticipates.
Step Three: What the BTI Valuation Models Say
JINI reported three High-suitability valuation models.
 BTI model outputs and analyst consensus are estimates, not realized prices. Reference date: October 9, 2026. Source: supplied JINI research package; not independently verified from market feeds.
- EPS / FCF Model: $438.10 fair value, -16.2%
- Revenue Model: $443.09 fair value, -15.2%
- Total Addressable Market Model: $438.10 fair value, -16.2%
Microsoft looks approximately 15% to 16% overpriced.
But a professional investor should not stop there.
Why Model Convergence Is Not the Same as Independent Confirmation
The three fair values are extremely close, but their similarity does not necessarily imply independent corroboration.
That sounds reassuring.
But JINI correctly identified an important limitation: the models share assumptions.
The TAM output was identical to the EPS/FCF output in the package.
That means it should not be treated as a completely independent third confirmation.
The models also share the same central problem: current free cash flow is depressed by enormous capital expenditure.
If capex later normalizes while revenue remains strong, FCF could rise materially and the valuation outputs could move higher.
Practical rule: Three similar model outputs are only powerful evidence when the models arrive there through genuinely different economic assumptions.
EPS / FCF Model: Why It Is Cautious
The EPS / FCF model used a five-year framework with assumptions including:
- 17.8% revenue growth;
- 40% net margin;
- 29x exit P/E;
- 40x exit P/FCF;
- 10% required annual return.
The fair value was $438.10.
The major drag was free cash flow.
JINI estimated an FCF margin of only about 20.2%, far below the roughly 40% net margin.
That gap exists because of the AI infrastructure buildout.
This model therefore becomes much more bullish if one assumption changes:
capital intensity normalizes while operating growth remains strong.
Revenue Model: Why It Reaches a Similar Value for a Different Reason
The Revenue Model produced a fair value of $443.09.
It used an exit EV/Sales multiple of about 10.1x with similar growth assumptions.
The limitation is different.
A revenue multiple does not directly reward Microsoft's exceptional operating-margin quality.
Two companies with the same revenue can deserve very different valuations if one produces a 47% operating margin and the other produces 15%.
So a revenue model can understate value if it does not adequately capture superior economics.
The Valuation Disagreement Is the Real Story
Other valuation signals were more positive.
JINI reported that a separate BTI fair-market-cap framework, based on an earnings blend and a 32x AI-infrastructure P/E tier, implied Microsoft traded about 12.6% below fair value.

Wall Street analysts were also more optimistic.
The average analyst price target was $587.63, implying about 12.4% upside from $522.61.
The analyst range was wide:
- High target: $870
- Low target: $440
- Consensus: Strong Buy
- 69 analysts: 64 Buy, 5 Hold, 2 Sell

How quickly can Microsoft's AI investment convert into free cash flow?
Step Four: What Management Said on the Earnings Call
Two management comments frame the thesis.
Satya Nadella: “Azure surpassed $100 billion, up 41%.”
This supports the demand side of the investment case.
Amy Hood: “demand continues to exceed available supply.”
This supports the capacity-investment case.
Together, the message is:
Microsoft is not spending heavily because demand has disappeared. It is spending heavily because current capacity is insufficient for demand.
That is the bullish interpretation.
The skeptical interpretation is that infrastructure spending can outrun economic returns even during a period of strong demand.
Step Five: Institutional Positioning Is Mixed
JINI's 13F sample did not show a simple institutional-buying signal.
- 229 holders in the sample;
- 100 increased positions;
- 103 reduced positions;
- no broad consensus direction.
Notable increases included Artemis Investment Management, Zevenbergen Capital and Quintet Private Bank.
Bell Asset Management was among the notable sellers.
This data should be interpreted carefully.
13F filings are quarterly and typically arrive with a delay of roughly 45 days.
They show historical positioning, not real-time trades.
Institutional activity is therefore useful as context, not as a timing signal.
Step Six: Risks That Matter More Than the Daily Stock Move
1. Capex May Not Earn Its Return
Microsoft itself warns that AI investments may fail to achieve expected returns.
This is the central valuation risk.
2. OpenAI Dependency
The JINI research package highlighted concern around partner-driven Azure demand. If a major AI partner grows more slowly than expected, part of the infrastructure thesis may need to be revised.
3. Valuation Leaves Less Room for Error
With the stock at $522.61 and cash-flow models in the $438–$443 range, a slowdown could create both earnings pressure and multiple compression.
4. Regulation and Operating Friction
Microsoft operates across cloud infrastructure, labor markets, AI governance, privacy and competition regulation. New restrictions can increase cost even when they do not impair the long-term business thesis.
5. Supply Constraints Can Become Execution Constraints
Demand exceeding supply is bullish until capacity shortages delay revenue, raise costs or force uneconomic spending.
Step Seven: Catalysts That Could Move the Thesis
Q1 FY2027 Earnings
The research package listed consensus around $90.7 billion of revenue and $4.72 of EPS for the next expected report.
The important questions are not only whether Microsoft beats those numbers.
Watch Azure growth and free-cash-flow recovery.
E7 and Agent 365 Monetization
Enterprise AI governance may become a new monetization layer on top of Microsoft's existing identity, security and productivity stack.
Local AI Windows PCs
New Surface and partner hardware could create another premium category if local AI becomes economically useful to customers.
FY27 Capex Guidance
This may be the single most important valuation catalyst.
If capex growth moderates while Azure remains strong, BTI's FCF-based valuation could improve materially.
Case Study: Should an Investor Add MSFT at $522.61?
Now combine the evidence.
The Business Case
Microsoft remains one of the strongest large-cap businesses in the market.
- Azure grew 41%.
- FY26 revenue grew about 18%.
- Operating income grew about 21%.
- Operating margin reached 46.8%.
- The company has several recurring and high-switching-cost revenue streams.
That is the bull case for quality.
The Valuation Case
Three High-suitability BTI models placed fair value around $438–$443.
At $522.61, that suggests the stock price already discounts substantial execution.
The Counterargument
The models may be overly influenced by current FCF because capex is unusually high.
If infrastructure investment normalizes after the capacity buildout, free cash flow could rebound.
The Analyst Case
Wall Street's average target of $587.63 implies upside rather than downside.
Analysts appear to place more weight on Microsoft's earnings quality, growth durability and AI monetization than BTI's cash-flow-constrained models currently do.
The Decision

HOLD makes sense when a world-class business is priced above conservative cash-flow fair value but still has credible operating evidence that could raise future fair value.
The decision becomes more attractive if the price moves closer to the high-$430s/$440s model zone or if free cash flow begins recovering while Azure remains strong.
What Would Make the JINI Thesis More Bullish?
- Free-cash-flow margin begins recovering.
- Capex growth slows without hurting Azure growth.
- Azure continues growing around the current high rate.
- Agent 365 and Copilot monetization raise ARPU.
- Analyst earnings estimates move higher without additional multiple expansion.
- The stock price approaches or falls below the conservative BTI valuation zone.
What Would Make the Thesis More Cautious?
- Azure growth slows materially.
- AI capex remains above $100B annually without stronger FCF.
- OpenAI or other AI workloads disappoint.
- Operating margin begins compressing.
- Analyst estimates fall while the stock remains near a premium multiple.
- AI infrastructure overcapacity emerges across the industry.
MSFT Stock Forecast 2026: The Practical Takeaway
The simplest interpretation is not “Microsoft is overvalued.”
It is:
Microsoft's current valuation assumes that today's extraordinary AI investment will eventually translate into extraordinary free cash flow.
That is plausible.
It is not yet fully visible in the cash-flow statement.
The stock therefore sits in an unusual position.
The business can continue getting better while the stock remains fully valued.
That is why a HOLD rating can be fundamentally bullish on the company while still being disciplined on entry price.
What About an MSFT Stock Forecast for 2030?
Long-term forecasts are much less precise than one-year valuation work.
The research package supports several durable advantages — Azure scale, enterprise distribution, recurring subscriptions, GitHub, security, productivity software and AI governance.
But it does not provide a verified 2030 price target.
A responsible long-term forecast should therefore focus on what would drive value rather than invent a precise 2030 number.
The most important long-term variables are:
- Azure growth and market share;
- Copilot and Agent 365 monetization;
- AI infrastructure returns on capital;
- free-cash-flow recovery;
- share repurchases;
- regulatory constraints;
- the valuation multiple investors are willing to pay once AI growth normalizes.
Why Analyst Targets and Model Fair Value Can Disagree
It is tempting to assume that one side must be wrong when analysts see upside and a cash-flow model sees downside.
That is not necessarily the case.
Different frameworks answer different questions.
An analyst target may place more weight on forward earnings, competitive position, Azure growth and future AI monetization. A cash-flow model may place more weight on the amount of capital that must be spent before those future economics are realized.
For Microsoft, this distinction is especially important because the company is simultaneously producing elite operating margins and absorbing enormous amounts of cash into data-center capacity.
The analyst target of $587.63 says the market may be underestimating the future earnings power of Azure, Copilot, enterprise AI and Microsoft's software distribution.
The $438–$443 BTI cash-flow model zone says today's price may already be capitalizing much of that future success before the free cash flow has fully arrived.
Those are not mutually exclusive statements.
The company can execute well while stock returns lag if the purchase price has already capitalized future success.
Investor Question: Are you paying for future AI economics before the cash-flow evidence arrives, or is the current capex build creating a temporary valuation distortion that the market is correctly looking through?
A Practical Bear, Base and Bull Framework Without False Precision
The JINI package does not provide a verified three-price Bear/Base/Bull table for Microsoft, so it would be misleading to invent one.
Instead, we can build an evidence-based scenario framework around the variables that actually drive the thesis.
Bear Case: Capex Stays High and FCF Does Not Recover
In the bear case, Azure continues growing but at a slower rate, infrastructure spending remains elevated and free-cash-flow conversion fails to improve.
Under that environment, the high-$430s/$440s BTI model zone becomes more relevant because the market would be forced to value Microsoft on cash returns rather than on expected future AI monetization.
A multiple contraction could occur even if the business remains profitable.
Base Case: Growth Remains Strong but the Stock Is Fully Valued
In the base case, Azure remains strong, enterprise AI adoption expands and operating margins remain excellent.
Free cash flow improves gradually rather than immediately.
That supports a HOLD interpretation: the company thesis remains intact, but the expected return from the current price is less compelling than the underlying business quality.
Bull Case: AI Capacity Converts Into High-Return Cash Flow
In the bull case, Microsoft's current data-center build becomes a temporary investment phase.
Azure stays near the current high growth rate, Copilot and Agent 365 expand monetization, capex growth slows and free cash flow begins catching up with net income.
That would weaken the argument behind today's conservative FCF-based fair values and make the more optimistic analyst view easier to defend.
The purpose of these scenarios is not to choose the one you prefer.
It is to identify the evidence that tells you which scenario is becoming more likely.
How to Read HOLD Correctly
A HOLD rating is often misunderstood as a weak opinion.
In this case, it is actually a very specific conclusion.
JINI is not saying Microsoft's business is average.
It is saying the business quality is high enough that selling purely because of valuation may be premature, while the current price and cash-flow profile do not justify aggressive new buying.
That is an important difference.
A great company can remain a HOLD for a long period if valuation already reflects much of the expected growth.
The investor should therefore separate three questions:
- Would I want to own Microsoft as a business?
- Would I want to buy Microsoft at $522.61?
- Would I want Microsoft to become an even larger percentage of an already technology-heavy portfolio?
Those questions can produce different answers.
The first may be yes.
The second may be not yet.
The third may be no.
Practical MSFT Research Checklist
Before changing a Microsoft position, an investor can monitor the following evidence rather than reacting to daily price movements:
- Azure growth: Is growth staying near levels that justify continued capacity expansion?
- Free-cash-flow margin: Is FCF beginning to recover as new infrastructure starts producing revenue?
- Capex growth: Is spending still accelerating, or is the buildout beginning to normalize?
- Operating margin: Is Microsoft preserving elite profitability despite AI infrastructure costs?
- Copilot and Agent monetization: Are AI products creating measurable ARPU uplift?
- Analyst revisions: Are earnings estimates rising because of operating results, or are price targets rising mainly because the market multiple expanded?
- OpenAI-related demand: Is partner-driven usage continuing to support Azure capacity economics?
- Portfolio concentration: Would adding MSFT improve the portfolio or simply increase exposure to the same technology risk factor?
A research process becomes stronger when each new quarter answers a question that was written down before the report.
Frequently Asked Questions
Is MSFT stock overvalued?
In the JINI snapshot, BTI's three High-suitability models placed fair value around $438–$443 versus a market price of $522.61, suggesting roughly 15%–16% overvaluation under those assumptions. Other BTI and analyst frameworks were more positive.
What is Microsoft's biggest valuation risk?
The biggest risk is that massive AI and data-center capex does not convert into enough future free cash flow to justify today's premium valuation.
Why is Microsoft's FCF lower than its net income margin?
Microsoft is investing heavily in AI infrastructure. Fiscal 2026 capex reached roughly $115.9 billion, which depressed free cash flow despite strong accounting earnings.
What could make MSFT fair value rise?
A combination of sustained Azure growth, slower capex growth and stronger free-cash-flow conversion would materially strengthen the cash-flow-based valuation case.
What is the analyst target for MSFT?
The JINI research package showed an average analyst target of $587.63 from 69 analysts, with a range from $440 to $870.
Why did JINI rate Microsoft HOLD instead of SELL?
Because the business quality, earnings growth and AI opportunity remain strong. The concern is entry valuation and cash-flow conversion, not a broken company thesis.
What price would make MSFT more attractive?
JINI highlighted the high-$430s/$440s as the area where conservative BTI model values begin to converge with the market price. That is a model zone, not a guaranteed buy level.
Research Method and Source Discipline
This article is based on the JINI Microsoft investment-research package generated on October 9, 2026.
Primary-source verification (reported financial data): Microsoft FY2026 Q4 earnings release and cash-flow statement; Microsoft FY2026 Q4 earnings call; Microsoft operating metrics. The stock-price snapshot, analyst-target set, portfolio sample and BTI valuations are carried over from the supplied JINI package and have not been independently verified here.
The package combines BTI market data, company financial statements, analyst estimates, earnings-call commentary, BTI news, valuation-model outputs and institutional-ownership data.
Market prices may be delayed. 13F holdings are lagged. Analyst targets are opinions. Valuation-model outputs depend on stated assumptions.
The most important distinction is between:
- reported facts such as revenue, operating income and capex;
- estimates such as analyst targets and consensus forecasts;
- model outputs such as $438–$443 BTI fair values;
- JINI analysis that interprets how those facts and estimates fit together.
Disclosure: This article is for educational and analytical purposes only. It is not personalized investment advice, an offer, a solicitation or a guarantee of future performance. Investors should verify current market data, filings, tax considerations and portfolio risk before acting.
Analyze Microsoft with BTI · Open the Stock Valuation Calculator · Open the Microsoft Stock Page
Popular AI leaderboard Arena nearly doubles valuation to $3.1B valuation in 10 months
Mecka AI Nears a $500 Million Valuation as Robot Training Data Becomes the Next Scarce AI Resource
Continue your MSFT research
Related News
Anthropic's IPO Filing Shows Enterprise Scale and Capital Intensity
Anthropic's public S-1 reveals 1,900 customers generating at least $1 million each over 12 months, alongside the cash reserves and funding demands behind frontier AI.
UiPath Improved, but Valuation Still Explains Its Microsoft Gap
UiPath's operations have improved sharply since 2021, yet its stock still trails Microsoft because the market has erased most of the premium once attached to its sales.
Arista's $3 Billion Quarter Raises the Bar for Its AI Premium
Arista Networks delivered 37.7% revenue growth and nearly 50% adjusted operating margin in the second quarter. Those results support its AI-networking premium, while customer concentration and supply commitments keep execution risk high.

Google Cloud’s 82% Growth Narrows the Gap, but Not on a Clean Basis
Google Cloud revenue surged 82% to $24.8 billion and its margin reached 35.6%. Claims that it could pass Azure within a year rely on incompatible revenue measures and unsustainable growth assumptions.
Nvidia's Supply Bottleneck Extends Into 2028, but Demand Quality Matters
Nvidia's filing confirms supply constraints and $279 billion of capacity commitments. Customer concentration and financing risk mean a long order queue is valuable only if buyers can fund and deploy the systems.
Chevron’s Next Test Is Cash Flow After a Record Quarter
Chevron enters its October 30 report after record production, refining profits and cash flow. Investors must separate durable operating gains from benefits tied to high oil prices, working capital and unusually strong refining margins.
Microsoft and Oracle Have Similar AI Backlogs, Not Similar Risk
Microsoft ended fiscal 2026 with $678 billion of commercial remaining performance obligations, while Oracle reported $664 billion after its fiscal first quarter. The two backlogs are close enough to invite comparison, but they do not represent the same financial proposition.
Remaining performance obligations, or RPO, measure contracted revenue that has not yet been recognized. The metric can signal future demand, but it does not show how quickly revenue will arrive, how much capital is needed to deliver it or how concentrated the contracts are. Those differences separate Microsoft from Oracle more clearly than the headline totals.
Microsoft is funding AI from an established cash engine
Microsoft's fiscal fourth-quarter revenue reached $90.0 billion, up 17.8% from a year earlier. Azure and other cloud services grew 43%, and Microsoft Cloud revenue reached $59.3 billion. Even after large data-center investments, the company produced $19.6 billion of quarterly free cash flow.
The composition of the backlog also provides context. Commercial RPO grew 84%, but it increased 25% when OpenAI was excluded. Microsoft said roughly 30% of the total should be recognized within 12 months and the weighted average duration was 2.3 years. Nearly 90% of Microsoft Cloud revenue came from customers outside frontier-model companies, reducing dependence on a small group of AI labs.
Microsoft is also monetizing AI through software. Paid Microsoft 365 Copilot seats exceeded 30 million, giving the company a second route to earn a return on infrastructure spending. That does not remove execution risk, but it spreads the risk across Azure, Office, Dynamics and other businesses.
Oracle's growth requires more outside capital
Oracle's cloud infrastructure revenue grew 121% in fiscal Q1, and the company added more than $30 billion of AI cloud contracts, taking RPO to $664 billion. It delivered more than 300,000 GPUs to cloud customers and almost tripled capacity from the previous quarter. Demand is not the main uncertainty.
The funding model is. Oracle generated a record $23 billion of operating cash flow in the quarter, yet free cash flow was about negative $5 billion because of its infrastructure buildout. The company also completed a $20 billion at-the-market common-stock sale. Oracle said the structure of the new contracts did not create an incremental need to raise capital, and management has described customer prepayments and bring-your-own-hardware arrangements as partial protection.
Concentration and timing still matter. Oracle relies on a smaller number of very large AI contracts, and its source article said interest expense rose 55% to $1.4 billion. Management has not given a date for free cash flow to turn positive. A large RPO balance therefore offers revenue visibility, but it does not by itself prove attractive returns on the assets being built.
The useful comparison is cash conversion
Oracle's lower valuation can look appealing after a steep share-price decline, but the discount reflects real financing and execution risks. Microsoft trades at a higher multiple because investors can see positive free cash flow while capacity expands.
The next evidence is operational. Microsoft must sustain Azure growth while preventing AI investment from eroding margins. Oracle must keep capital spending within its plan, convert its backlog on schedule and show that cloud revenue can outrun depreciation, interest and dilution.
For investors, the similar RPO totals are the beginning of the analysis, not the conclusion. Backlog quality depends on duration, customer concentration, funding terms and eventual cash conversion. On those measures, Microsoft currently offers the steadier model, while Oracle offers more upside sensitivity if its capital-intensive expansion begins producing durable positive free cash flow.
AppLovin's 61% Slide Turns Its Next Quarter Into a Model Test
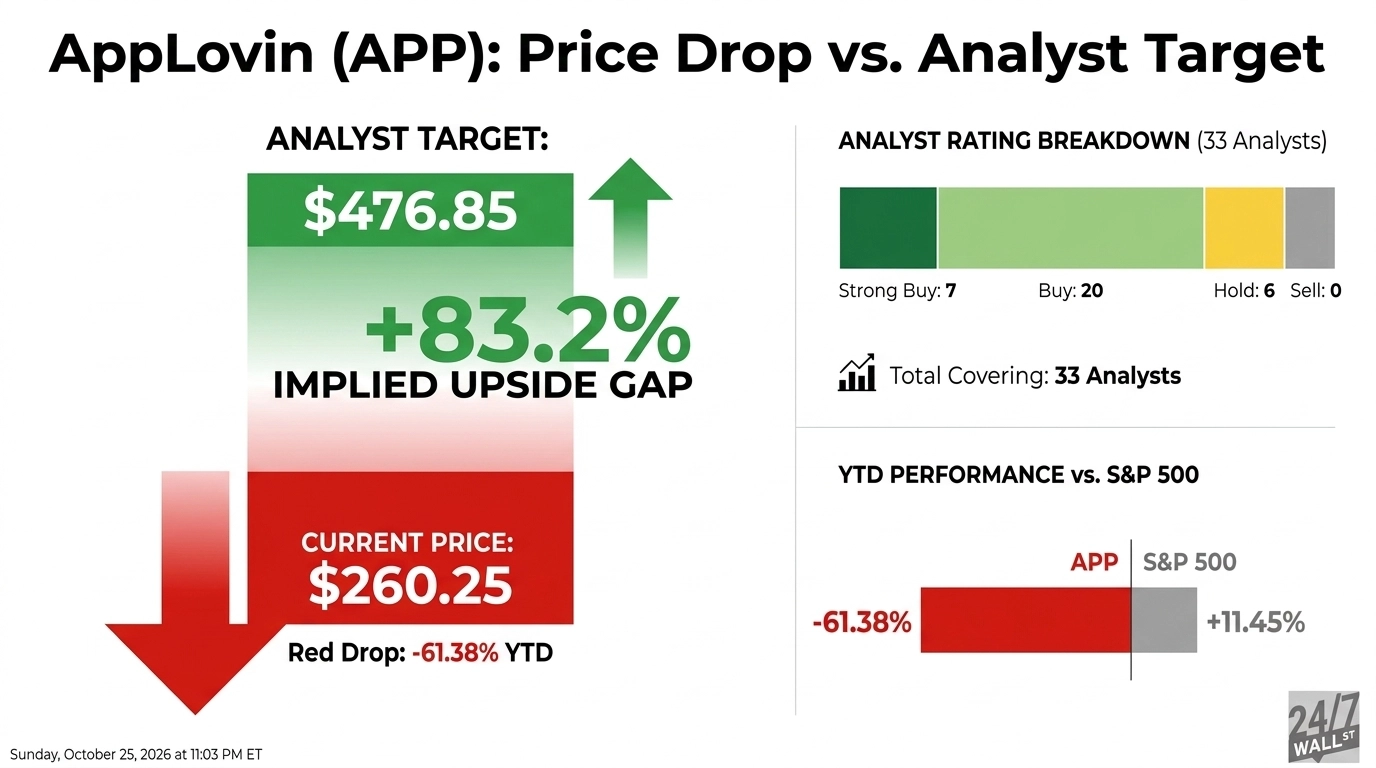
AppLovin's second-quarter results were strong in absolute terms, yet a small miss was enough to deepen a 2026 share-price collapse. The stock traded at $260.25 on October 26, according to 24/7 Wall St., down 61.38% for the year and close to its 52-week low. That reaction makes the next quarter a test of whether the setback was timing or a change in the growth engine.
The official results show why investors have not abandoned the company. Revenue rose 53% from a year earlier to $1.924 billion, net income increased 55% to $1.267 billion, and adjusted EBITDA climbed 58% to $1.614 billion. AppLovin generated $863.3 million of free cash flow and spent $551.3 million on share repurchases and tax withholding tied to vested awards.
The problem was the gap between a fast-growing business and even higher expectations. The source report says revenue missed estimates by 0.94%, while adjusted EBITDA fell below the guided range as computing costs rose. Chief Executive Adam Foroughi attributed the quarter's slower progress to the timing of model improvements, with the next meaningful upgrade arriving after quarter-end. Because AppLovin's AXON advertising system depends on repeated model gains, investors treated the timing issue as evidence that growth may be less predictable.
Management's third-quarter outlook points to continued expansion. The company guided for revenue of $2.055 billion to $2.085 billion and adjusted EBITDA of $1.710 billion to $1.740 billion, both with an 83% adjusted EBITDA margin at the midpoint and endpoints stated by the company. Meeting that range would show that the model improvement deployed after June is contributing to revenue. Missing it would strengthen the argument that the second-quarter stumble was not isolated.
The bullish case goes further. The source cites a $790 target from UBS analyst Stephen Ju, compared with a $476.85 average target across 33 analysts. Ju's view rests on AXON monetization, expansion from mobile gaming into e-commerce advertising, and free cash flow that can support buybacks. Those targets are opinions, not operating evidence, and even the consensus target implies a recovery that requires sustained execution.
There are also issues outside the quarterly model cadence. A securities class action challenges statements about model improvements, while the source says an SEC inquiry ended without a recommendation for enforcement action. The legal matters should not be treated as interchangeable. One remains active; the other, according to the report, closed without recommended action.
AppLovin is scheduled to report third-quarter results on November 4. Revenue, adjusted EBITDA margin and evidence of advertiser expansion will matter more than any price target. The company has already demonstrated high profitability and cash generation. It now has to show that those results can keep compounding when model upgrades do not arrive on a perfectly smooth schedule.
Alibaba's Cloud Growth Cannot Yet Offset Its Commerce and Cash Costs
Alibaba's 31% share-price decline in 2026 looks like a broad retreat from Chinese internet stocks, but the company's latest results show a sharper internal divide. Its cloud business is growing quickly, while core commerce and the cash cost of artificial intelligence investment remain meaningful constraints.
On October 26, 24/7 Wall St. reported Alibaba's U.S.-listed shares at $99.91, down 31% for the year. The KraneShares CSI China Internet ETF and PDD Holdings were each down about 32%, while JD.com was down 9% and the S&P 500 was up 12%. Those comparisons support the view that sector sentiment matters, but they do not show that Alibaba's businesses are standing still.
For the June 2026 quarter, Alibaba reported revenue of RMB268.95 billion, up 9% from a year earlier. AI Cloud and Compute Services revenue rose 45% to RMB48.44 billion, while AI-related product revenue reached RMB12.38 billion and posted triple-digit growth for a twelfth consecutive quarter. Segment adjusted EBITA increased 133% to RMB5.63 billion. Those figures provide the clearest evidence that cloud is becoming a larger and more profitable part of the group.
Commerce was less convincing. China e-commerce revenue fell 8%, and customer management revenue declined 7%. Alibaba said customer management revenue would have risen 1% on a like-for-like basis without the contra-revenue effect of a new business development program. China Quick Commerce revenue rose 45%, but that growth came alongside continued investment in user experience and technology.
The consolidated numbers show the cost of the transition. Reported operating income fell 57% to RMB15.16 billion, and net income declined 75% to RMB10.44 billion. Adjusted EBITA fell 30% to RMB27.33 billion. Free cash flow was an outflow of RMB44.67 billion, compared with an RMB18.82 billion outflow a year earlier, mainly because cloud infrastructure spending increased. Quarterly capital expenditure rose 75% to RMB67.68 billion.
Alibaba still had RMB474.51 billion of cash and other liquid investments at the end of June. That balance gives management room to fund AI infrastructure, but the spending has to translate into durable returns. The new AI Labs and Applications segment reported an adjusted EBITA loss of RMB13.86 billion, more than four times the RMB3.22 billion loss a year earlier, largely because of AI investment and Qwen app inference costs.
The investment question is therefore not simply whether Alibaba is cheap after falling with its peers. It is whether 45% cloud growth and improving cloud profitability can eventually outweigh slower commerce, heavy capital expenditure and rising application-layer losses. A sustained gap between Alibaba and the broader China internet index would be useful market evidence, but the stronger proof will come from cash flow and consolidated profit.
Cyprus' First Gas Project Turns a Discovery Into a 2028 Export Plan
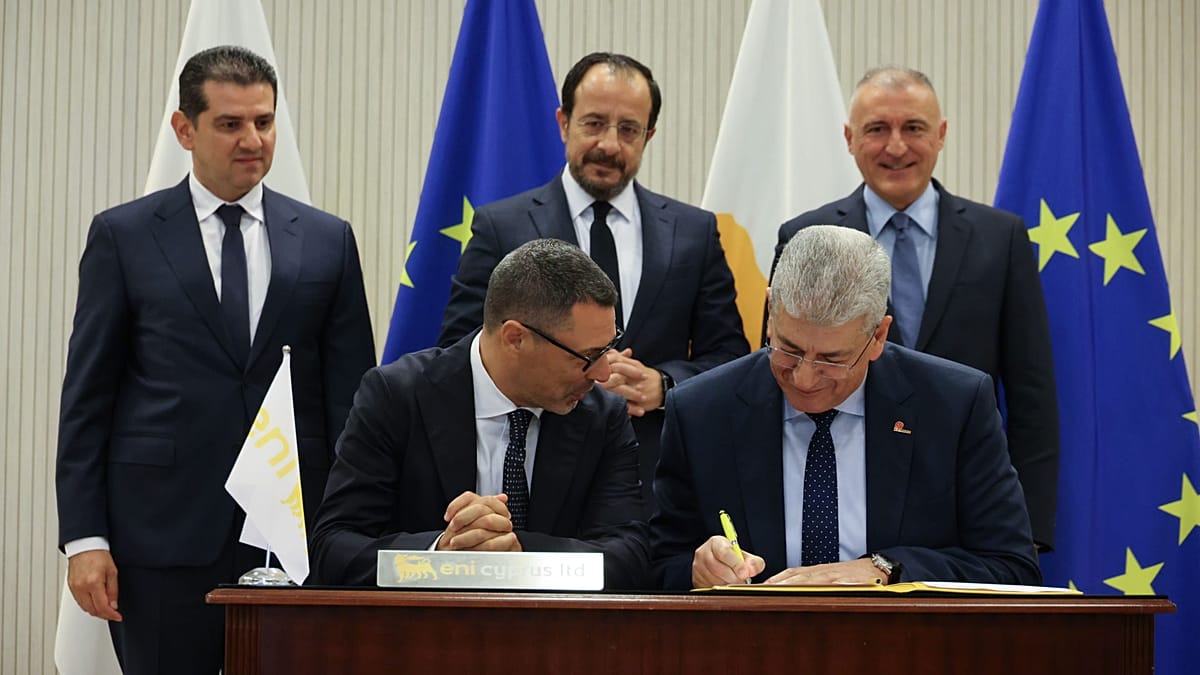
Cyprus has moved closer to producing natural gas for the first time. Eni signed infrastructure contracts worth up to $1.8 billion for the Cronos field, turning a discovery in Block 6 of Cyprus' exclusive economic zone into a construction program aimed at first production in 2028.
Eni operates the field with a 50% interest, while TotalEnergies owns the other 50%. The companies approved the development in July. Eni says Cronos contains more than 3 trillion cubic feet of gas and could produce as much as 500 million cubic feet a day once operations stabilize. At that plateau rate, annual output would be about 182.5 billion cubic feet, a BTI calculation that helps show the project's scale but does not account for ramp-up, downtime or reservoir decline.
The export route is central to the economics. Gas will travel by subsea pipeline to facilities linked to Eni's Zohr field in Egypt, then move to the Damietta liquefied natural gas plant for shipment to international markets, mainly Europe. Reusing Egyptian processing and liquefaction infrastructure should reduce the amount of new construction compared with building a complete export system in Cyprus. It also makes the project dependent on cross-border coordination and the availability of the Egyptian network.
The contracts cover the equipment and connections needed to make that route work. Baker Hughes is set to supply subsea production systems; Dalmine will work on export and transfer pipelines; TechnipFMC will handle flexible production lines; and McDermott will transport, install and commission subsea equipment. Oceaneering, CMHI, Petrojet and Saipem also have roles in controls, the floating unit, the Egyptian onshore pipeline and drilling.
For Eni and TotalEnergies investors, the signing is more important as evidence of execution than as immediate earnings. Revenue from gas sales is not expected before production starts, and the current target still depends on completing a complex offshore project on time. Commercial agreements, export capacity, safety performance and regional conditions will determine how much of the resource ultimately reaches paying customers.
Cronos is therefore a regional infrastructure story as much as a reserve story. Cyprus gains a route to monetize its first gas field, Egypt uses existing assets, and Eni and TotalEnergies can develop a deepwater discovery without creating a standalone liquefaction system. The next proof point is physical progress toward first-half 2028 production, not the headline value of the contracts alone.
Meta's $135 Billion AI Budget Shifts Attention to Amphenol

Meta's artificial intelligence budget is now large enough to shape results well beyond Meta itself. Aptus Capital Advisors portfolio manager David Wagner argues that the spending should be viewed from both sides: capital expenditure for Meta becomes revenue for the companies supplying data centers, networking equipment and cloud capacity.
That argument gained firmer numerical support in Meta's third-quarter results. The company spent $34.91 billion on capital expenditures, including principal payments on finance leases, during the quarter and narrowed its full-year 2026 forecast to $135 billion to $145 billion. Meta also said its AI investments are already lifting advertising revenue through better recommendations, engagement and monetization.
The cost is visible too. Meta generated $32.79 billion of operating cash flow in the third quarter but reported negative free cash flow of $2.12 billion. It ended September with $82.45 billion of cash, cash equivalents and marketable securities. The company has since said it plans to fund its infrastructure with a mix of operating cash flow, investment-grade debt, strategic partnerships and equity capital. That makes Wagner's point about debt capacity more specific: Meta has substantial resources, but the buildout is big enough to require several funding channels.
Amphenol is one way investors can express the supplier side of that thesis. The company sells connectors, cables and related systems into the IT and data communications market, making it exposed to the physical expansion of AI infrastructure. Wagner named Amphenol alongside Amazon and Meta among stocks he favors. The connection is economically plausible, but it is not a guarantee that every dollar of Meta spending reaches Amphenol. Customer mix, component pricing, competition and the shift between copper and optical connections will determine how much of the industry budget becomes Amphenol revenue.
The next company-specific check arrives quickly. Amphenol is scheduled to report third-quarter results on October 28. Investors can then compare the broad supplier thesis with actual IT and data communications sales, orders and guidance. Meta's spending plan supports demand, while Amphenol's own results will show how much of that demand it is capturing.
Latest comments