


 Be The Investor Research
AppLovin's 61% Slide Turns Its Next Quarter Into a Model Test
AppLovin's second-quarter revenue and cash flow still grew rapidly, yet a small revenue miss and slower model improvements changed the market's confidence. The November 4 report now carries unusual weight.
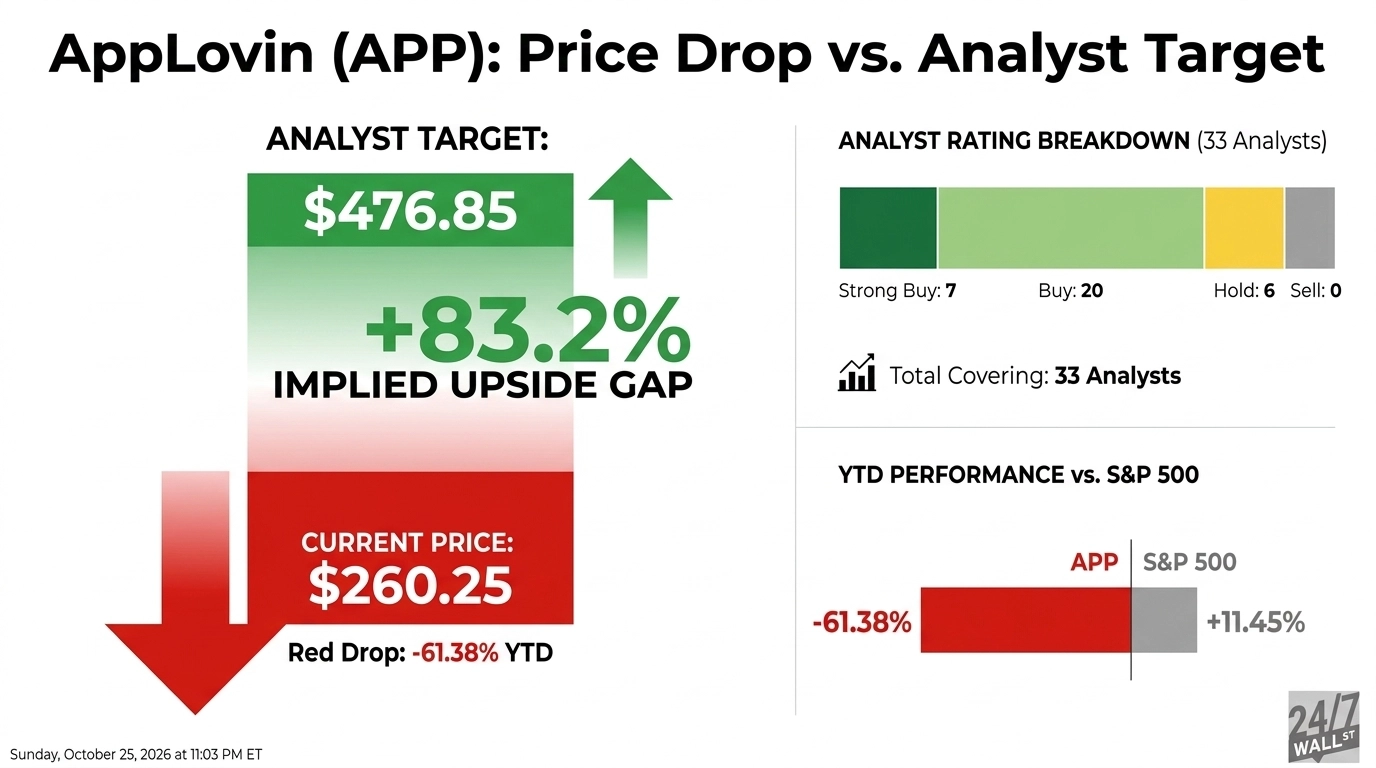
AppLovin's second-quarter results were strong in absolute terms, yet a small miss was enough to deepen a 2026 share-price collapse. The stock traded at $260.25 on October 26, according to 24/7 Wall St., down 61.38% for the year and close to its 52-week low. That reaction makes the next quarter a test of whether the setback was timing or a change in the growth engine.
The official results show why investors have not abandoned the company. Revenue rose 53% from a year earlier to $1.924 billion, net income increased 55% to $1.267 billion, and adjusted EBITDA climbed 58% to $1.614 billion. AppLovin generated $863.3 million of free cash flow and spent $551.3 million on share repurchases and tax withholding tied to vested awards.
The problem was the gap between a fast-growing business and even higher expectations. The source report says revenue missed estimates by 0.94%, while adjusted EBITDA fell below the guided range as computing costs rose. Chief Executive Adam Foroughi attributed the quarter's slower progress to the timing of model improvements, with the next meaningful upgrade arriving after quarter-end. Because AppLovin's AXON advertising system depends on repeated model gains, investors treated the timing issue as evidence that growth may be less predictable.
Management's third-quarter outlook points to continued expansion. The company guided for revenue of $2.055 billion to $2.085 billion and adjusted EBITDA of $1.710 billion to $1.740 billion, both with an 83% adjusted EBITDA margin at the midpoint and endpoints stated by the company. Meeting that range would show that the model improvement deployed after June is contributing to revenue. Missing it would strengthen the argument that the second-quarter stumble was not isolated.
The bullish case goes further. The source cites a $790 target from UBS analyst Stephen Ju, compared with a $476.85 average target across 33 analysts. Ju's view rests on AXON monetization, expansion from mobile gaming into e-commerce advertising, and free cash flow that can support buybacks. Those targets are opinions, not operating evidence, and even the consensus target implies a recovery that requires sustained execution.
There are also issues outside the quarterly model cadence. A securities class action challenges statements about model improvements, while the source says an SEC inquiry ended without a recommendation for enforcement action. The legal matters should not be treated as interchangeable. One remains active; the other, according to the report, closed without recommended action.
AppLovin is scheduled to report third-quarter results on November 4. Revenue, adjusted EBITDA margin and evidence of advertiser expansion will matter more than any price target. The company has already demonstrated high profitability and cash generation. It now has to show that those results can keep compounding when model upgrades do not arrive on a perfectly smooth schedule.