



 Be The Investor Research
The Case for Waiting on Moderna Is About Revenue, Not the Science
Moderna's oncology pipeline has been clinically de-risked, but current products still generate limited revenue relative to its valuation. The next earnings report must show that the commercial base is stabilizing.
The strongest reason to wait on Moderna shares is not doubt about the melanoma result. It is the gap between a promising oncology pipeline and the revenue produced by today's business.
Moderna generated $2.21 billion of revenue in the twelve months through June 2026, far below the $22.3 billion produced during the comparable pandemic-era period in 2022. The company remained loss-making, so investors cannot rely on a conventional earnings multiple. In mid-October, the stock traded at more than 40 times trailing sales after a several-hundred-percent rally.
The commercial base is beginning to recover. Revenue grew from a year earlier in each of the first two quarters of 2026, and management expected full-year growth of as much as 10%. Its newer COVID shot, mNEXSPIKE, captured about 24% of the U.S. retail COVID vaccine market in its first season, according to the company. Most annual vaccine revenue still arrives in the second half, which makes the third quarter especially important.
Products beyond COVID have not yet changed the income statement. The RSV vaccine mRESVIA generated only $8 million in 2025, although a European procurement contract covers up to 24 million doses. The combined flu and COVID vaccine mCOMBRIAX is approved in the European Union but is scheduled for a 2027 launch and is excluded from the 2026 forecast.
Intismeran could eventually reshape Moderna, but it remains investigational and profit economics are shared with Merck. The positive Phase 3 melanoma result improved the program's probability of approval; it did not create current product revenue.
The November 6 earnings report therefore has two jobs. It must show that seasonal vaccine sales are supporting management's annual outlook, and it must preserve enough cash to fund a broad late-stage pipeline. The company expects to end 2026 with $4.7 billion to $5.2 billion of cash and investments.
Waiting is a position on timing, not necessarily on scientific quality. Investors can believe the cancer program is valuable while requiring proof that the existing franchise can slow cash burn before the oncology opportunity becomes commercial.
Continue your MRK research
Related News
Moderna's Melanoma Data Must Justify a Rally Analysts Do Not
Moderna rallied ahead of full Phase 3 melanoma data due Oct. 24, even as Goldman Sachs kept a Neutral rating and set a target well below the share price.
Biotech Catalysts Put Moderna and Achieve Life Sciences in Focus
A dense clinical calendar gives investors several binary events, led by Moderna and Merck’s melanoma program and Achieve Life Sciences’ response to an FDA manufacturing rejection.

Mastercard’s Record Run Raises the Bar for October Earnings
Mastercard enters its October 29 report after strong second-quarter growth, leaving investors focused on cross-border volume, service revenue and whether margins can absorb continued investment.
FMC’s Guidance Collapse Signals a Channel Reset, Not a Normal Miss
FMC cut third-quarter revenue expectations to $65 million to $125 million and forecast a steep adjusted EBITDA loss as it discounts inventory and changes U.S. pricing.
RTX's Pratt Sales Rise 16% Even as New-Engine Mix Weighs on Growth
Pratt & Whitney's second-quarter sales rose 16%, but commercial original-equipment revenue fell as engine mix and repair demand redirected parts. RTX's next report should show whether service recovery and new deliveries can advance together.
Tesla, Meta and RTX Earnings Put AI Spending and Industrial Demand to the Test
A concentrated earnings calendar will test two market concerns at once: whether heavy AI spending is producing returns and whether industrial and consumer demand can withstand higher financing costs after a bruising week for technology shares.
American Airlines Faces a Narrower Margin for Error as Fuel Costs Surge
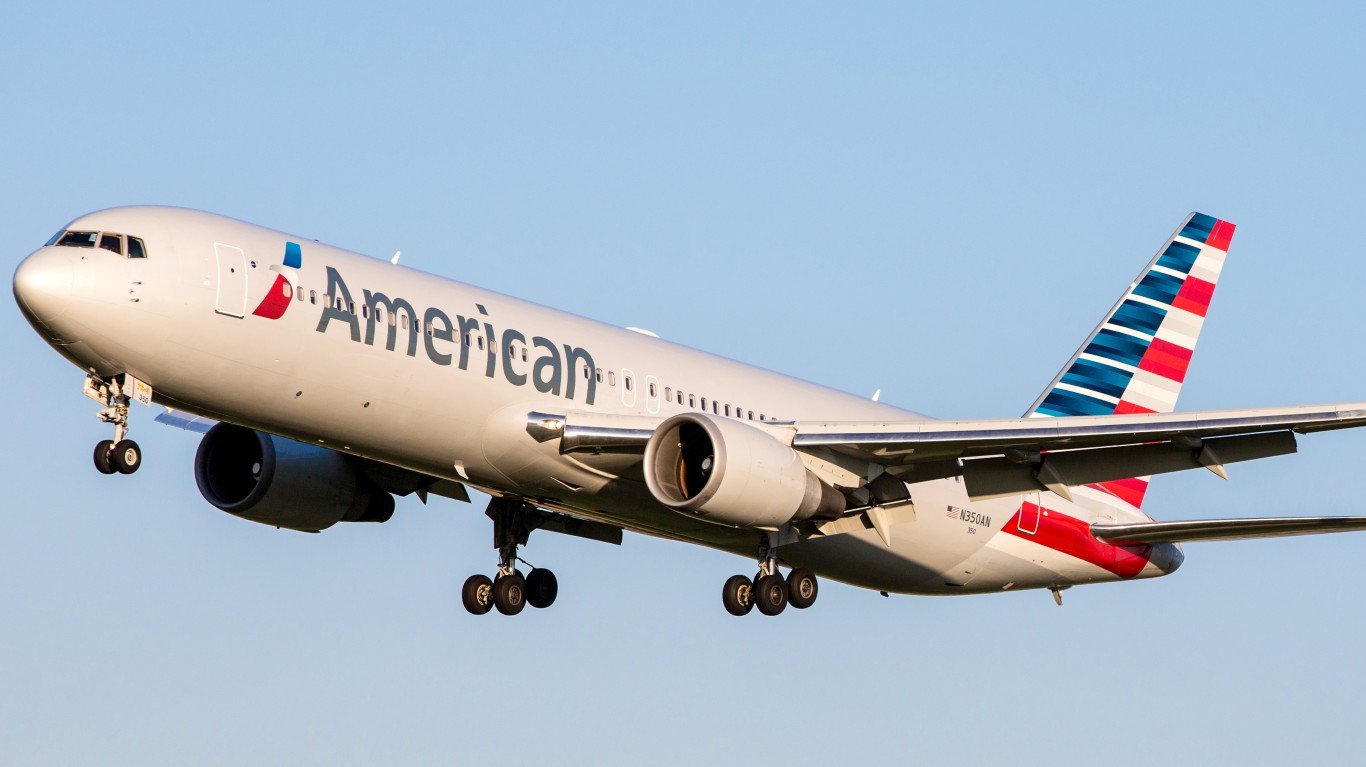
American Airlines carried more revenue in the second quarter, but fuel costs absorbed much of the benefit. Revenue rose 16.3% to $16.7 billion, while fuel expense jumped 83.3% to $4.9 billion. Operating margin fell to 2.7% from 7.9%, and net income declined 88.2% to $71 million.
Those figures explain the company’s unusually wide full-year outlook. American guided to adjusted earnings per share between a loss of $0.65 and a profit of $0.65. For the third quarter, it projected an adjusted loss of $0.70 to $0.10 per share. A range that crosses zero is not merely conservative presentation; it signals that small changes in fuel prices, fares or operations can determine whether the year is profitable.
There are offsets. Premium unit revenue increased 13.4%, corporate revenue rose 26%, and management said demand improved as the quarter progressed. Premium and business travelers generally provide better yields than price-sensitive leisure traffic, so continued mix improvement could help protect revenue even if industry capacity remains competitive.
The balance sheet leaves less flexibility than the demand figures alone might suggest. American reported $34.7 billion of debt and $11.3 billion of liquidity. That liquidity is meaningful, but higher fuel expense and thin operating margins make debt reduction harder. Investors should also distinguish accounting earnings from cash generation because aircraft spending, debt service and working-capital movements can widen the gap.
The next earnings report should clarify whether stronger premium demand is translating into better unit revenue and whether fuel pressure is easing. The central investment issue is operating leverage in reverse: when margins are thin, an expense shock can overwhelm healthy top-line growth. American does not need record fares to improve results, but it does need a more favorable combination of fuel prices, reliability and capacity discipline than it delivered in the second quarter.
That leaves little room for another cost surprise.
Spotify's Buyback and Rogan Renewal Put Q3 Margins in Focus
Spotify entered its third-quarter report with two capital-allocation decisions already in view: a new multiyear agreement for The Joe Rogan Experience and a $1.5 billion increase to its share-repurchase authorization.
The combination protects a major content franchise while returning capital to shareholders. It also raises the standard for margins because content commitments and buybacks compete for cash.
The operating base is stronger
Spotify ended the second quarter with 300 million premium subscribers and 777 million monthly active users. Premium subscribers increased 9% from a year earlier, monthly active users rose 12%, and gross margin reached a record 33.4%.
Revenue grew 14% to 4.78 billion euros. Premium revenue rose 15%, while advertising increased only 1%. That mix shows that subscriptions remain the main growth engine and that the advertising business has yet to provide an equally strong contribution.
The company guided to roughly 5 billion euros of third-quarter revenue. Investors should compare the result with subscriber additions, pricing and gross margin rather than focus on revenue alone.
Content retention and capital returns
Spotify did not disclose terms for the new Rogan agreement. Reports cited in the source said it may resemble the 2024 arrangement, which included an estimated $250 million earnout. Without confirmed terms, investors cannot calculate the return on the renewal. The benefit is retention of a highly engaged audience and continued ad-sales rights across platforms.
The board's additional $1.5 billion lifted the total repurchase authorization to about $2.22 billion. Authorization is not a commitment to spend the full amount, and management can slow or stop purchases. Spotify's net cash position gives it flexibility, but buybacks create value only when shares are repurchased below their long-term worth.
The margin test
The bullish valuation model in the source assumes an operating margin of 17.2% by the end of 2028. Spotify's trailing margin was reported near 14.6%, making further improvement possible but not automatic.
The third-quarter result needs to show that subscriber growth, pricing and cost discipline can absorb major content spending. A good report would combine healthy premium growth with stable or rising margins. If margins slip while advertising remains weak, the buyback may look better timed for shareholders than the operating investment behind it.
Morgan Stanley's $232 Billion Wealth Inflow Tests Its New Model
Morgan Stanley's wealth-management strategy delivered a record third quarter, but the quality of the quarter deserves a closer look. The division generated $9.1 billion of net revenue, up from $8.2 billion a year earlier, while net new assets reached $232 billion compared with $81 billion in the prior-year period.
More than half of the new assets were associated with initial public offerings. That does not make the inflow less real, but it means the quarter benefited from a channel that can fluctuate sharply with capital-market activity.
A larger pool of fee-producing assets
Morgan Stanley now oversees about $10.5 trillion across wealth and investment management. That asset base supports advisory, lending and other recurring revenue, reducing the firm's dependence on trading and investment banking.
The shift began after the 2008 financial crisis and continued through acquisitions and adviser expansion. It gives Morgan Stanley a different earnings mix from Goldman Sachs, which remains more exposed to whether deals close, and from Charles Schwab, whose results are particularly sensitive to client cash balances and interest rates.
The latest quarter also showed that the old engine still matters. Morgan Stanley reported $5.8 billion of equities trading revenue, up 41% from a year earlier. The firm is not abandoning trading. It is using wealth management to make the overall business less dependent on a single market cycle.
Where the moat can narrow
Asset-based fees rise when markets and client balances grow, but the same mechanism works in reverse during a selloff. A concentrated equity market adds another risk because falling prices among a small number of large technology holdings can reduce client assets quickly.
IPO-linked flows also complicate the comparison. Management said the active IPO calendar accelerates its funnel and deepens client relationships, yet those flows should not be extrapolated as a steady quarterly run rate. The better test is whether Morgan Stanley retains those assets and expands advice, lending and investment services around them.
The quarter validates the strategic direction without eliminating cyclicality. Wealth management has made Morgan Stanley more durable, but record flows arrived with favorable markets and unusually strong IPO activity. Investors should watch asset retention and the share of future inflows that comes from repeatable adviser-led channels rather than one-time liquidity events.
GE Aerospace and RTX Earnings Must Clear Guidance Already Priced Higher
GE Aerospace and RTX enter third-quarter earnings with a demanding setup: both beat estimates and raised guidance last quarter, while analyst expectations already assume at least part of another improvement. The companies report before the opening bell on October 20.
GE Aerospace delivered second-quarter adjusted earnings of $2.02 a share, up 22%, as revenue increased 21%. The company raised full-year adjusted EPS guidance to $7.65 to $7.85 and free cash flow guidance to $8.9 billion to $9.2 billion. Consensus cited in the source article expects $7.92, already above the top of that range.
RTX reported second-quarter adjusted EPS of $1.89 and 16% organic sales growth, with $2.9 billion of free cash flow. It raised full-year adjusted EPS guidance to $7.10 to $7.25 and free cash flow guidance to $8.50 billion to $8.75 billion. Consensus of $7.25 reaches the high end of the EPS range.
The operating questions differ. GE's commercial services revenue rose 26% last quarter, making engine utilization and shop-visit demand central to the outlook. Investors also need evidence that supply-chain investments can translate demand into deliveries without absorbing too much cash.
RTX combines commercial aerospace with defense. Pratt & Whitney's aftermarket grew 25%, while Raytheon benefited from Patriot, Standard Missile and AMRAAM demand. Powder-metal inspections on geared turbofan engines, tariffs and production capacity remain the constraints.
The valuation test is therefore about guidance quality rather than one quarterly beat. If either company merely repeats its existing range, investors may read that as caution because consensus already embeds stronger earnings. Conversely, higher guidance backed by cash generation would be more persuasive than a revenue beat driven by timing.
The two reports will provide a useful cross-check on aircraft service demand, engine output and weapons production. Those operational indicators can reveal whether record backlogs are becoming revenue or remaining constrained by parts and factory capacity.
Fifth Third’s Comerica Deal Starts to Show Operating Leverage
Fifth Third Bancorp’s acquisition of Comerica is beginning to show up in earnings power, even though merger costs kept reported per-share profit nearly flat from a year earlier.
Net income available to common shareholders rose 36% year over year to $828 million in the third quarter. Diluted earnings per share slipped 1% to $0.90, while adjusted earnings per share were $1.13 after excluding $0.23 of merger and other items.
The underlying improvement came from both scale and integration. Net interest income rose 3% from the second quarter to $2.28 billion and increased 49% from a year earlier, largely because Comerica expanded the balance sheet. Adjusted pre-provision net revenue rose 8% sequentially, and the bank reported 450 basis points of positive operating leverage, meaning revenue grew faster than adjusted expenses.
Fifth Third completed the Comerica systems conversion during the quarter and said the full $850 million annual expense-synergy run rate was locked in for the fourth quarter. Management also reported strong client and banker retention, a key risk after large bank combinations.
Funding and credit metrics remained stable. Average deposits increased 3% sequentially to $238.3 billion, while the loan-to-core-deposit ratio improved to 76% from 77%. Net charge-offs were 0.31% of average portfolio loans, compared with 0.30% in the prior quarter, and the provision for credit losses fell to $122 million from $129 million.
Capital moved in the right direction as well. The common equity tier 1 ratio increased to 10.02% from 9.93%. That gives the combined bank more flexibility as it absorbs integration costs and manages a larger credit book.
The main caveat is that reported results still contain sizable deal noise. Fifth Third recorded $215 million of pretax merger costs, plus technology impairments and interchange-litigation expenses. Investors now need evidence that the promised savings persist after conversion work fades, without deterioration in deposits or credit. The quarter supports that case, but the next test is converting locked-in cost synergies into durable per-share growth.
Latest comments