


 Be The Investor Research
USA Rare Earth's Rebound Puts Milestone Risk Back in Focus
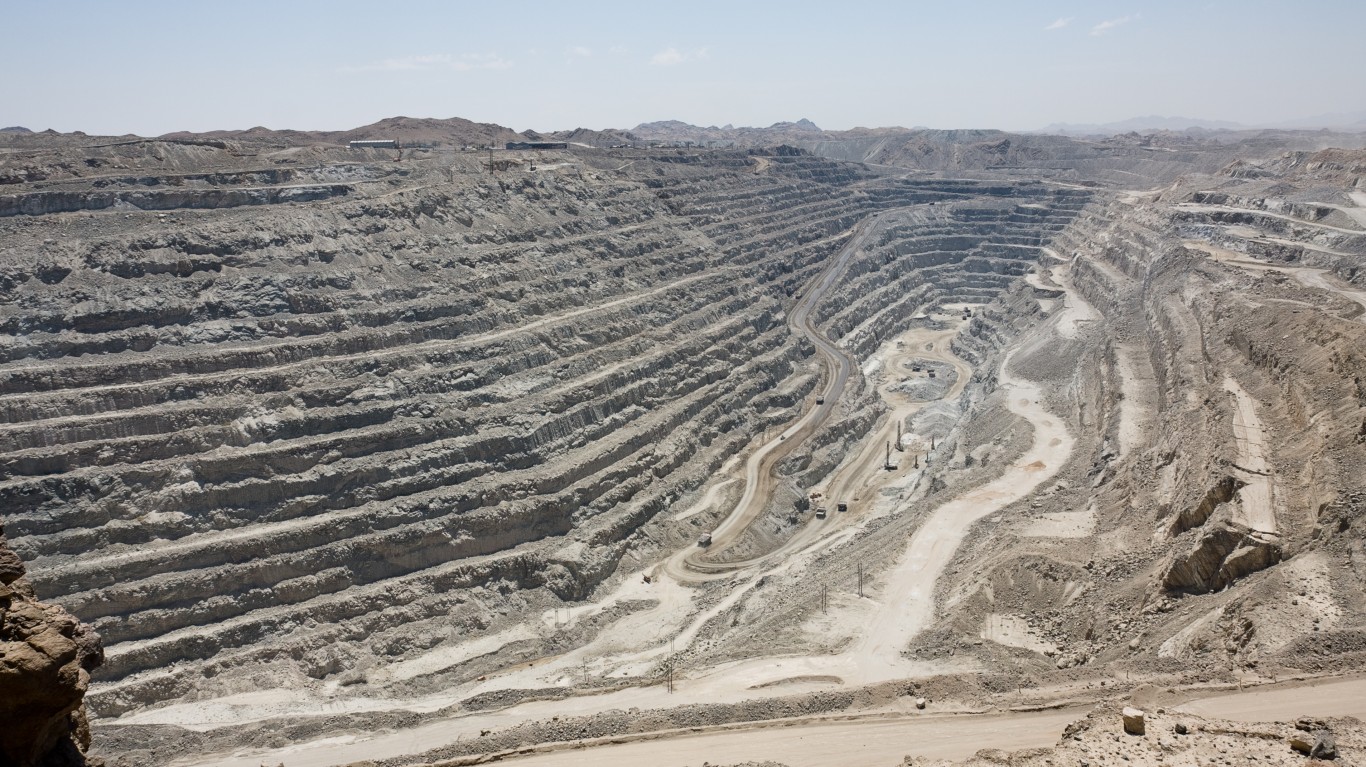
USA Rare Earth rebounded after a month-long selloff, but the company remains an execution story. Government-linked funding, a commissioned magnet line and Round Top planning support the thesis, while milestone conditions and operating losses remain central.
USA Rare Earth's share rebound follows a long selloff, but the daily price move says less about the business than the milestones behind its mine-to-magnet strategy. The company is trying to combine rare-earth mining, separation, metals and U.S. magnet production, a plan that requires substantial capital and coordinated execution.
The funding base is significant. USA Rare Earth said a $1.5 billion private placement closed in January 2026, and definitive agreements with the U.S. government brought total committed capital supporting the growth plan to about $3.5 billion. Some government funding remains subject to milestones rather than being immediately available cash.
Committed capital is not the same as unrestricted funding. Investors need to track which milestones have been achieved, how much cash has been received and what additional equity or debt may be required.
Operational progress is visible at Stillwater, Oklahoma. The company commissioned the first phase of its magnet-production line in March and said that enabled initial customer orders to begin in the second quarter. It also received a Texas grant of up to $14.2 million for the Round Top project and was selected for additional Department of Energy support subject to final negotiation.
Round Top remains earlier stage. Company filings called for a preliminary feasibility study followed by a definitive feasibility process. Until those studies establish economics, capital costs and timelines, the project's value depends heavily on assumptions about recovery rates, construction and rare-earth pricing.
USA Rare Earth has also disclosed that it expects operating losses until its facilities reach profitable commercial operations. That warning is important because strategic policy support does not remove ramp-up risk or guarantee customer qualification.
The rebound can be justified if investors believe the company is converting policy support into operating capacity. The next decisive evidence should come from delivered magnet revenue, government milestone receipts, updated project studies and a clear cash-use schedule. Without those, the stock will remain highly sensitive to sentiment around U.S. critical-minerals policy.
Continue your MP research
Related News

UK Clears Jackdaw Gas Production With a New Climate Trade-Off
The UK has allowed regulators to approve production from the Jackdaw gas field, pairing an expected 6% peak boost to domestic output with a £2 billion energy-transition fund and renewed emissions scrutiny.
Oil Stocks Hit New Highs, but Producers and Refiners Face Different Bets
Exxon, Chevron and Marathon Petroleum reached 52-week highs as Brent approached $110. The rally helps each company differently, and intraday records do not remove commodity-cycle or refining risks.
How Much Capital Can Support $7,600 a Month in Retirement?
Generating $91,200 a year may require about $2.61 million at a 3.5% yield, $1.52 million at 6% or $912,000 at 10%. The smaller portfolio carries much greater payout and principal risk.
Treasury Yields Near 5% Change the Dividend Decision for Retirees
Short-term Treasuries offer high contractual income with limited duration risk, while dividend stocks offer potential growth and better tax treatment. The better choice depends on spending horizon, reinvestment risk and tolerance for equity volatility.
Realty Income’s Dividend Streak Is Safe Only While AFFO Coverage Holds
Realty Income’s monthly dividend consumes roughly 73% to 74% of adjusted funds from operations, leaving a useful cushion. High Treasury yields, leverage and tenant credit quality limit how quickly the payout can grow.
Thermo Fisher’s Third-Quarter Growth Comes With Wider Margins
Thermo Fisher’s revenue rose 9% to $12.14 billion, while adjusted earnings increased 15% and operating margins expanded. Organic growth and new products show that the improvement was broader than acquisition effects.
3M’s Amazon Data Center Deal Offers Growth With a Dilution Trade-Off
3M shares rose 6% after the company combined stronger third-quarter earnings with an expanded data-center relationship with Amazon. The two developments support different parts of the investment case: the earnings report improved the near-term outlook, while the Amazon agreement created a conditional path to longer-term growth.
3M reported adjusted earnings of $2.50 per share, above the cited $2.39 consensus estimate. Revenue was about $6.6 billion, adjusted organic sales grew 3.3% and reported sales increased 1%. Those measures use different accounting bases, so the underlying growth rate should not be treated as the change in reported revenue.
The company raised its full-year adjusted earnings guidance to $9.10 to $9.15 per share. The outlook uses a new reporting basis, which means investors should compare it with historical guidance on a consistent basis before attributing the entire change to operating improvement.
The Amazon agreement is substantial but conditional. 3M issued an Amazon subsidiary a seven-year warrant to buy approximately 3.16 million shares at $164.89 each. About 85% of the warrant shares vest according to Amazon’s purchases of data-center products, with full vesting of that portion when cumulative payments reach $6 billion. The remaining 15% depends on separate milestones.
The $6 billion threshold is a vesting condition, not revenue that 3M has already earned or Amazon has unconditionally promised to spend.
For 3M, the structure aligns potential dilution with commercial activity. If Amazon buys enough optical-connectivity and related data-center products, 3M gains revenue while Amazon earns the right to acquire shares. If purchases fall short, much of the warrant does not vest. Investors still need to evaluate whether the product margins justify any additional share count.
The stock’s move outpaced Coherent, Corning, the industrial sector and the broader market, indicating that investors reacted to 3M-specific news rather than a general optics rally. That distinction supports the view that the earnings beat and Amazon arrangement were the main catalysts.
The next evidence will be purchase volume, data-center revenue and margin contribution. Until those figures appear, the agreement should be valued as an option on future business, not as a completed order.
eBay Plans a Second 2026 Workforce Cut as It Redirects Spending
eBay plans to eliminate about 1,000 jobs, or roughly 9% of its workforce, in its second major restructuring of 2026. The company confirmed the plan after an internal memo described the need to simplify operations and move resources toward higher-priority growth areas.
The new reduction follows a February cut of approximately 800 positions, or about 6% of staff. eBay ended 2025 with roughly 12,300 employees. Taken together, the two announced rounds represent a substantial change in the organization, although the final net headcount will depend on hiring and attrition.
Chief Executive Jamie Iannone told employees that the company’s strategy was working but required deliberate choices about where to invest. eBay said it would continue recruiting in selected growth areas while increasing spending on artificial intelligence. That combination matters: the plan is not simply a uniform cost reduction, but a reallocation from some teams to others.
The financial benefit depends on severance costs, hiring in growth areas and whether a smaller organization can execute without weakening the marketplace.
The cuts come after eBay completed its $1.4 billion cash acquisition of Depop from Etsy. Depop gives eBay a stronger position in secondhand fashion and access to younger customers, but integration adds another demand on management and technology resources. The workforce plan may help align the combined portfolio, yet the company has not provided a complete savings target or timeline in the reviewed materials.
The stock rose about 1% after the news, suggesting investors initially viewed the restructuring as supportive of margins. A positive share-price reaction does not show whether the cuts will improve long-term growth. Marketplaces depend on product development, trust and safety, seller support and customer service, all of which can suffer if cost reductions are poorly targeted.
Investors should look for three pieces of evidence: a disclosed restructuring charge, a measurable run-rate cost saving and stable or improving marketplace activity. AI spending should also be judged by outcomes such as better search, fraud detection and seller productivity.
The restructuring can improve efficiency, but it also raises the standard for execution. eBay now needs to show that fewer employees and more focused investment produce stronger cash flow without damaging the experience that keeps buyers and sellers on the platform.
Nuclear Stocks Face a Split Verdict Before Earnings
Wall Street’s latest nuclear-energy calls show that support for the sector does not translate into equal confidence in every stock. Analysts remained constructive on established power producers while cutting targets more sharply for developers and fuel companies whose valuations depend on future milestones.
Citi lowered its Oklo target to $33 from $57.50 and kept a Neutral rating. The new target still implied upside from the cited market price, but the reduction reflects a lower valuation for an advanced-reactor developer that has not yet reached commercial operation. Citi also cut NuScale Power’s target to $4 from $6.50 and maintained a Sell rating, implying downside in the original report.
Morgan Stanley raised its Constellation Energy target to $378 from $369 and kept an Overweight rating. The firm linked the outlook to utility fundamentals and the political debate around data-center power demand. Constellation owns operating nuclear plants, so its earnings are tied to actual generation, power prices and customer contracts rather than only future reactor deployment.
The analyst split is a reminder that nuclear demand can be bullish while individual equity risk remains very different.
Raymond James reduced its Vistra target to $176 from $182 but maintained a Strong Buy rating. The firm argued that concerns about ERCOT forward prices, regulation and slower data-center contracting were already reflected in the stock, while agreements with Meta and Amazon Web Services, a pending acquisition and PJM fundamentals offered support.
Centrus Energy received a sharper target cut. Roth Capital lowered its target to $115 from $188 and kept a Neutral rating, warning that third-quarter results could disappoint after the company acquired Westerman Holdings for $11 million. Centrus is exposed to uranium enrichment and fuel-cycle policy, creating a different risk profile from power producers.
The common sector catalyst is rising electricity demand from data centers and electrification. The differences are timing and financing. Operating generators can sell power today. Advanced-reactor developers must pass licensing, construction and funding milestones. Fuel suppliers depend on contract timing, government policy and capacity expansion.
Investors should avoid using a single nuclear thesis for all five stocks. The next earnings reports should be judged on company-specific evidence: contracted power prices for Constellation and Vistra, licensing and cash runway for Oklo and NuScale, and order visibility for Centrus.
Nokia’s AI and Cloud Orders Turn Network Growth Into a Measurable Business
Nokia’s third-quarter results gave investors concrete evidence that artificial intelligence demand is moving beyond chipmakers and into networking equipment. Net sales rose 10% from a year earlier to €5.15 billion, while comparable operating profit increased 35% to €605 million.
The strongest growth came from Network Infrastructure. Revenue in that division rose 15% on a constant-currency basis to €2.15 billion, with IP Networks up 43% and Optical Networks up 18%. These products carry data between servers and data centers, making them essential when AI workloads require larger and faster networks.
Nokia said revenue from AI and cloud customers increased 123%, while orders from those customers rose 118%. The company secured €1.5 billion of new AI and cloud orders during the quarter. That order figure is particularly useful because it shows demand beyond revenue already recognized.
The €1.5 billion of AI and cloud orders gives Nokia a measurable pipeline rather than only a long-term technology narrative.
Profitability improved, but not every indicator moved in the same direction. Comparable gross margin slipped 0.2 percentage points to 44.6%, while operating margin rose to 11.7%. The divergence suggests that volume growth and operating leverage helped offset some pressure at the gross-profit level.
Management maintained its 2026 comparable operating-profit outlook of €2.1 billion to €2.6 billion. It also expects the combined Optical and IP Networks businesses to grow between 25% and 30% in 2027. That target now has support from current orders, though investors still need to see how much of the backlog converts into revenue and cash.
Nokia is also expanding its work with Nvidia on AI-native radio access networks. The companies are combining Nokia software with Nvidia’s Aerial platform to improve signal processing, beamforming and network-resource allocation. Nokia said it completed an AI-RAN call in a live operator network with T-Mobile and Nvidia.
The investment case is becoming more specific: AI spending can benefit Nokia through data-center networking and telecom automation. The next evidence should come from backlog conversion, sustained margins and cash generation. If those measures improve together, the quarter could mark more than a temporary demand spike.
Latest comments