



Domino's Holds 23% Pizza Share: How Much Growth Runway Is Left?

Domino’s Pizza (DPZ) sees meaningful runway beyond its estimated 23% pizza-category share, supported by order growth, aggregator delivery and store development, although modest U.S. comparable sales and franchisee pressures have curtailed near-term expansion plans.
Domino’s Pizza, Inc. (DPZ) leads the global pizza industry, but management sees substantial long-term market-share potential. Its estimated 23% category share remains below the 40%-50% shares held by leading quick-service restaurant brands in some other categories, though that comparison does not imply Domino’s will reach those levels. The growth case centers on orders. Since the end of 2008, U.S. orders through Domino’s system have more than doubled, generating double-digit market-share gains, roughly $7 billion in incremental retail sales, more than 2,100 net new stores and an almost 240% increase in franchisee store-level EBITDA. Management views rising orders and disciplined pricing as the foundation for further gains. Third-party delivery could expand the addressable customer base. Domino’s believes it is already the No. 1 pizza brand on Uber and DoorDash, but has not reached its fair share of aggregator activity. The company continues to cite roughly 50% incrementality for aggregator orders, suggesting many transactions come from customers who might not otherwise have ordered directly. Unit development offers another growth route. Domino’s ended the second quarter with 22,531 stores globally, including 7,231 U.S. and 15,300 international locations. The system added 209 net stores during the quarter and 995 over the trailing four quarters. Risks include U.S. same-store sales growth of only 0.1% in the second quarter, as lower ticket offset stronger orders. Franchisee profitability pressure led Domino’s to reduce its 2026 U.S. store-growth outlook to approximately 175 units. Peers also highlight the value of customer acquisition and development. Starbucks Corporation (SBUX), through its Back to Starbucks strategy, reported third-quarter fiscal 2026 U.S. comparable-sales growth of 7.9%, with transactions up 4.2% and ticket up 3.6%. Rewards reached 35.8 million 90-day active U.S. members, while Refreshers produced double-digit U.S. revenue growth. Starbucks sees coffeehouse whitespace domestically and internationally. Yum! Brands, Inc. (YUM) reported Taco Bell second-quarter 2026 same-store sales growth of 7%, its ninth consecutive quarter outperforming the broader QSR industry. Digital mix reached 47%, up 5 percentage points year over year. KFC delivered 7% unit growth and sees a 20,000-unit opportunity across India, Southeast Asia, West Africa and Brazil.
Continue your DPZ research
Related News
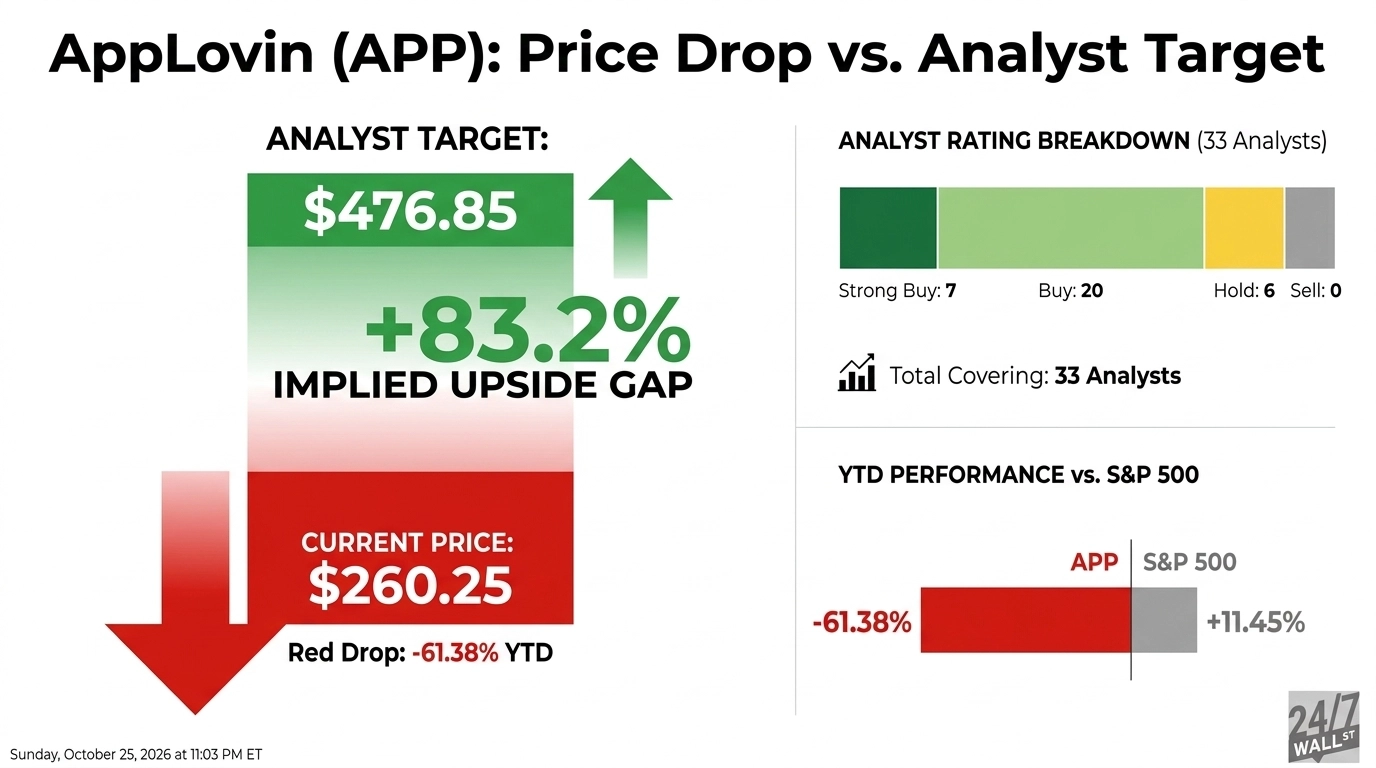
AppLovin's 61% Slide Turns Its Next Quarter Into a Model Test
AppLovin's second-quarter revenue and cash flow still grew rapidly, yet a small revenue miss and slower model improvements changed the market's confidence. The November 4 report now carries unusual weight.
Alibaba's Cloud Growth Cannot Yet Offset Its Commerce and Cash Costs
Alibaba's shares have fallen with Chinese internet stocks, but the operating picture is more complicated: cloud revenue is accelerating while commerce weakness, AI spending and a wider free-cash-flow outflow weigh on the case.
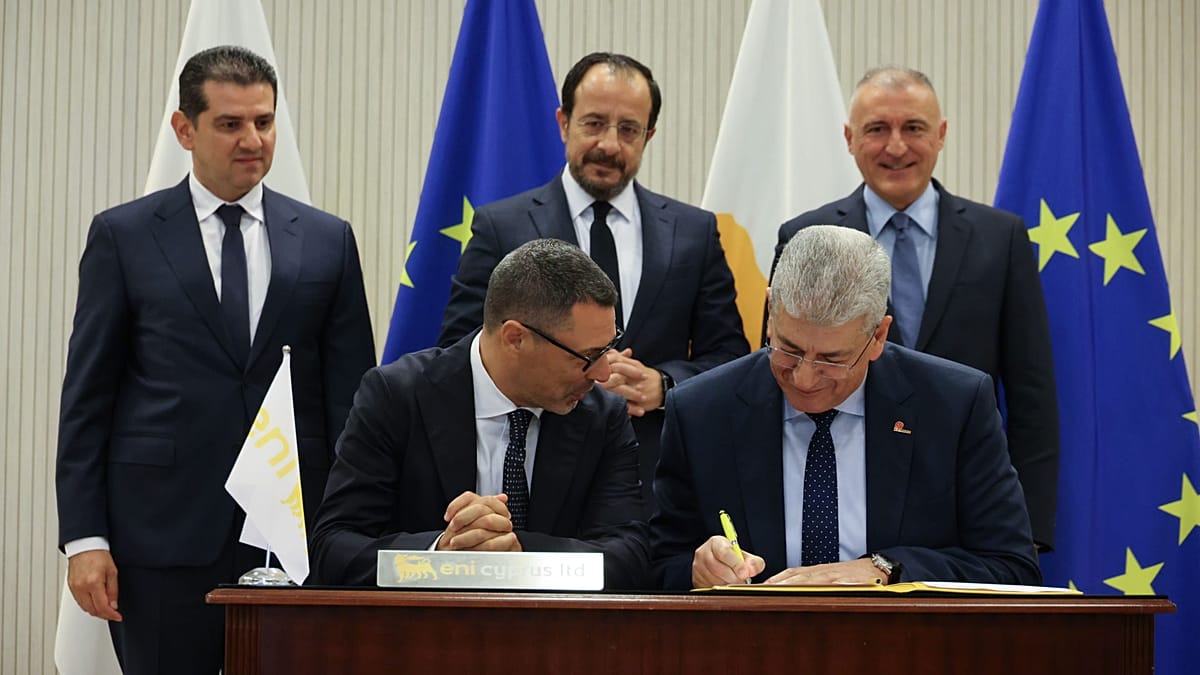
Cyprus' First Gas Project Turns a Discovery Into a 2028 Export Plan
Eni and TotalEnergies are moving the Cronos gas field into construction with contracts worth up to $1.8 billion, using Egypt's existing infrastructure to target first production in 2028.

Meta's $135 Billion AI Budget Shifts Attention to Amphenol
Meta's spending plan strengthens the revenue case for data-center suppliers such as Amphenol, but negative free cash flow and new financing plans show why investors are also questioning the cost of the buildout.
Affirm's Q1 Setup Turns on GMV Growth Above Guidance
Morgan Stanley expects Affirm's GMV growth to exceed management's outlook, but investor expectations may be higher still. Margins, funding costs and revenue less transaction costs will decide the result.
Amazon's AWS Forecast Raises the Bar Ahead of Q3 Earnings
Bank of America expects AWS growth to accelerate to 40%, but Amazon's October 29 report must also show that record AI infrastructure spending can produce durable margins and cash returns.
Roku's Home Screen Advantage Needs Measurable Ad Conversion
Roku is asking advertisers to treat the television home screen as the start of a measurable customer journey, not simply as a place to buy reach. The strategy fits the company's operating-system position, but the most important claims still come from Roku and its partners rather than independently audited campaign data.
Lauren Benedict, Roku's vice president of global ad sales and partnerships, told Beet.TV that Roku reaches 100 million households globally and meets viewers when they first switch on their televisions. She said users spend nearly 16 minutes searching for content and return to Roku on roughly 25 days each month, compared with about eight days for the next most-used app. Those figures explain why Roku believes menu, home-screen and in-content ads can work as a sequence rather than isolated impressions.
The commercial pitch is moving toward outcomes. Benedict cited Roku and Omnicom research in which a home-screen placement followed by sequential streaming messages produced nearly six times the purchase intent. A Roku case study said Toyota's multi-format campaign lifted ad recall by 8.1%, with 98% of campaign reach coming exclusively from sponsorship media. These are useful examples, but investors should treat them as company-reported evidence until methodology and control-group details are available.
Industry infrastructure is becoming more supportive. IAB Tech Lab introduced standardized signals for connected-TV formats such as pause, menu, overlay and squeeze-back ads. Common definitions can reduce manual work and make new inventory easier to buy programmatically, which may help Roku scale formats that appear before or between programs.
Roku's financial results show why this matters. Reuters reported that first-quarter 2026 platform revenue rose 28% to $1.13 billion, beating the estimate it cited, and Roku raised its full-year platform revenue forecast to $5 billion, or 21% growth. Devices revenue fell 16% to $118 million, reinforcing that advertising and other platform services, not hardware sales, are the larger economic opportunity.
The next proof point is not another household milestone. Roku needs to show that home-screen access, sequential formats and data partnerships increase advertiser spending and platform revenue without overwhelming viewers or relying on one-off case studies. Standardization makes the inventory easier to transact, but repeatable campaign performance will determine whether the operating-system advantage becomes durable cash flow.
Apparel Selloff Masks Three Different Turnaround Problems
A broad retail selloff pushed Lululemon and Under Armour down about 4% on October 23, while Nike fell roughly 2%. The similar share moves concealed three different operating problems, and investors should not treat the group as a single bet on consumer spending.
The macro backdrop was not uniformly weak. The U.S. Census Bureau estimated September retail and food-services sales at $745.0 billion, up 0.8% from August and 6.3% from a year earlier. The report was adjusted for seasonal and trading-day effects but not for price changes. With the SPDR S&P Retail ETF down about 2% that day and no fresh announcement from the three companies, the stock moves looked more like a repricing of discretionary risk than a response to new company results.
Lululemon has the clearest near-term demand problem. Second-quarter revenue fell 4% to $2.4 billion, Americas revenue declined 8%, and Americas comparable sales dropped 12%. Reported gross margin rose 200 basis points to 60.5%, but a $134.5 million tariff refund added 560 basis points. Operating margin still declined 190 basis points to 18.8%. Management guided third-quarter revenue to $2.29 billion to $2.32 billion, a 10% to 11% decline, and expects full-year revenue to fall 5% to 7%.
Under Armour's weakness is spread across channels and categories. Its first-quarter fiscal 2026 revenue declined 4% to $1.1 billion, with North America down 5%, wholesale down 5% and direct-to-consumer revenue down 3%. Footwear fell 14%, a sharper contraction than the 1% decline in apparel. The company reported $13 million of restructuring charges and held $911 million of cash, including $400 million raised in senior notes to help address $600 million of notes due in June 2026.
Nike is further along in parts of its turnaround, but the recovery is uneven. Fiscal first-quarter 2027 revenue fell 4% to $11.2 billion, while North America grew 2%. Performance categories grew at a high-single-digit rate, helped by running and global football, but Sportswear, Jordan and Greater China remained material drags. Nike ended the quarter with $8.4 billion in cash and short-term investments, giving it more financial room than the other two companies.
The October 23 selloff therefore did not prove that shoppers had suddenly stopped spending. It highlighted different tests: Lululemon must stabilize Americas comparable sales without relying on one-time tariff refunds, Under Armour must make restructuring produce durable demand and margin improvement, and Nike must turn strength in performance products into a broader brand recovery.
Exelon's 36 GW Load Pipeline Is Bigger Than Its Near-Term Certainty
Exelon enters its October 30 earnings report with a larger growth opportunity than its current capital plan can capture, but the utility still needs to show which data center requests are likely to become paying load.
The company's second-quarter presentation identified about 36 gigawatts of projected data center demand across its service territories. Exelon classified roughly 11 gigawatts as high-probability load: about 9 gigawatts at ComEd in advanced design or backed by transmission security agreements, plus about 2 gigawatts in the Mid-Atlantic, where roughly 40% had signed agreements supported by about $1 billion of collateral. Another 25 gigawatts remained in current or future study clusters. That distinction matters because an interconnection request is not the same as a contracted customer.
Exelon's existing plan is already large. Management affirmed a $41.7 billion capital program through 2029, expected to produce 7.9% rate-base growth, and said it sees another $12 billion to $17 billion of transmission opportunities beyond the plan. Most of that additional opportunity is expected in 2030 or later. The company also highlighted more than 11,000 circuit miles of transmission and several awarded or proposed projects, including a $1 billion-plus MISO project being developed with Invenergy.
Near-term earnings are steadier than the load pipeline. Exelon reported second-quarter adjusted operating earnings of $0.43 per share, up from $0.39 a year earlier, while GAAP earnings were $0.39 in both periods. It maintained 2026 adjusted operating earnings guidance of $2.81 to $2.91 per share and still expects annual adjusted earnings growth near the top of its 5% to 7% range through 2029. Management had completed about 86% of its 2026 debt issuance needs and priced about 37% of the $3.4 billion of equity expected through 2029.
The financing progress reduces immediate interest-rate risk, but it does not remove execution or regulatory risk. A proposed $15.3 billion ComEd grid plan awaits an Illinois order expected by December 15, while BGE's $156.1 million electric rate request is scheduled for a January 2027 decision. Storm costs, a July PECO employee strike and the timing of large-load commitments can all shift quarterly results without changing the longer-term transmission thesis.
The most useful October 30 update will not be whether Exelon repeats the headline 36-gigawatt figure. Investors need to know how much of the 25-gigawatt study pipeline has advanced, how much collateral protects customers from abandoned projects, and whether incremental transmission awards can move into the capital plan without weakening affordability or credit metrics.
Novartis Raises Profit Outlook, but Cash Flow Trails Earnings

Novartis raised its 2026 core operating-income outlook after a third quarter in which higher sales and a wider core margin outweighed a $1.94 billion impairment. The guidance increase is meaningful, but falling free cash flow and the remaining value assigned to the failed drug program keep the result from being a simple earnings beat.
Third-quarter sales were $14.5 billion, up 4% at constant currencies. Core operating income rose 10% at constant currencies to $6.0 billion, and the core margin expanded 2.0 percentage points to 41.6%. Core earnings per share reached $2.46, helped in part by a lower share count. The source article said that figure was about 9% above the Zacks consensus of $2.25.
Novartis now expects 2026 core operating income to be flat to up by a low-single-digit percentage at constant currencies. Its previous forecast called for a low-single-digit decline. Sales guidance remains for low-single-digit growth, so the higher profit forecast implies that management expects stronger profitability rather than faster revenue growth.
The operating support came from newer medicines that are replacing sales lost to generic competition. At constant currencies, Kisqali sales increased 37%, Kesimpta rose 22%, Scemblix gained 67% and Leqvio climbed 63%. That mix matters because Novartis needs these products to support both revenue growth and margins as older drugs face competition.
Reported results tell a much weaker story because they include the del-desiran charge. Reported operating income fell 61% at constant currencies to $1.8 billion. Novartis's interim report shows that the acquired research asset carried a value of $7.48 billion before the impairment and a recoverable value of $5.54 billion afterward. The $1.94 billion charge therefore removed about 26% of the asset's carrying value.
The impairment followed del-desiran's failure to meet the primary endpoint in the Phase 3 HARBOR trial. The remaining $5.54 billion is not automatically another loss, but it is a concentrated accounting risk if Novartis reduces its expectations for the program again. Investors should also keep the non-cash nature of the charge separate from the economic issue: no cash left the company this quarter, yet the lower recoverable value reflects weaker expected benefits from money already committed.
Cash generation is the main counterweight to the margin improvement. Third-quarter free cash flow fell 18% to $5.1 billion from $6.2 billion a year earlier. For the first nine months, free cash flow declined 12% to $14.0 billion from $15.9 billion. Over the same nine-month period, core operating income was $16.9 billion, down only 1% in U.S. dollars. That gap does not invalidate the raised outlook, but it shows that higher core profitability has not yet translated into comparable cash growth.
Valuation leaves limited room for disappointment. TIKR data in the source article put Novartis at 16.4 times forward earnings, above its five-year average of 14.3 times. The same data showed consensus earnings per share of $8.83 for 2026, $9.80 for 2027 and $10.69 for 2028. Those estimates require roughly double-digit annual earnings growth after a year in which management still expects only low-single-digit sales growth.
The quarter strengthens the case that Novartis can protect margins while its newer drugs scale. It does not erase the two risks visible in the same report: cash flow is trailing the core earnings story, and more than $5.5 billion of value remains attached to del-desiran after a failed pivotal study. The raised outlook is real progress, but future results must show that the improvement reaches cash as well as adjusted profit.
ARK's Archer and Joby Purchases Put Execution Ahead of Hype
ARK Invest's latest purchases of Archer Aviation and Joby Aviation are a visible vote of confidence in electric air taxis, but the size of the trades is less important than the operating milestones the two companies still need to deliver.
Stocktwits reported that ARK bought 1,161,604 Archer shares for about $4.5 million and 434,012 Joby shares for about $2 million. The purchases were spread across the ARK Autonomous Technology & Robotics ETF and the ARK Space Exploration & Innovation ETF. ARKQ received 781,854 Archer shares and 292,119 Joby shares, while ARKX added 379,750 Archer shares and 141,893 Joby shares.
Those transactions show how an active manager is positioning its funds. They do not establish that commercial demand, certification or unit economics have improved. ARKQ itself describes its strategy as actively managed, which means holdings can change as the portfolio team revises its views.
Archer has supplied a clearer operating narrative in Texas. The company announced plans for air-taxi networks in Austin, Dallas-Fort Worth and Houston, linking airports and other high-traffic destinations. Archer says its Midnight aircraft could reduce trips that take 60 to 90 minutes by car to flights lasting 10 to 20 minutes. That is a company goal, not evidence of a functioning commercial network today.
The company is also trying to broaden its aerospace exposure through agreements to acquire Boeing's Wisk, SkyGrid and Insitu businesses. Archer says Insitu generates more than $200 million in annual revenue, based on company estimates. The waiting period under U.S. antitrust law has expired, but the transaction still depends on other closing conditions and is expected to close by the end of 2026.
Joby has moved into real-world test operations through the Federal Aviation Administration's Electric Vertical Takeoff and Landing Integration Pilot Program. In October, it began a week of piloted flights over representative routes in Texas, including the Dallas-Fort Worth area. The program is designed to start with flights under FAA oversight and progress toward passenger operations. That progression is useful operational evidence, but it is not the same as full certification or scaled commercial service.
The market has already punished the gap between ambition and execution. Stocktwits reported that Archer and Joby shares were down 47% and 64%, respectively, in 2026 when the article was published. It also noted that Morgan Stanley had cut its Joby price target to $10 from $13 while keeping an Equal Weight rating.
ARK's roughly $6.5 million purchase may help sentiment at the margin, but it does not solve the central investor questions. Archer must turn network plans and acquisitions into funded operations, while Joby must move from supervised demonstration flights toward certified passenger service. Until those steps are visible, the trade is best read as a portfolio manager's conviction, not confirmation that the air-taxi business model has arrived.
Latest comments