


 Be The Investor Research
CoreWeave’s Upgrade Rests on Scale, but Debt Still Defines the Risk
Goldman Sachs upgraded CoreWeave as its backlog and operating scale expanded. The bullish case depends on turning contracted demand into cash faster than financing and depreciation consume it.
CoreWeave rose after Goldman Sachs upgraded the AI cloud provider to Buy, helping lift other infrastructure names such as Nebius and Oracle. The call reflects a more constructive view of operating leverage as CoreWeave adds capacity and converts a large backlog into revenue.
The company’s scale is difficult to dismiss. CoreWeave reported approximately $104 billion of revenue backlog at June 30, excluding more than $25 billion of net new customer commitments added early in the third quarter. It also said operating cash flow had turned positive and continued to expand contracted power, which is the scarce input behind GPU capacity.
Scale does not remove the financing question. CoreWeave raised more than $10 billion of unsecured debt and convertible bonds in the second quarter. Backlog includes obligations and estimated future revenue that remain subject to service availability and delivery conditions. That makes construction schedules, power availability and customer concentration central to the value of the headline number.
The bullish case is that a larger installed base spreads fixed costs, improves utilization and gives CoreWeave more bargaining power. If operating cash flow expands before debt service and capital spending peak, the company can reduce the market’s concern that growth is being financed faster than it creates value. The bearish case is that hardware depreciation, interest expense or delayed sites keep free cash flow negative despite strong demand.
The upgrade is a meaningful sentiment catalyst, but the next earnings report must do the heavier work. Investors should compare revenue growth with cash capital expenditure, interest expense and incremental margins. They should also examine how much backlog converts on schedule. CoreWeave can justify a higher valuation if it proves that scale improves cash economics. If it merely produces more revenue alongside more leverage, the rally will remain vulnerable to every shift in AI spending expectations.
Continue your NBIS research
Related News

Gartner Sees a $4.9 Trillion Revenue Gap Behind the Neocloud Shakeout
Gartner estimates AI data-center owners need $8.5 trillion of revenue through 2030, against no more than $3.6 trillion available. The gap points to consolidation, not the disappearance of AI demand.
Gartner’s AI Infrastructure Math Puts Neocloud Survival Under Pressure
Gartner’s warning is less about an imminent collapse than a financing mismatch: AI infrastructure owners may need far more revenue than the market can generate before today’s accelerators lose value.

JPM Coin Goes Live on Ethereum for Institutional Dollar Transfers
JPMorgan made its dollar deposit token available to institutional clients on Ethereum after launching on Base. The move broadens bank-backed settlement but keeps access inside JPMorgan's permissioned client network.
Ethereum's Faster Proofs Still Need a Worst-Case Cost Limit
Vitalik Buterin says Ethereum's zero-knowledge provers need a hard maximum cost per unit of gas. Fast results on sampled blocks do not yet guarantee predictable resources for every valid workload.
Apple Schedules October 28 Event as Touchscreen Mac Reports Build
Apple invited media to an October 28 event, but reports of a touchscreen MacBook Pro remain unconfirmed. Investors should separate the scheduled launch from product specifications and pricing rumors.

Meta's Reported Claude Cut Is Small Beside Its $130 Billion AI Budget
Meta reportedly halved internal Claude Code seats as it shifts developers toward in-house tools. The possible savings are modest beside its official 2026 capital-spending range, making infrastructure returns the more important earnings question.
A Second $45 Billion Nscale-Anthropic Deal Would Raise the Financing Stakes

Nscale and Anthropic are reportedly discussing a second compute agreement worth as much as $45 billion, only weeks after announcing a deal of similar size. Bloomberg's sources, cited by TechCrunch, cautioned that negotiations were continuing and the terms could change. Neither company had confirmed the new agreement when the report appeared.
That status is the first thing investors should keep straight. A discussion is not a signed contract, and a headline value can represent years of capacity commitments rather than cash paid upfront. Without disclosed pricing, deployment dates, minimum-use clauses or financing terms, the reported $45 billion cannot be treated as near-term revenue for Nscale or an immediate expense for Anthropic.
The report still matters because Nscale is building at extraordinary scale. In an October operational update, the private cloud provider said its long-term partnerships represented more than $103 billion of total contract value. It has separately disclosed projects involving tens of thousands of Nvidia systems and substantial power commitments in Europe and the United States. These contracts can support growth, but they also require land, power, equipment and financing well before all customer payments arrive.
The financing question is especially relevant because both companies have been pursuing public listings. TechCrunch reported that Nscale faced investor resistance to a proposed $30 billion valuation. A second giant Anthropic commitment could improve revenue visibility, yet it could also increase concentration and execution risk if facilities arrive late, power is constrained or the customer's demand changes.
The next useful evidence is a signed announcement with GPU count, start dates, contract duration and funding responsibilities. Until those terms appear, the story is best read as evidence of aggressive capacity negotiations, not proof that a new $45 billion asset or liability already exists.
Amazon’s TorchNeuron Lowers the Barrier to Trainium, but CUDA Still Sets the Benchmark

Amazon Web Services is attacking one of Nvidia’s strongest advantages: developer friction. TorchNeuron is designed to let PyTorch users run workloads on AWS Trainium accelerators with a small configuration change rather than rewriting an application for a new hardware stack.
That matters because software compatibility can be more important than chip specifications. AWS says roughly 85% of AI applications use PyTorch. If those teams can test Trainium without rebuilding code, more of them may compare AWS silicon with Nvidia GPUs on real workloads.
AWS cites Deepgram as evidence of the possible economics. In an AWS case study, the voice AI company reported processing between 11% and 70% more audio per dollar, depending on the benchmark and configuration. Those results are useful but not universal. Performance can change with model architecture, batch size, latency targets and engineering effort, and a vendor case study is not a substitute for an independent workload test.
The strategic goal is to reduce dependence on Nvidia’s CUDA ecosystem while keeping customers inside AWS. That creates a second form of lock-in: moving away from CUDA may lower GPU dependence, but services optimized around Trainium can become tied to AWS tools and infrastructure. Buyers should evaluate both directions of portability.
For Amazon, easier migration can improve utilization of its custom chips and support cloud margins if Trainium delivers more computing per dollar at an attractive cost to AWS. For Nvidia, the threat is gradual rather than immediate because CUDA’s libraries, talent base and installed applications remain extensive.
Developers should compare end-to-end cost, latency, accuracy and maintenance burden on the same production-like workload. TorchNeuron is important because it makes that comparison cheaper. The investment significance depends on whether repeated customer tests confirm the advertised gains and whether AWS can turn trials into sustained Trainium usage.
That evidence remains essential.
OpenAI Spy Case Tests Insider Controls, but the Allegations Remain Unproven
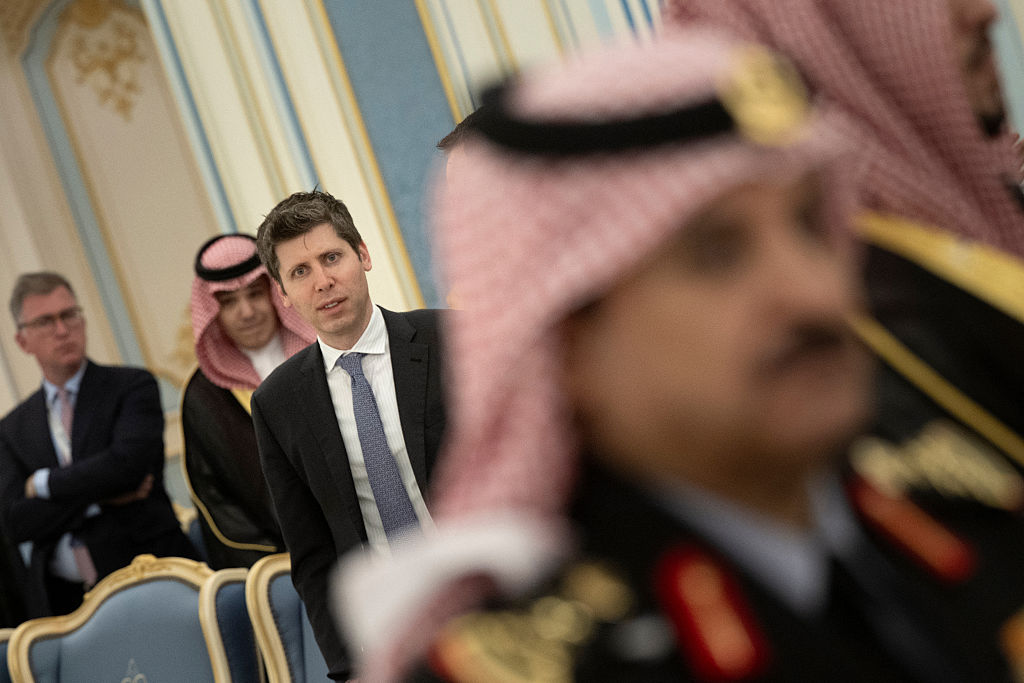
A federal criminal case involving OpenAI has become a vivid example of the risks created by trusted access. Prosecutors accuse a Saudi national who worked as a contractor at OpenAI’s San Francisco office of installing two concealed audio-recording devices and later trying to leave the United States.
The procedural status matters. A judge denied the defendant’s release pending trial, but that decision is not a conviction. The government’s complaint describes alleged conduct, including a secret meeting, a one-way ticket to Saudi Arabia, WhatsApp communications with members of the Saudi royal family and a folder labeled “Saudi Gov Docs.” Prosecutors have not publicly established what the folder contained or proved that the alleged recordings were delivered to a foreign government.
For companies building sensitive AI systems, the incident shows why network security alone is insufficient. Contractors, temporary workers and employees can have physical access to conversations, prototypes and internal decisions that never appear in a source-code repository. Security programs therefore need access limits, device controls, visitor logging and rapid offboarding in addition to software monitoring.
The case also demonstrates the danger of overstating an early prosecution narrative. The government must prove the charges, and the defense can challenge the evidence and its interpretation. A suspicious travel plan or file name may support an investigation without establishing espionage. Reader-facing analysis should preserve that distinction.
OpenAI has not disclosed a financial loss tied to the alleged devices. The immediate investment significance is therefore operational and reputational, not a quantified earnings event. The lasting question is whether the company strengthens physical and contractor security without disrupting the collaboration required for research. Until trial evidence is tested, the responsible conclusion is narrow: the allegations expose a plausible insider-control weakness, but they do not establish who received information or what harm occurred.
Future filings should clarify whether any proprietary research, customer data or strategic discussions were exposed.
Microsoft Treats AI Agents as Insiders With Dynamic Privileges

Microsoft is reframing autonomous AI agents as a new class of insider. Its security work introduces Guardian Agents and Project Perception, tools designed to monitor agents, separate their identities and adjust permissions as context changes.
The premise is practical. An agent that can read email, query databases and execute workflows may accumulate more effective access than the employee who launched it. A malicious prompt, compromised tool or mistaken plan can then turn legitimate permissions into an unintended action. The risk exists even when no employee is acting maliciously.
Microsoft’s proposed answer is an independent security boundary. Agents should have their own identities rather than borrowing a user’s credentials, and permissions should be limited to the current task. Higher-risk actions can require human approval. Monitoring also needs to follow sequences of activity because an individual API call may look harmless even when several calls together create a data leak or unauthorized change.
That design creates operational trade-offs. Frequent approval prompts can slow work and encourage users to approve mechanically. Rules that are too permissive undermine the control, while rules that are too strict reduce the value of automation. Effective deployment therefore requires risk-based thresholds, clear ownership and logs that investigators can reconstruct.
For Microsoft, the initiative supports its broader security and enterprise AI strategy, but it is not yet a quantified revenue catalyst. The more important signal is architectural: identity, least privilege and continuous monitoring must extend from humans and applications to agents. Companies adopting autonomous systems should test them with production-like permissions before broad deployment and preserve an immediate way to revoke access. Treating agents as insiders is not alarmism; it is a recognition that useful autonomy and security exposure grow together.
The strongest control is preventive: an agent should never receive standing authority merely because a user could grant it.
Why Embedded AI Evaluations Can Mislead Buyers

AI companies are embedding evaluation tools directly into development platforms, promising customers a faster way to test models and agents. The convenience is real: teams can run a prompt set, record outputs and compare versions without building a separate testing system.
The risk is that an evaluation harness is not neutral plumbing. Prompt formatting, retry logic, tool permissions, scoring rules and even timeout settings can change a model’s measured performance. Research on benchmark infrastructure has shown that implementation choices can affect results, which means two vendors can report different scores for the same underlying system without either number being obviously false.
Agent evaluations are especially difficult. An agent may choose among tools, maintain memory and take several steps before answering. A successful final result can hide an unsafe intermediate action, while a failed task may reflect a broken tool rather than poor reasoning. Cost and latency also matter because a system that solves more tasks by making many more calls may not be economical in production.
Hugging Face’s Evaluation Cards proposal addresses part of the problem by asking test creators to document datasets, metrics, limitations and implementation details. NIST has likewise emphasized transparent, reproducible automated benchmark practices. Those principles are more important than any single leaderboard position.
Buyers should ask whether they can export test cases and logs, reproduce results outside the vendor’s platform and inspect failures at each step. They should also run domain-specific tests that reflect actual permissions and business consequences. Embedded evaluators are valuable for iteration, but they should not become self-issued certificates of quality. The more a commercial claim depends on a score, the more independent reproduction and documented methodology matter.
A sound evaluation program should also define failure severity before testing begins. A wrong answer in a drafting tool is not equivalent to an unauthorized financial transaction or disclosure of customer data.
Latest comments