



Talen's 2027 Outlook Gives Vistra Investors a Fresh PJM Benchmark
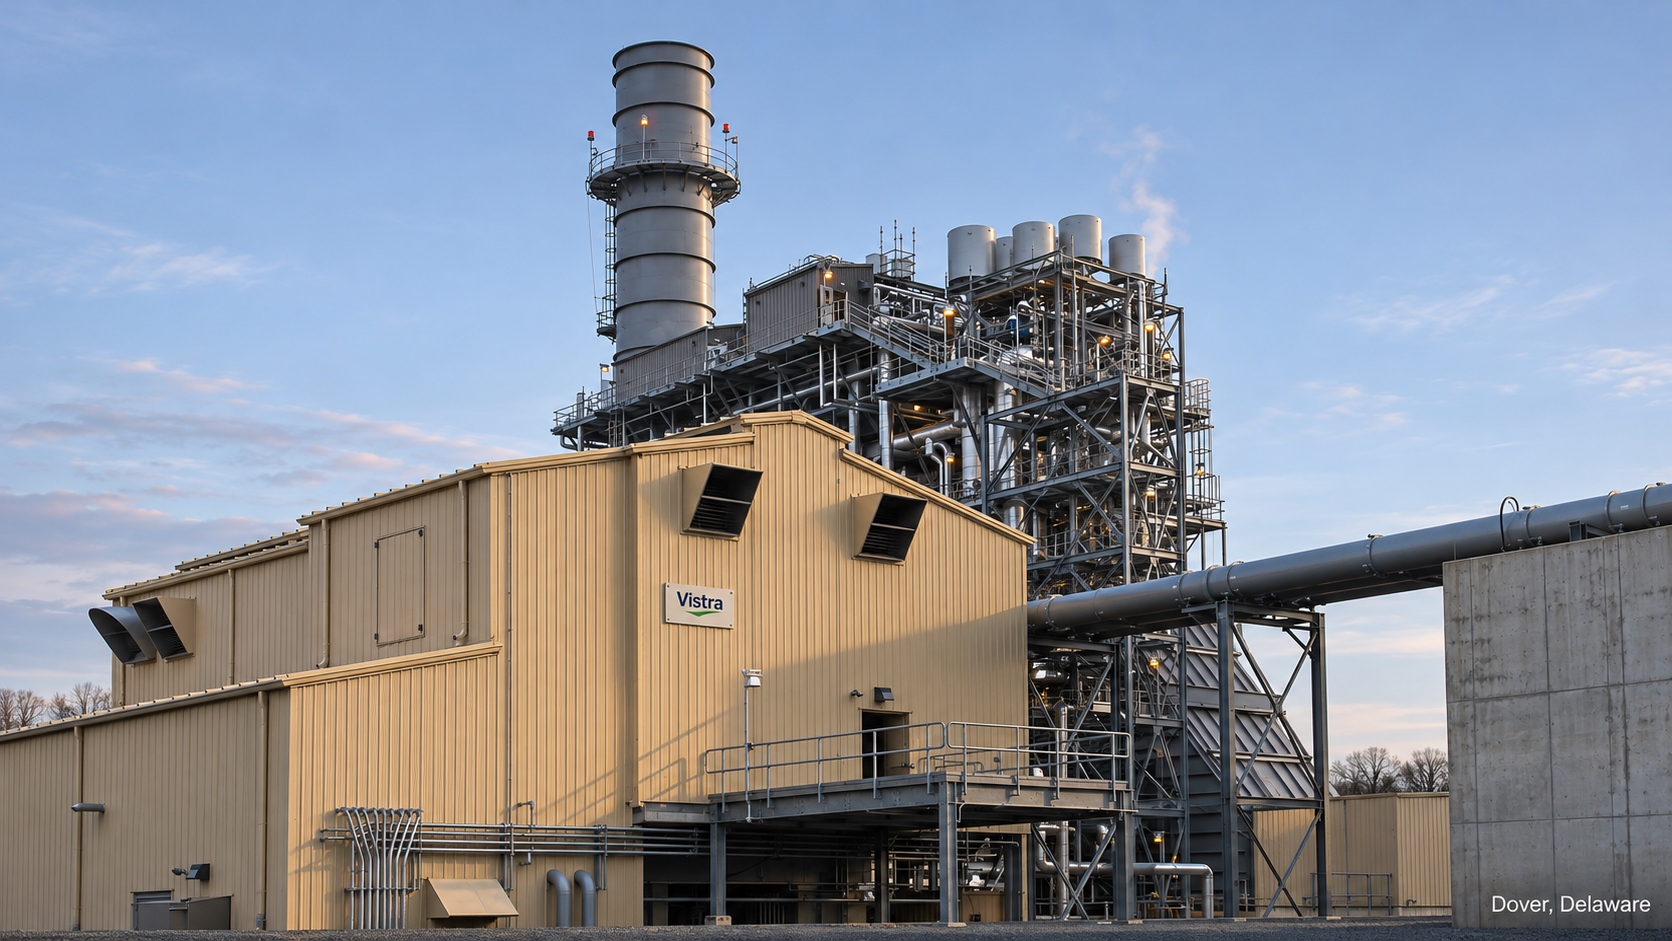
Talen expects adjusted EBITDA to rise about 26% at the midpoint in 2027, backed by PJM conditions and acquired plants. Vistra's newly expanded PJM fleet makes the read-through relevant, though Texas remains a separate risk.
Talen Energy's new 2027 guidance gives investors a useful, though imperfect, benchmark for Vistra's expanding PJM generation fleet. Talen expects adjusted EBITDA of $2.50 billion to $2.85 billion next year, about 26% growth at the midpoint from its narrowed 2026 range.
Talen attributed the outlook to strong PJM fundamentals and a full year of contributions from recently acquired assets. Its third-quarter adjusted EBITDA reached $669 million, up from $363 million a year earlier, while adjusted free cash flow rose to $433 million from $223 million. These are non-GAAP measures, so the acquisition contribution, hedges and financing costs need to be considered alongside reported net income of $138 million.
Vistra has just increased its own exposure to the same power market. On October 30, it completed the acquisition of Cogentrix Energy, adding 5,496 megawatts across 10 gas plants. Five of those facilities, totaling 3,163 megawatts, are in PJM. The acquired portfolio also includes plants in New England and Texas.
The read-through is that stronger capacity and power economics in PJM can support both companies. It is not a direct earnings forecast for Vistra. Their asset mixes, hedges, fuel positions, financing and acquisition timing differ, and Vistra also has substantial Texas exposure.
Vistra said when it announced the Cogentrix deal that the assets were expected to add mid-single-digit ongoing-operations adjusted free cash flow before growth per share in 2027 and high-single-digit accretion on average through 2029. The company paid a mix of cash and stock and assumed debt, making integration and leverage part of the return calculation.
Talen's guidance also includes a $1.5 billion accelerated repurchase and a larger $3 billion repurchase authorization through 2028. That capital return can amplify per-share growth, so investors should not attribute the entire projected increase to wholesale power prices.
For Vistra, the next earnings update should clarify how Cogentrix changes 2027 guidance and whether PJM strength offsets weaker conditions elsewhere. Talen has raised the benchmark, but Vistra still has to show the cash flow, integration and regional balance in its own numbers.
Continue your TLN research
Image references: · Delaware Public Media (Factual visual reference; rights retained by owner.) · Lotus Infrastructure (Factual ownership reference.)