



VYMI, IDV and SCHY Offer Foreign Income With Very Different Costs
International dividend ETFs delivered strong recent returns, but VYMI, IDV and SCHY differ sharply on fees, concentration and yield. Investors should separate a favorable one-year window from a durable allocation case.
International dividend stocks outperformed many U.S. income strategies over the one-year window used in the source, but the result should not be mistaken for a permanent advantage. VYMI, IDV and SCHY all own foreign dividend payers, yet their fees and portfolio construction differ enough to produce distinct outcomes.
Vanguard International High Dividend Yield ETF, or VYMI, is the broadest low-cost option in the group. Vanguard lists a 0.07% expense ratio. The source placed its trailing yield near 3.7% and its return around 24% from October 9, 2025 through October 12, 2026. Broad country and sector exposure can reduce single-market risk, though currency moves still affect U.S. investors.
iShares International Select Dividend ETF, or IDV, offered the highest cited yield at about 5.8% and returned roughly 22% in the same window. Its 0.50% expense ratio is materially higher. A high yield can reflect attractive cash distributions, but it may also signal slower growth, concentration in financials or utilities, or depressed share prices. The fee consumes a larger portion of the income advantage every year.
Schwab International Dividend Equity ETF, or SCHY, carried a 0.08% expense ratio and a 30-day SEC yield of about 3.8% in late September. Its source-window return was about 18%. Schwab's quality and sustainability screens can produce a more selective portfolio than a simple high-yield index.
The one-year results benefited from the chosen start and end dates. Currency gains, regional valuation changes and sector leadership can reverse. Foreign dividends may also face withholding taxes, and distributions are often less even across quarters than those from U.S. companies.
For a core allocation, VYMI offers breadth at a very low fee. IDV fits an investor who values current yield enough to accept higher cost and concentration. SCHY offers a low-cost quality screen with a shorter track record. The durable reason to own any of them is diversification across countries and business cycles, not a belief that the latest year's outperformance will repeat.
Continue your IDV research
Related News
Binance's SOXL Perpetual Fell 5.9% Without Breaking Its 3% Price Band
Binance's SOXL-linked perpetual fell 5.9% from its hourly open even though sampled mark-to-index gaps stayed below 3%. The episode shows why a price band does not cap trading losses.

GLDM Drew More New Money Than GLD as Fees Took Center Stage
State Street's lower-cost GLDM attracted substantially more new money than GLD in the reported period. The choice turns on holding costs, trading liquidity and taxes, not a different exposure to gold.
IBIT's $165 Million Outflow Looks Large, but Context Matters
BlackRock's bitcoin trust drove most of a $228.4 million weekly ETF outflow. Against $104.3 billion in sector assets, the move was small and concentrated in one session.
XRP ETF Outflow Broke a 13-Week Streak, but It Was Only 0.13% of Assets
U.S. spot XRP ETFs posted a $1.84 million weekly outflow after 13 weeks of inflows. Relative to $1.47 billion of assets, the reversal was small and does not establish a durable trend.
Trump Media and Rumble Fell Faster Than the Market as Merger Risk Loomed
Trump Media dropped 6% and Rumble 8% during a broader selloff, highlighting their high volatility. For DJT, the pending TAE merger adds execution, dilution and fusion-development risk.

JPM Coin Goes Live on Ethereum for Institutional Dollar Transfers
JPMorgan made its dollar deposit token available to institutional clients on Ethereum after launching on Base. The move broadens bank-backed settlement but keeps access inside JPMorgan's permissioned client network.
Ethereum's Faster Proofs Still Need a Worst-Case Cost Limit
Ethereum's zero-knowledge proof systems are becoming fast enough to prove ordinary blocks in near real time, but Vitalik Buterin says speed is no longer the only test. He has called for a hard upper bound on prover cost relative to the amount of gas in a block.
Gas is intended to meter execution work and keep blocks within a resource budget. Proof generation can impose a different workload. A block that is inexpensive for a conventional execution client may contain operations that are unusually expensive for a prover, so a speed result on typical blocks does not establish a worst-case guarantee.
ZKsync reported that one modern GPU proved 99% of a sample of 7,200 Ethereum blocks in under 10 seconds each. That is an important engineering milestone. It still measures the selected historical blocks, not every workload Ethereum rules permit an adversary to assemble.
EIP-7904 reaches a similarly narrow conclusion from the other direction. Its current analysis recommends no change to compute gas costs at a targeted native-execution throughput, but the document explicitly says it does not specifically address zero-knowledge proof generation.
A credible bound would need stated hardware, security settings, implementations and a maximum proving deadline. Without it, independent operators may have to provision for uncertain peaks or risk falling behind. Ethereum's next proof milestone is therefore not another average-speed record. It is a reproducible demonstration that the hardest valid blocks remain within a predictable resource envelope.
Aave's Proposed USAT Gateway Adds Permission Risk to the Return Trip
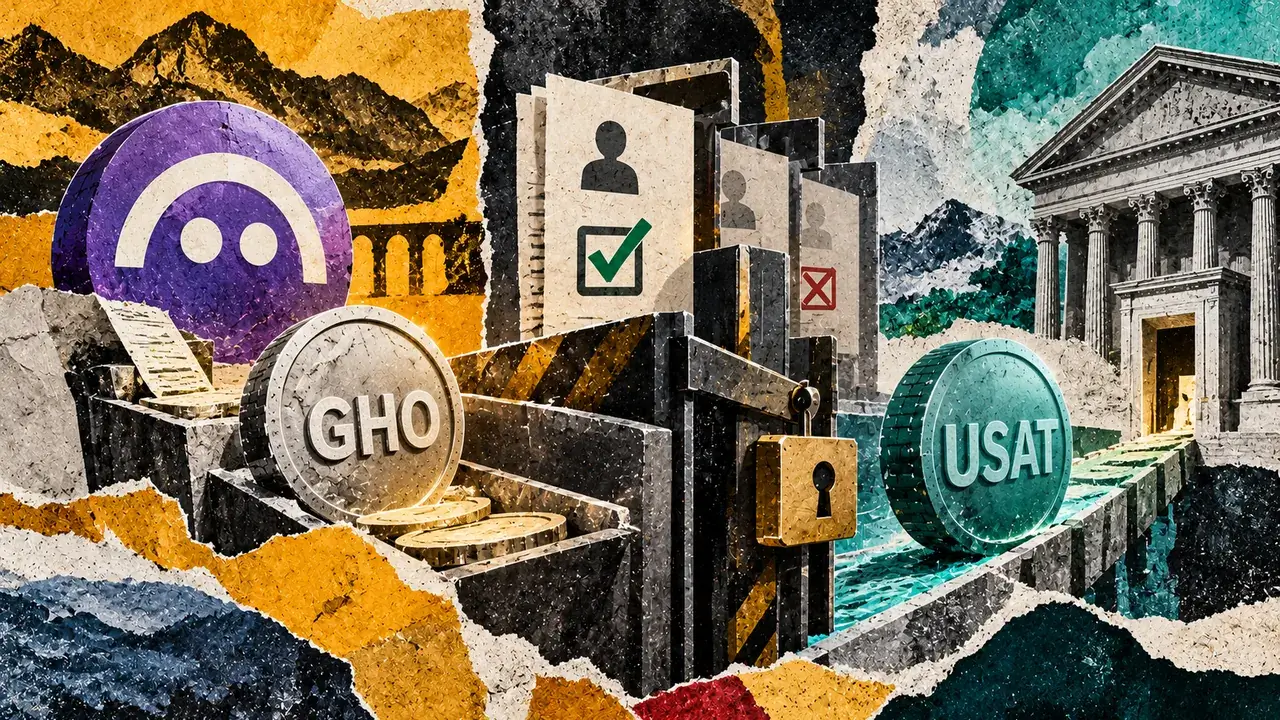
TokenLogic has proposed a permissioned GHO Stability Module on Avalanche that would let approved counterparties exchange waUSAT for GHO. The design could add institutional stablecoin liquidity to Aave, but it creates an important asymmetry: receiving and transferring GHO would not guarantee the ability to reverse the original swap.
Approval would be checked in both directions. If access were revoked after a counterparty deposited waUSAT and received GHO, the participant could still transfer GHO but could not use the module to recover waUSAT. The proposal says that restriction should be reflected in commercial agreements.
Even a successful reverse swap would return a receipt token rather than dollars. The holder would still need to withdraw USAT from Aave, subject to available liquidity and reserve conditions, and then meet Anchorage Digital Bank's requirements for issuer redemption. Each step has its own permission and operational risk.
The proposal separates 65 million GHO of reserve funding, a 25 million GHO module draw limit and a 20 million waUSAT exposure cap. Some contract addresses and pricing details remain unspecified, and the forum post still requires governance approval and an implementation proposal.
The plan may deepen GHO liquidity, but investors should treat it as a proposal rather than an operating product. The decisive questions are whether governance approves the module, whether final contracts preserve the described limits, and how counterparties are protected if access is revoked after entry.
CFTC Challenges CME's Standing in U.S. Perpetual-Futures Fight

The Commodity Futures Trading Commission has asked a federal court to reject CME Group's challenge to the agency's policy on perpetual futures, arguing that the exchange has not shown a concrete injury. The dispute concerns a CFTC framework that treats certain bitcoin perpetual contracts as futures that regulated exchanges may list.
CME says the policy changes the competitive and regulatory landscape. The agency's response focuses first on standing, a threshold legal question about whether CME is harmed enough to sue. If the court accepts that argument, it could dismiss the case without deciding whether the CFTC's interpretation of the Commodity Exchange Act is correct.
The competitive stakes are real even though the current fight is procedural. Perpetual futures have no fixed expiration date and are widely used on offshore crypto venues. Allowing them on U.S.-regulated exchanges could attract volume from conventional futures and give newer markets a product associated with crypto-native trading.
A dismissal would not automatically guarantee broad adoption. Exchanges would still need product approvals, surveillance, margin rules and sufficient liquidity. A ruling for CME could slow the framework or force the agency to provide a fuller legal justification.
For CME investors, the immediate effect is limited because the company can seek to list comparable products. The longer-term issue is whether the policy lowers barriers for rivals and changes the economics of U.S. crypto derivatives. The next meaningful event is the court's ruling on standing and dismissal, not the rhetoric in either side's filing.
Bitcoin Funds Cut Net Shorts, but the Data Shows Less Risk, Not a Bull Turn
Leveraged funds reduced their net short position in CME bitcoin futures to the equivalent of 30,611 bitcoin as of October 13, down from 35,903 a week earlier. The 5,292-bitcoin change occurred while the underlying asset fell, a combination consistent with some bearish traders taking profits or reducing exposure.
The details weaken a simple bullish interpretation. Outright short positions fell by 6,437 bitcoin, but outright longs also declined by 1,145. Leveraged funds still held more than twice as much outright short exposure as long exposure. The market became less bearish at the margin without turning net bullish.
Spread positions rose by 2,719 bitcoin per leg to about 8,434, an increase of nearly 48%. Those trades often pair long and short contracts with different maturities, seeking changes in the futures curve rather than a directional price move. Their growth lifted gross exposure even as outright bets and combined open interest contracted.
CFTC positioning is also delayed. The October 13 snapshot does not include bitcoin's subsequent fall below $80,000 and rebound toward $82,000. It cannot establish whether funds continued covering shorts or rebuilt them after inflation data and higher bond yields pressured risk assets.
The next report, covering positions through October 20, should be read alongside open interest and the split between outright and spread trades. Fewer net shorts can support price if positions are closed aggressively, but this week's data mainly shows traders reducing directional risk in a volatile market.
Latest comments