


 Be The Investor Research
Tether's Mining Kit Gives AI More Control, and Raises a Permission Question
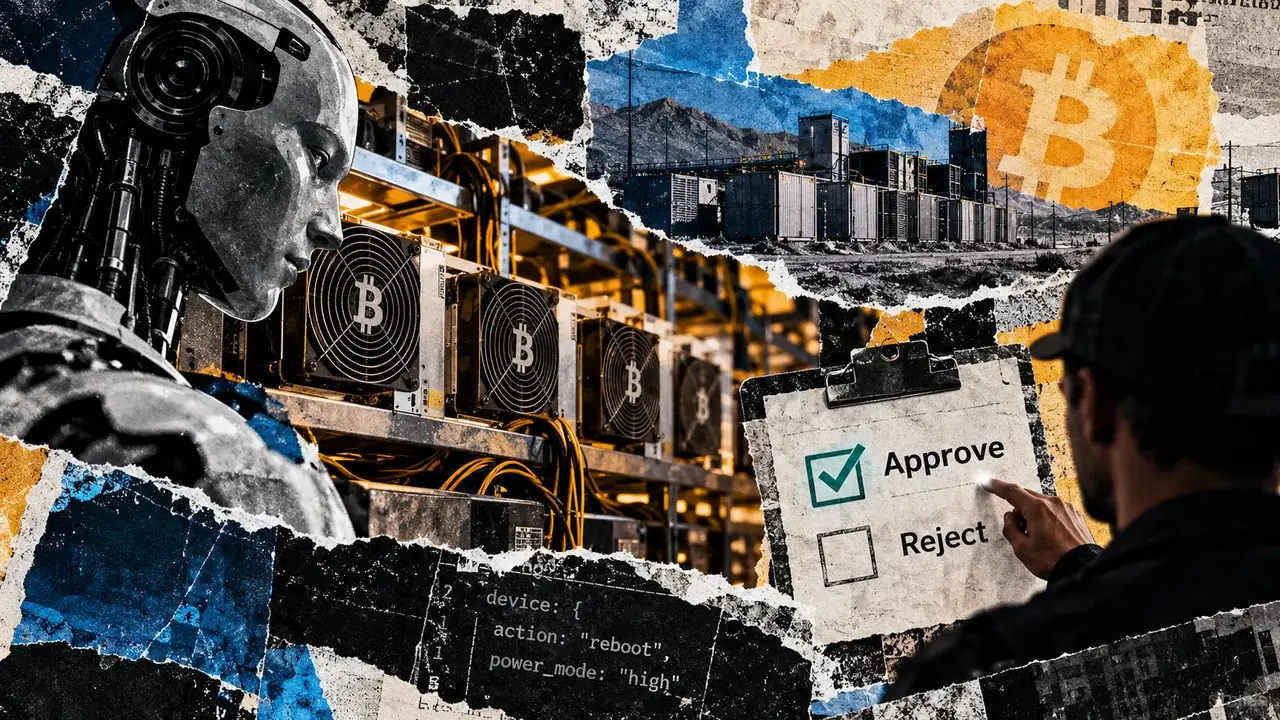
Tether says 15 mining companies and suppliers support its open Mining Development Kit. The automation promise depends on who may issue commands and where human approval remains mandatory.
Tether says 15 Bitcoin mining companies, equipment makers and pools have committed to integrate with its open-source Mining Development Kit, or MDK. The project aims to give software and AI agents a common way to monitor and operate mining equipment from different manufacturers.
The participant list includes Bitdeer, Bitmain, Canaan, Foundry Digital, Luxor, MicroBT, OCEAN and Block's Proto. Their involvement could reduce the need for mining operators to build a separate integration for every machine, pool or control system.
That interoperability is useful because a large mining site may contain several generations of hardware and multiple vendors. A common control layer could help operators compare performance, respond to overheating or power constraints, and automate repetitive tasks.
The same capability creates a security boundary that investors should not overlook. An AI agent that can read temperatures and hash rates is different from one that can reboot machines, change power modes or write configuration settings. Tether's version 0.11 reference agent pauses device-writing actions for human approval, but each deployment still has to define who the approver is and how that authority is authenticated.
The source review also found that caller authorization changed as the software developed. The tagged 0.11 Worker RPC interface did not enforce a caller-key check in the same way as newer code, while the newer main branch added admitted caller keys unless an allow-all setting is used. That difference shows why operators should review the exact version they deploy rather than rely on a general product description.
Model location matters too. A locally hosted AI system can keep operational data inside the mining site, while a hosted model may send prompts or telemetry to an outside provider. Operators need to decide which data may leave the facility and whether an external service should ever participate in write actions.
Tether targets a stable 1.0 release by the end of 2026, and the current code remains open for testing. The 15 commitments are therefore evidence of ecosystem interest, not proof that every integration is production-ready.
MDK could lower integration costs and make mining fleets easier to manage. Its success will depend just as much on permission design, audit logs and fail-safe controls as on AI capability. Automation becomes valuable only when the system can distinguish a useful command from an unauthorized or unsafe one.
Continue your BTC research
Related News
Franklin's Bitcoin DRIP ETFs Turn Stock Dividends Into Crypto
Franklin Templeton's new FBEQ and FIBT ETFs begin with 5% bitcoin exposure and redirect stock dividends into bitcoin. Low headline fees mask a structure that adds crypto volatility, derivative risk and potential tracking differences.
Super League Vote Clears Metaplanet Deal, but Dilution Comes First
Super League shareholders approved Metaplanet's 2,100-Bitcoin investment, but closing conditions, overwhelming control, 381 million warrants and future preferred financing define the risk for existing owners.
Nvidia and TSMC Show the Same AI Boom Through Different Risks
Nvidia's fiscal second-quarter revenue doubled, while TSMC's latest quarter delivered 41% growth and a fast 2-nanometer ramp. The results confirm strong AI demand but expose different constraints in products, customers and manufacturing.
Apple Offers iPhone Duo Replacements as Inner Screens Crack
Apple says a small number of iPhone Duo units have inner-display problems and directs affected buyers to AppleCare for replacements. The immediate risk is customer disruption, while the defect's cause, scale and financial cost remain unknown.
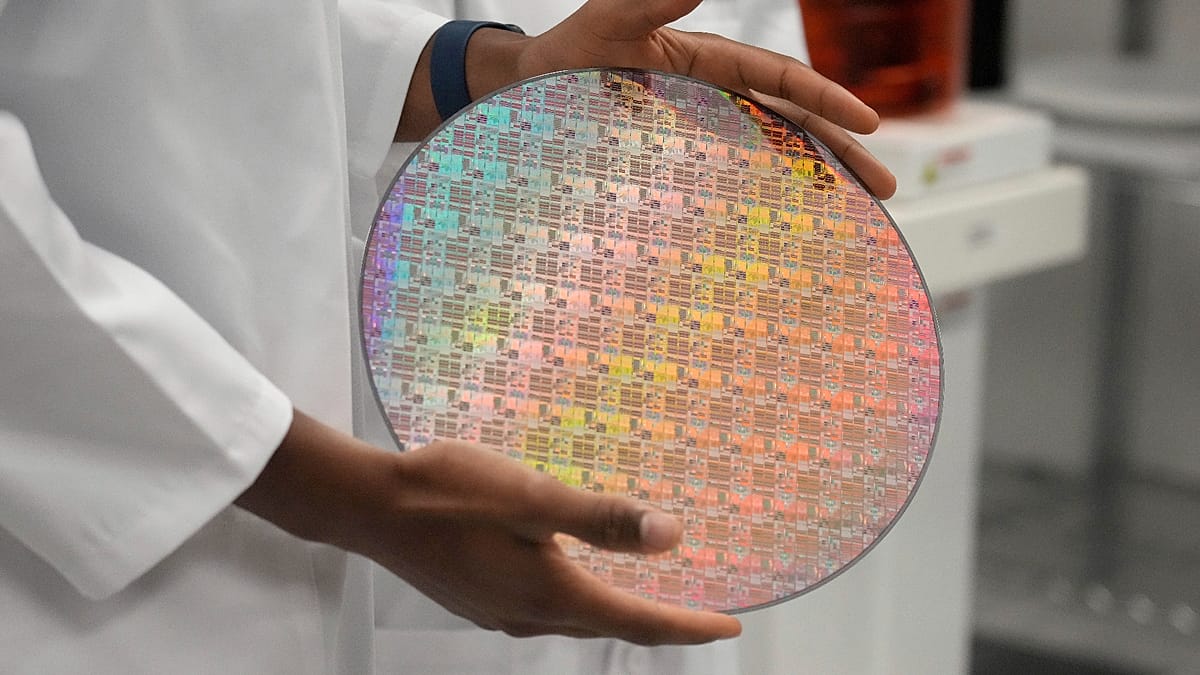
Applied Materials Doubles Down on Besi as Hybrid Bonding Demand Rises
Applied Materials plans to lift its Besi stake from 9% to about 20%, subject to U.S. antitrust review. The minority investment deepens a packaging partnership just as Besi's hybrid-bonding orders are accelerating.
CoreWeave and Nvidia Show Two Very Different Costs of AI Demand
CoreWeave and Nvidia are riding the same AI infrastructure boom, but CoreWeave's debt and construction cash burn contrast sharply with Nvidia's margins and cash generation. Backlog alone does not close that gap.
Nvidia's $3 Billion Meta Investment Deepens a Powerful Customer Tie
Nvidia is putting $3 billion into Meta's equity offering while the companies expand their work on Meta's Muse artificial-intelligence models. The investment is more than a financial placement: Meta also plans to deploy additional Nvidia Vera Rubin systems, Vera CPUs, Spectrum-X Ethernet networking and BlueField-4 technology across its data centers.
The transaction needs precise framing. Nvidia said it will invest $3 billion, but its release described the investment as proposed and subject to closing conditions. Meta launched concurrent offerings of Class A common stock and depositary shares representing mandatory convertible preferred stock. Meta later priced $25 billion of Class A shares at $625 each and 250 million depositary shares at $50 each, for a combined $37.5 billion before any over-allotment options.
On those announced amounts, Nvidia's commitment equals 12% of the $25 billion common-stock offering and 8% of the combined offerings. Those percentages are BTI calculations. Meta expects about $24.9 billion of net proceeds before expenses from the common-stock transaction, but the structure uses forward sale agreements that Meta expects to settle on or before November 19, 2027. Investors should not treat the entire amount as immediate cash already received.
The industrial logic is straightforward. Nvidia gets a closer relationship with one of the world's largest buyers of AI infrastructure, while Meta gets capital and engineering support for Muse. The companies said they will work on training and inference efficiency, total cost of ownership and agent security. For Nvidia, the relationship could reinforce demand across compute, networking and data-processing products rather than only GPUs.
The financial relationship also deserves scrutiny. Nvidia generated about $21.3 billion of free cash flow in its fiscal second quarter, calculated from $24.1 billion of operating cash flow less property and equipment purchases. The $3 billion commitment is therefore meaningful but manageable, equal to about 14% of that quarter's free cash flow. Nvidia also ended the quarter with $56.6 billion of cash, cash equivalents and marketable debt securities.
The harder question is whether supplier investments are helping finance demand for the supplier's own products. That does not make the demand artificial, but it can blur the line between an independent customer order and an ecosystem supported by Nvidia capital. Meta's share issuance also dilutes existing holders when the forward contracts settle, while the preferred securities add a 6.5% dividend obligation.
The clearest investor test is execution. If Muse adoption and Meta's infrastructure deployment generate durable workloads, Nvidia's $3 billion investment can strengthen a major customer relationship and support sales across several product lines. If the spending does not produce adequate returns, Nvidia will have used shareholder capital to deepen exposure to a customer's high-cost buildout. The partnership is strategically important, but the economics still depend on Meta converting new compute into useful, revenue-producing services.
Roblox's Safety Reset Raises the Cost of Its Bookings Test

Roblox's third-quarter report will arrive while the company is asking investors to accept two costs at once: weaker near-term monetization and a more expensive safety regime. The central question is whether those changes protect the platform without making the bookings slowdown harder to reverse.
The second quarter showed why the distinction matters. Daily active users rose 10% to 123 million and revenue increased 36% to about $1.5 billion, yet bookings grew only 8%. Roblox defines bookings as sales activity before the deferred-revenue accounting that spreads most virtual-currency purchases over the estimated life of a paying user. That makes bookings a more immediate measure of spending than reported revenue.
Management guided third-quarter bookings to $1.576 billion to $1.653 billion, a decline of 14% to 18% from a year earlier. It expects revenue to rise 4% to 10% because prior bookings continue to flow through reported results. Adjusted EBITDA guidance ranges from roughly break-even to $41 million, and the company stopped providing a full-year outlook in favor of quarterly guidance.
Some of the pressure comes from product choices. Roblox changed its recommendation system to favor games with stronger retention even when they monetize less per hour. The company also introduced mandatory age checks for chat and rolled out Roblox Kids and Roblox Select, which place younger users into age-based accounts with tighter content and communication settings. In its June-quarter filing, Roblox said these safety changes have affected and may continue to affect engagement, retention, revenue and bookings.
Those measures address a legal risk that is already showing up in the accounts. Roblox accrued $91 million in the first half of 2026 for settlements and settlement discussions with several states over youth-related consumer protection and digital safety matters. The filing said that amount covered cash payments but excluded some future commitments, such as public-service campaigns, law-enforcement liaison staffing and possible costs of platform changes.
The litigation remains unresolved. Reuters reported in September that a Los Angeles County lawsuit alleging that Roblox failed to protect children from exploitation could proceed after a judge rejected the company's attempt to dismiss it. Reuters also reported that Roblox and Discord faced more than 180 related lawsuits. These are allegations, not findings of liability, and Roblox disputes claims that it failed to protect users. The number of cases nevertheless makes the risk more than a hypothetical line in a disclosure.
Roblox has financial room to respond. At June 30, it held $6.1 billion in cash, cash equivalents and investments, while second-quarter operating cash flow was $318 million and free cash flow was $294 million. But safety spending is also rising. The company said infrastructure and trust-and-safety expense increased 54% to $236 million in the quarter, partly because of safety-related marketing and AI investment.
The October 29 report therefore has to answer more than whether bookings landed within guidance. Investors need to see whether payer growth and spending per user are stabilizing, how the new age-based controls affect engagement, and whether management can fund safety improvements without erasing operating leverage. A rebound in bookings would be encouraging. A rebound achieved while the company keeps strengthening safeguards would be far more durable.
Roblox's 17% Rally Faces a Bookings Test on Oct. 29

Roblox shares have rallied 17% in a month even as the company heads into its October 29 report with guidance for a sharp decline in third-quarter bookings. That contrast makes the coming result less a referendum on user growth than a test of whether a new viral hit can turn engagement into spending.
Bookings are the key measure because Roblox records most purchases of virtual currency as deferred revenue and recognizes the related revenue over the estimated life of a paying user, which was 27 months at the end of June. Reported revenue can therefore keep rising after current spending slows. In the second quarter, revenue increased 36% to about $1.5 billion, but bookings grew only 8% and landed at the low end of management's guidance. Daily active users rose 10% to 123 million.
Roblox blamed weaker monetization partly on users moving away from highly profitable 2025 viral games and partly on changes to its recommendation system. The company deliberately gave more visibility to games that kept players engaged longer, even when those games generated less spending per hour. Management said it expects retention to outweigh the near-term monetization cost over time, but its third-quarter forecast assumes the pressure continues.
For the third quarter, Roblox guided bookings to $1.576 billion to $1.653 billion, down 14% to 18% from a year earlier. It also moved to quarterly-only guidance, so the fourth-quarter outlook will matter almost as much as the reported number.
The wild card is Steal an Egg, which broke out after management issued that forecast. An Aream & Co. industry report cited in the original analysis estimated that the game reached 6 billion visits and 14.2 million concurrent players at its peak. Those figures were not independently available in the underlying report, so they should be treated as source-attributed estimates rather than company data. The investment question is not simply whether the game attracts players, but whether those players spend at rates comparable with Roblox's earlier hits.
Wall Street's recent target changes show how divided that question has become. Jefferies cut Roblox to Underperform with a $38 target in late September, while JPMorgan and UBS later raised their targets to $53, DA Davidson to $50, Wedbush to $55 and Roth Capital to $60. Most of those firms kept neutral ratings. With the shares around $53 in the source analysis, the rally had already moved the stock above several newly raised targets.
Valuation offers some support, but not a free pass. The source put Roblox at 5.3 times forward sales, below its five-year average of 7.8 times but roughly 50% above the 3.5 times multiple reached after the July report. That means investors are paying more for a business whose near-term bookings are still expected to fall.
The cleanest evidence on October 29 will come from three places: bookings relative to the $1.653 billion top of guidance, management's explanation of Steal an Egg's contribution, and the fourth-quarter bookings outlook. A strong user count without better spending would confirm that engagement and monetization are still moving in different directions. A result near the top of guidance, followed by a visibly narrower decline, would show that the viral hit is becoming an economic one.
Broadcom's AI Growth Deepens Its Customer and Margin Concentration
Broadcom's growth is increasingly tied to AI chips and a small group of large customers, even though its software business still provides a substantial second engine. The risk is not that Broadcom has become a one-product company. It is that faster-growing, lower-margin semiconductor revenue now carries more of the company's results.
Broadcom reported fiscal third-quarter revenue of $29.59 billion, up 86% from a year earlier. Semiconductor solutions produced $20.84 billion, or 70% of total revenue, and grew 127%. Infrastructure software contributed $8.75 billion, or 30% of revenue, and grew 29%.
Within the chip segment, AI semiconductor revenue reached $16.7 billion. That was up 221% from a year earlier and 54% from the prior quarter. BTI calculates that AI chips represented about 56.4% of company revenue and 80.1% of semiconductor revenue. Management guided to $21.7 billion of AI semiconductor revenue in the fourth quarter against about $34.8 billion of total revenue, which would lift the AI share to roughly 62.4% if both forecasts are met.
Three kinds of concentration
The first concentration is the business mix. Semiconductor solutions rose to 70% of revenue from 57% a year earlier, while software's share fell to 30% from 43%. Software is still meaningful, and VMware Cloud Foundation helped that segment grow 29%, so Broadcom is not solely an AI-chip company.
The second concentration is among end customers. Broadcom's filing says its top five end customers, through all channels, accounted for about 55% of third-quarter revenue, up from about 40% a year earlier. A delayed deployment, smaller order or product change at one large customer can therefore move quarterly results sharply.
The third concentration is in distribution. Direct sales to one semiconductor distributor accounted for 50% of quarterly revenue, compared with 32% a year earlier. That does not mean one end customer bought half of Broadcom's output. A distributor can serve multiple underlying customers, so channel concentration and end-customer concentration must remain separate.
Broadcom's April disclosure also said Anthropic was expected to access about 3.5 gigawatts of next-generation TPU capacity beginning in 2027. That scale helps explain the growth opportunity, but the statement is forward-looking. It does not remove deployment timing, financing or customer-concentration risk.
Margins show both sides of the shift
Broadcom's GAAP gross margin rose to 69% from 67% a year earlier as revenue expanded. The company also said the benefit from growth was partly offset by a greater mix of semiconductor solutions, which carry lower gross margins than infrastructure software. On management's adjusted measure, the source reported a 75% gross margin, down 210 basis points from the prior quarter, with a fourth-quarter expectation near 73%.
That pattern does not make AI growth unattractive. It shows that revenue mix matters. Rapid chip growth can increase total profit while reducing the percentage of each sales dollar that becomes gross profit. Broadcom generated $13.67 billion of free cash flow in the quarter, equal to 46% of revenue, which provides a large cushion while the mix changes.
The valuation leaves investors exposed to any disappointment. The source calculated that Broadcom traded near 41 times earnings, versus about 22.9 times for the S&P 500, after the shares had fallen 21% from April 27 through October 26 while the index gained 7.6%.
Broadcom's software revenue, cash generation and several custom-chip relationships keep the story broader than one customer or product. Yet the filing confirms that AI revenue, major end customers and one distribution channel all became more important. The next test is whether AI sales can meet guidance without further margin erosion or a larger dependence on a handful of deployments.
Microsoft's Voluntary Exit Offer Leaves the Savings Question Open
Microsoft's new voluntary exit offer gives tens of thousands of employees a chance to leave with financial support, but the company has not said how many people will accept or how much money the program will save. That missing information matters more than the claim that Microsoft is simply cutting payroll to fund artificial intelligence.
Microsoft said the time-limited program applies to eligible employees at level 70 and below in participating teams in Canada, India, the United Kingdom and the United States. Participation varies by each unit's priorities, customer commitments and workforce needs. Reuters reported that roughly 60,000 employees were eligible, more than a quarter of Microsoft's 223,000 full-time workers at June 30.
Eligibility is not the same as expected departures. Microsoft disclosed neither a participation target nor the cost of the packages, and its public announcement did not connect the offer directly to AI spending. The program should therefore be treated as a workforce-flexibility measure whose financial effect remains unknown.
The source described this as Microsoft's third workforce action of 2026. It said an April retirement program covered 8,750 U.S. employees and drew acceptance above 30%, followed by 4,800 job cuts in July. It also reported that participating areas include Xbox, Windows, Copilot and Finance, while data-center, sales and marketing roles were largely outside the offer. Microsoft did not list participating teams in its public announcement, so those details remain attributed reporting rather than company-confirmed terms.
The spending pressure is real
The timing still gives investors a clear reason to study the program. Microsoft reported $41 billion of capital expenditures in its June quarter. About two-thirds went to shorter-lived assets, primarily CPUs and GPUs used for both AI and non-AI infrastructure. Chief Financial Officer Amy Hood said a shift from finance leases to operating leases reduced Microsoft's calendar-2026 capital-expenditure expectation to about $175 billion.
That figure is not a clean measure of AI spending. It includes broader cloud infrastructure, and the accounting reclassification changed what appears in capital expenditures. Still, the scale means depreciation and operating costs will shape margins for years.
Microsoft is spending against visible demand rather than building into an empty market. Azure and other cloud-services revenue grew 43% in the June quarter, and management said customer demand continued to exceed available capacity. Added capacity was quickly monetized, according to the company. That evidence weakens any simple story that the exit offer reflects a business under stress.
What the offer can and cannot prove
The investor case rests on operating leverage. If enough employees in lower-priority work accept, Microsoft could slow expense growth while protecting teams tied most closely to customer demand. But the company has not identified the savings, the departure mix or the timing of any benefit. Severance costs could also reduce the near-term gain.
There is an execution risk as well. A voluntary program may attract employees with strong outside options, and the teams choosing to participate could lose skills faster than managers expect. Lower headcount helps only if Microsoft can keep product development, security and customer service on track.
The next earnings report should make the program easier to judge. Investors need the number of acceptances, any restructuring charge, expected annual savings and a clearer link between workforce changes and business priorities. They should also compare those figures with updated capital spending, Azure growth and depreciation.
For now, Microsoft's offer is best understood as an option, not a completed cost reduction. The company is creating room to reshape parts of its workforce while cloud demand remains above capacity. Whether that improves margins depends on take-up, execution and the cost of continuing to expand the infrastructure behind Microsoft's AI and cloud services.
Latest comments