


 Be The Investor Research
GoDaddy and Akamai Offer Two Very Different Ways to Invest in AI
GoDaddy sells AI tools through an established small-business platform, while Akamai is spending heavily to build cloud capacity. GoDaddy offers stronger current margins; Akamai offers faster infrastructure growth with greater capital intensity.
GoDaddy and Akamai both benefit from businesses adopting artificial intelligence, but they expose investors to different parts of the spending cycle. GoDaddy sells AI-assisted website and commerce tools to existing small-business customers. Akamai is building cloud infrastructure that provides computing capacity to AI developers and large enterprises.
The distinction shows up clearly in their latest results. GoDaddy reported second-quarter 2026 revenue of about $1.30 billion, up 7% from a year earlier, with operating income of $342.5 million and free cash flow of $443.5 million. Its Applications and Commerce segment grew 11%, while the Core Platform segment grew 4%. GoDaddy's model uses a large installed customer base to distribute Airo and other software without constructing data centers for each new user.
Akamai's cloud infrastructure services revenue reached $99 million in the same quarter, up 39%. The company said multiyear contracts signed in 2026 were worth more than $2.8 billion, including a new four-year commitment exceeding $600 million. That growth is attractive, but it requires far more capital. Akamai's capital expenditure was 32% of revenue in the first half of 2026, and it issued $3.5 billion of zero-coupon convertible notes in May to accelerate the buildout.
The spending is already affecting reported profitability. Akamai's second-quarter operating margin fell to 7% from 15% a year earlier, while its cash balance and contracted demand provide resources to continue expanding. GoDaddy, by contrast, has emphasized margin improvement, free cash flow and share repurchases. Its risk is slower adoption of AI products and weaker customer acquisition, not the same construction and financing burden.
Valuation comparisons require care because the companies have different business mixes and accounting profiles. A lower earnings multiple for GoDaddy does not automatically make it the better investment, just as Akamai's faster cloud growth does not guarantee adequate returns on new capacity.
Investors choosing between them are choosing a business model. GoDaddy offers current cash generation and distribution to small businesses. Akamai offers a more capital-intensive bet that scarce AI infrastructure will support large contracts and stronger future growth. The next evidence should be recurring adoption of GoDaddy's AI tools and the rate at which Akamai converts contracted cloud capacity into revenue and cash flow.
Continue your AKAM research
Related News

Terafab's GDP-Sized Ambition Starts With a Much Smaller Test
Musk says Terafab could rival a top-20 economy, but supplier talks, undefined output measures and a decade-long ramp make capital allocation the immediate issue for Tesla investors.

Google Cloud’s 82% Growth Narrows the Gap, but Not on a Clean Basis
Google Cloud revenue surged 82% to $24.8 billion and its margin reached 35.6%. Claims that it could pass Azure within a year rely on incompatible revenue measures and unsustainable growth assumptions.

Microsoft’s Cheap-Model Strategy Puts AI Margins to the Test
Satya Nadella expects most AI usage to shift toward cheaper, interchangeable models. That could lower Copilot costs, but Microsoft still must earn adequate returns on a sharp rise in data-center investment.
Olo Takes Its Restaurant Software Directly to Diners
Olo’s new consumer app aggregates restaurant ordering without menu-item markups or sponsored listings. The launch tests whether its existing software network can become a lower-cost alternative to major delivery marketplaces.
Big Tech's $2.35 Trillion Backlog Is Huge, but Not All the Same
Microsoft, Oracle, Google Cloud and AWS report about $2.35 trillion of contracted backlog. The total supports AI demand, but different definitions and delivery schedules limit direct comparisons.
Microsoft Offers Buyouts to 60,000 Workers as AI Costs Rise
Microsoft's voluntary exit program covers more than one-quarter of its workforce across four countries, but the undisclosed terms and actual participation will determine the savings.
SpaceX's 80,000-Site Plan Could Reshape the Wireless Supply Chain
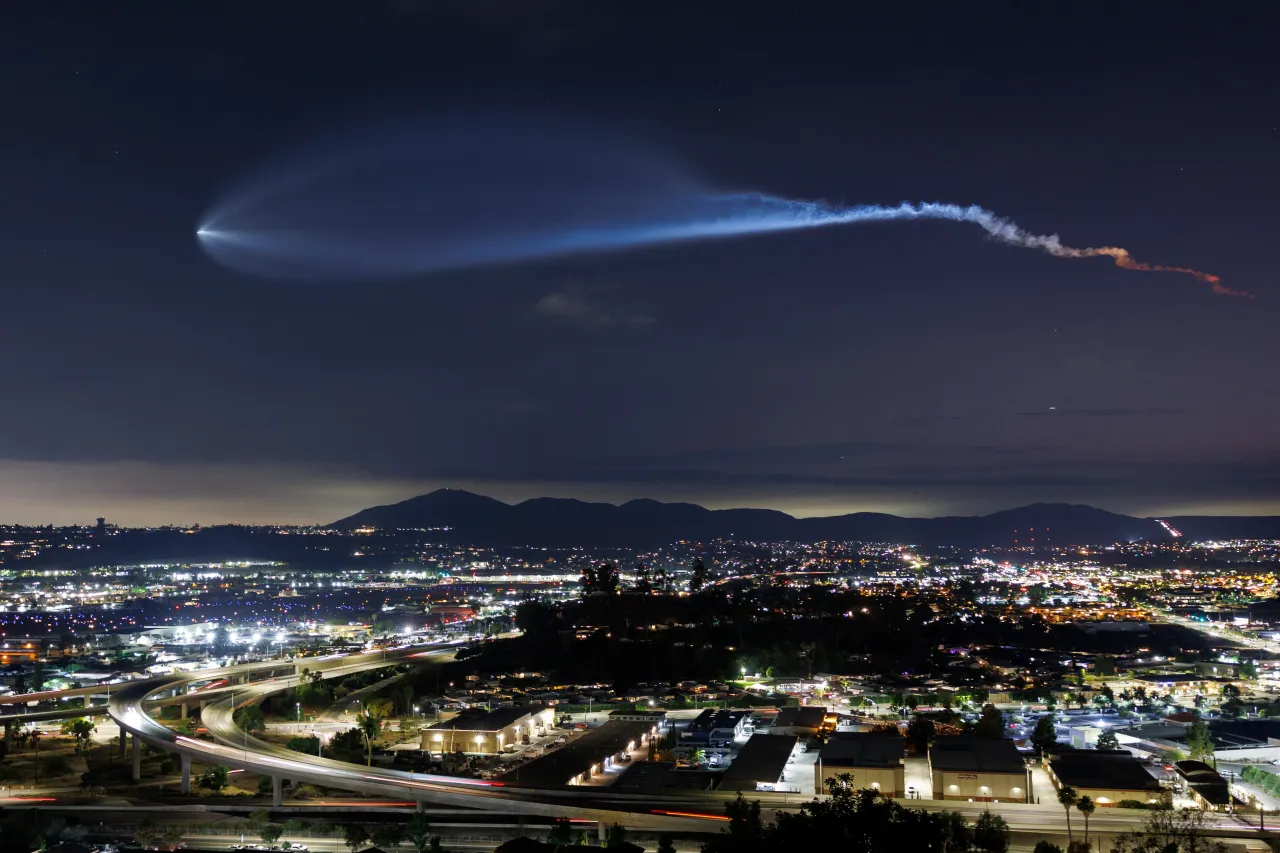
SpaceX is reportedly seeking access to at least 80,000 U.S. cell sites as it works toward a fourth nationwide wireless network. The discussions would add a terrestrial layer to Starlink's direct-to-device satellite service, turning a satellite expansion into a much broader infrastructure project.
Reuters, citing Bloomberg, reported that SpaceX has spoken with cellular infrastructure companies about the sites. Crown Castle was among the tower operators approached, although no agreement has been announced. That distinction matters. An 80,000-site target describes ambition and potential demand, not signed revenue for any supplier.
Roth Capital analyst Scott Searle identified several possible beneficiaries beyond tower landlords. He pointed to radio-access-network vendors Ericsson and Nokia, backhaul specialists Aviat Networks and Ceragon Networks, and spectrum owners Anterix, NextNav and Gogo. The logic is straightforward: a national terrestrial network would need radios at the site, connections between sites and the core network, and usable spectrum. It could also increase the value of AST SpaceMobile's wholesale model if established carriers look for satellite coverage without building a competing national network themselves.
The opportunity is large enough to move stocks, but the timing and economics are unresolved. SpaceX would need to negotiate leases, deploy equipment, integrate terrestrial and satellite networks, and satisfy federal spectrum and interference rules. MarketWatch reported that analysts expect a rollout to take three to five years, while reaching meaningful national market share could take much longer.
Regulation could slow the plan. In an October 20 meeting with the Federal Communications Commission, wireless carriers represented by CTIA asked regulators to keep two 5G bands outside proposed satellite-to-phone rules. The group argued that broader satellite use could interfere with networks serving more than 300 million people and urged the FCC to preserve requirements for agreements with terrestrial license holders.
That pushback shows why the story is not a simple win for every supplier. Tower companies could gain a new tenant, while AT&T, Verizon and T-Mobile face a possible competitor. Equipment and backhaul vendors may see incremental orders, but only after SpaceX selects an architecture and signs contracts. Spectrum holders could become more valuable, yet regulatory conditions may determine which licenses can actually support the service.
The reported 80,000-site goal therefore marks a strategic shift, not a completed buildout. Investors should watch for named infrastructure partners, contract terms and an FCC decision before treating the analyst beneficiary list as an order book.
Zscaler’s Rally Raises the Bar for Its November Results
Zscaler’s next earnings report will test whether a 73.2% three-month share-price rally moved faster than the business. At $255.15, the cybersecurity company was valued at 12.3 times trailing sales, up from 6.8 times at the end of June. That change leaves less room for a merely solid quarter.
Management’s own targets set the immediate test. Zscaler expects fiscal first-quarter 2027 revenue of $935 million to $939 million, about 19% growth, and reaffirmed that range at its October 6 investor day. The company also expects non-GAAP operating income of $215 million to $217 million, or a 23% margin, and non-GAAP earnings of $1.15 to $1.16 per diluted share.
The longer-term question is whether growth can remain strong after last year’s acquisition boost. Fiscal 2026 revenue rose 25% to $3.35 billion, but growth excluding Red Canary was 20%. Annual recurring revenue reached $3.77 billion, also up 25%, while ARR excluding Red Canary grew 20%. Red Canary contributed $141 million of ARR at the July year-end, so investors should separate acquired growth from underlying demand.
Zscaler still reported a GAAP operating loss of $133.3 million for fiscal 2026, equal to 4% of revenue. Its cash generation was much stronger: operating cash flow reached $1.13 billion and free cash flow was $779.1 million. That contrast matters because the valuation depends more on cash flow and future margins than on current reported earnings.
Cash quality also deserves attention. Fourth-quarter free cash flow fell to $60.8 million from $171.9 million a year earlier, even as operating cash flow increased, because capital spending and internal-use software costs jumped to $218.5 million. Management nevertheless guides to a 23.0% to 23.5% free-cash-flow margin for fiscal 2027.
The company says artificial intelligence is expanding demand for zero-trust security, data protection and tools that secure AI agents. That is a plausible growth driver, but management has not isolated revenue from security-for-AI products. Investors therefore need evidence in bookings, core ARR and large deals, not only a broad AI narrative.
For fiscal 2027, Zscaler guides to revenue growth of 16.6% to 17.5% and ARR growth of 16.6% to 17.4%. Those rates would be healthy, but clearly below fiscal 2026. The November report will matter most if it shows whether net new ARR excluding acquisitions is accelerating, whether capital intensity is easing, and whether the company can defend its cash-flow outlook. After the rally, meeting the revenue range may no longer be enough.
Morgan Stanley Moves Wealth AI From Answers to Actions
Morgan Stanley's wealth business is moving artificial intelligence from answering questions to carrying out controlled workflows across multiple systems. That shift could save advisers and service staff time, but the bank has not yet quantified the revenue, cost savings or error rates tied to the new tools.
The strategy rests on work that began years before generative AI became popular. Hina Shamsi, chief information officer for wealth management technology, told CIO Dive that the division stopped organizing data only around individual accounts and began building a broader view of each client relationship.
That change supported machine-learning tools that recommend the next action for an adviser. It also created the context and semantic layer that newer AI agents need to understand data consistently across the wealth platform.
Three agents, different boundaries
Morgan Stanley is focusing on three areas: client interaction, service support and adviser assistance.
The client agent lets customers ask questions in plain language and complete common tasks. Management plans to add more account-specific context over time.
The service agent helps client-service associates retrieve information and complete work such as moving money, opening accounts and changing beneficiaries. These tasks sound simple, but they often require several applications and approval steps. Automating the navigation can reduce manual effort while leaving the professional responsible for the decision.
The adviser agent supports daily work so advisers can spend more time with clients. This builds on earlier products such as AI @ Morgan Stanley Debrief, which can create meeting notes and draft follow-up emails with a client's consent. The adviser still reviews the output before sending it.
Controls are part of the product
The expansion from search to action raises the stakes. An incorrect summary is inconvenient. An agent that moves money or changes a beneficiary can create financial and legal harm if permissions are wrong.
Morgan Stanley says its agents operate within defined limits covering the data they can access, the actions they may take and the points at which a human must intervene. The firm's public AI materials also emphasize human-centered design, data protection, monitoring and oversight.
The financial payoff is still unproven
The wealth unit has scale that can make small productivity gains meaningful. Third-quarter 2026 wealth-management revenue reached a record $9.07 billion, up from $8.23 billion a year earlier. The business reported $232.4 billion of net new assets and a 30.4% pretax margin.
Those results do not isolate the effect of AI. Morgan Stanley attributed the quarter mainly to higher asset-management fees, net interest income and client flows. Technology spending also increased. Without disclosed adoption, time saved, error rates or unit costs, investors cannot separate operational progress from a measurable earnings contribution.
The important change is architectural. Morgan Stanley is no longer treating AI as a stand-alone chatbot. It is connecting agents to workflows, permissions and client context. That could widen the bank's service capacity, but the next proof point should be evidence that the tools improve productivity without weakening control.
Salesforce's Braze Deal Raises the Stakes in Marketing Software
Salesforce's $5.66 billion agreement to acquire Braze is more than a product extension. It places a large strategic value on real-time customer engagement and could change how investors assess smaller marketing software companies.
Salesforce agreed to pay $47.50 in cash for each Braze Class A share. The transaction, announced October 20, values Braze at approximately $5.66 billion in enterprise value and is expected to close during Salesforce's fiscal 2028. It still requires Braze shareholder approval, regulatory clearance and other customary conditions. Salesforce said the deal does not change its fiscal 2027 guidance.
Braze provides software that reacts to customer behavior across mobile apps, websites, email, text messages and other channels. Salesforce plans to connect those real-time signals and Braze's AI decisioning with Data 360, Customer 360, Agentforce and Marketing Cloud. The strategic aim is to improve Salesforce's consumer-facing marketing capabilities, an area where it competes with Adobe and other customer-engagement platforms.
The price also sends a message to the sector. Jefferies described the transaction as the third large small-to-mid-cap software deal in a short period, following agreements involving CCC Intelligent Solutions and Varonis. The firm said the Braze acquisition could be the spark for a strategic bid for Klaviyo, another marketing technology company. That is an analyst view, not evidence that Klaviyo is in talks.
Jefferies saw a different implication for Twilio. A stronger Salesforce marketing stack could reduce reliance on outside messaging providers or increase pressure on their pricing. The risk is not that Twilio immediately loses Salesforce-related volume, but that a more integrated platform changes bargaining power over time.
For Salesforce, the investment case depends on integration and returns. Braze serves about 2,770 customers and brings a cloud-native system designed for high-volume, real-time engagement. The combination could make Marketing Cloud more competitive, but the transaction also carries execution risk, transaction costs and the possibility that expected customer or revenue benefits arrive later than planned.
The deal's structure keeps an important distinction clear. Salesforce has signed a definitive agreement, but it has not completed the acquisition. Braze remains a public company until closing, and the parties must navigate shareholder and regulatory review.
Investors now have three separate questions. Salesforce must show that Braze can strengthen its marketing products without distracting from margin discipline. Braze shareholders must evaluate a fixed cash price against closing risk. Peers such as Klaviyo and Twilio may trade on takeover or competitive speculation, but their outcomes will depend on their own growth, customer retention and strategic value, not on the Braze deal alone.
Microsoft and Oracle Have Similar AI Backlogs, Not Similar Risk
Microsoft ended fiscal 2026 with $678 billion of commercial remaining performance obligations, while Oracle reported $664 billion after its fiscal first quarter. The two backlogs are close enough to invite comparison, but they do not represent the same financial proposition.
Remaining performance obligations, or RPO, measure contracted revenue that has not yet been recognized. The metric can signal future demand, but it does not show how quickly revenue will arrive, how much capital is needed to deliver it or how concentrated the contracts are. Those differences separate Microsoft from Oracle more clearly than the headline totals.
Microsoft is funding AI from an established cash engine
Microsoft's fiscal fourth-quarter revenue reached $90.0 billion, up 17.8% from a year earlier. Azure and other cloud services grew 43%, and Microsoft Cloud revenue reached $59.3 billion. Even after large data-center investments, the company produced $19.6 billion of quarterly free cash flow.
The composition of the backlog also provides context. Commercial RPO grew 84%, but it increased 25% when OpenAI was excluded. Microsoft said roughly 30% of the total should be recognized within 12 months and the weighted average duration was 2.3 years. Nearly 90% of Microsoft Cloud revenue came from customers outside frontier-model companies, reducing dependence on a small group of AI labs.
Microsoft is also monetizing AI through software. Paid Microsoft 365 Copilot seats exceeded 30 million, giving the company a second route to earn a return on infrastructure spending. That does not remove execution risk, but it spreads the risk across Azure, Office, Dynamics and other businesses.
Oracle's growth requires more outside capital
Oracle's cloud infrastructure revenue grew 121% in fiscal Q1, and the company added more than $30 billion of AI cloud contracts, taking RPO to $664 billion. It delivered more than 300,000 GPUs to cloud customers and almost tripled capacity from the previous quarter. Demand is not the main uncertainty.
The funding model is. Oracle generated a record $23 billion of operating cash flow in the quarter, yet free cash flow was about negative $5 billion because of its infrastructure buildout. The company also completed a $20 billion at-the-market common-stock sale. Oracle said the structure of the new contracts did not create an incremental need to raise capital, and management has described customer prepayments and bring-your-own-hardware arrangements as partial protection.
Concentration and timing still matter. Oracle relies on a smaller number of very large AI contracts, and its source article said interest expense rose 55% to $1.4 billion. Management has not given a date for free cash flow to turn positive. A large RPO balance therefore offers revenue visibility, but it does not by itself prove attractive returns on the assets being built.
The useful comparison is cash conversion
Oracle's lower valuation can look appealing after a steep share-price decline, but the discount reflects real financing and execution risks. Microsoft trades at a higher multiple because investors can see positive free cash flow while capacity expands.
The next evidence is operational. Microsoft must sustain Azure growth while preventing AI investment from eroding margins. Oracle must keep capital spending within its plan, convert its backlog on schedule and show that cloud revenue can outrun depreciation, interest and dilution.
For investors, the similar RPO totals are the beginning of the analysis, not the conclusion. Backlog quality depends on duration, customer concentration, funding terms and eventual cash conversion. On those measures, Microsoft currently offers the steadier model, while Oracle offers more upside sensitivity if its capital-intensive expansion begins producing durable positive free cash flow.
Latest comments