


 Be The Investor Research
GE Vernova's Q3 Test Is Turning a $176 Billion Backlog Into Cash
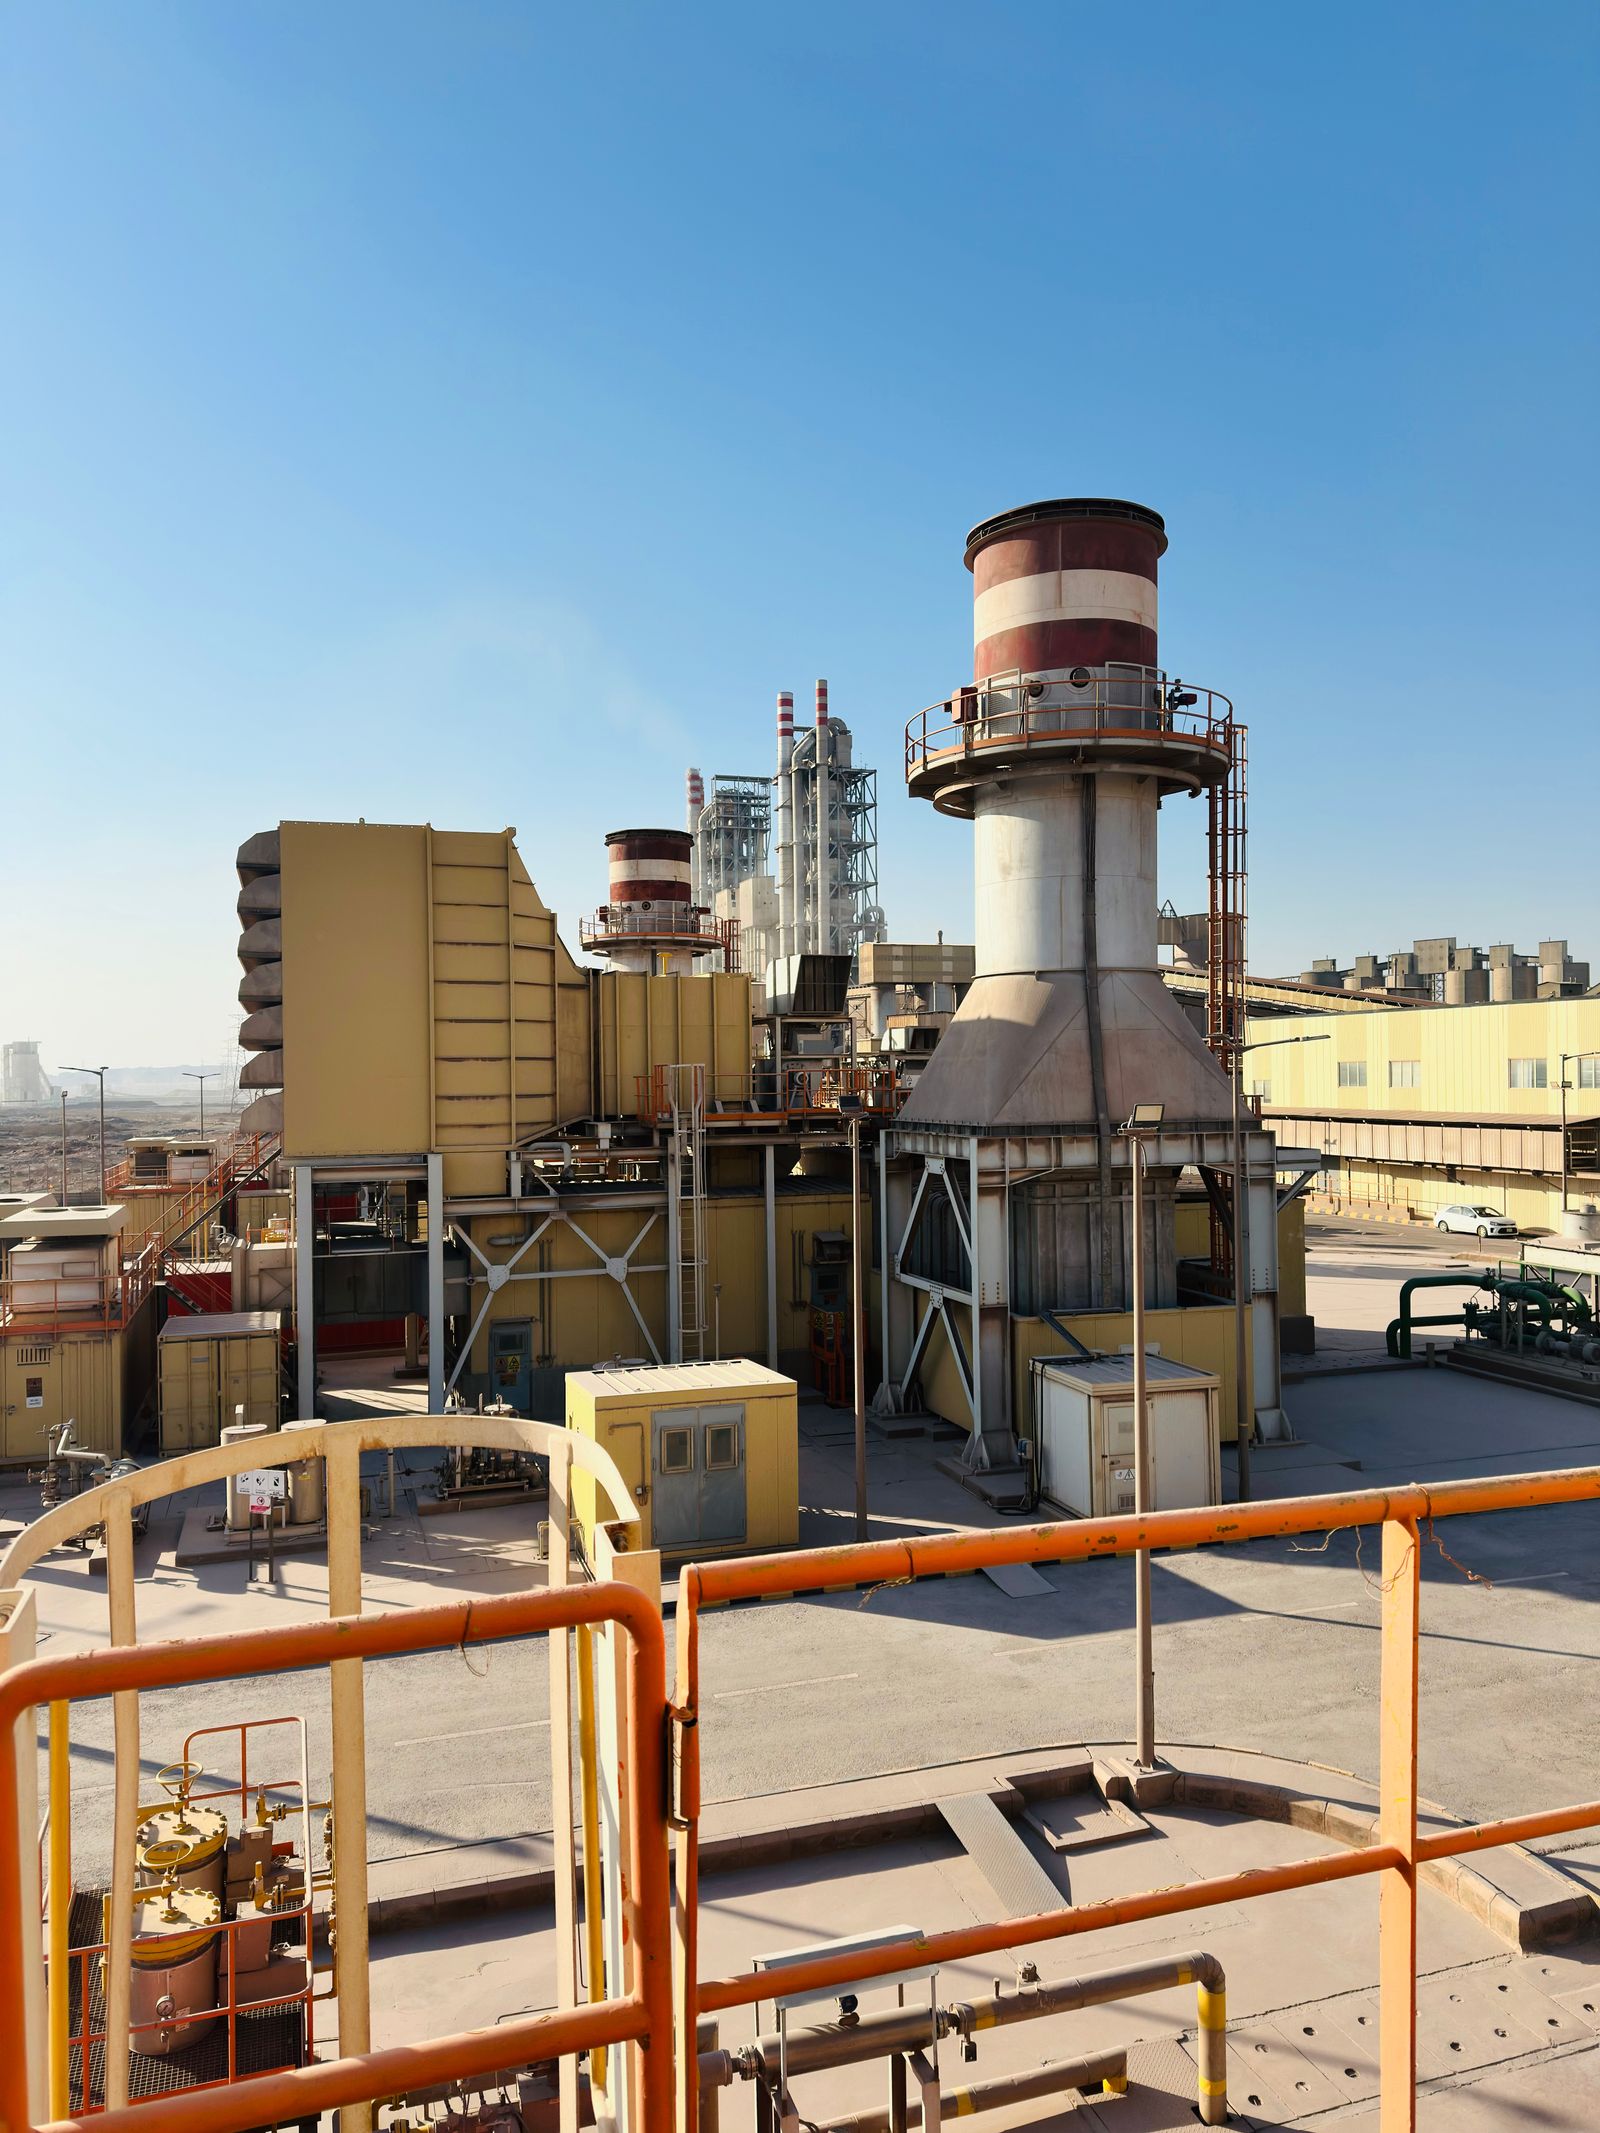
GE Vernova reports October 28 after raising 2026 revenue and free-cash-flow guidance. Investors will focus on backlog conversion, gas-turbine output, data-center orders and whether Wind approaches break-even.
GE Vernova reports third-quarter results before the market opens on October 28 with a $176 billion backlog, higher full-year guidance and a stock that has fallen sharply from its recent high. The report will test whether strong demand for power equipment and grid infrastructure is converting into revenue, margins and cash at the pace investors expect.
The $176 billion figure is GE Vernova's remaining performance obligation, not cash in hand or revenue guaranteed for the quarter. It rose by $13 billion sequentially in the second quarter as equipment and services orders expanded. Second-quarter orders reached $24.2 billion, up 88% organically, while revenue rose 22% to $11.1 billion. Free cash flow was $5.1 billion, more than the company generated in all of 2025.
Those results led management to raise 2026 revenue guidance to $45.5 billion to $46.5 billion from $44.5 billion to $45.5 billion. It also lifted free-cash-flow guidance to $11.5 billion to $12.5 billion from $6.5 billion to $7.5 billion, while keeping its adjusted EBITDA margin target at 12% to 14%. The size of the cash-flow revision raised expectations for the second half, even though management has said first-half cash generation should be much stronger than the second half.
Gas Power is the first operational test. GE Vernova said gas equipment backlog and slot reservations totaled 116 gigawatts at the end of the second quarter, with at least 125 gigawatts expected under contract by year-end. Management also said it was on track to reach an annualized gas-turbine output rate of 20 gigawatts in the third quarter, up from roughly 12 gigawatts previously. Investors need to distinguish firm backlog from slot reservations because reservations do not carry the same certainty as contracted orders.
Electrification provides another measure of AI-related demand. Data-center orders exceeded $5 billion in the first half, more than double the total for all of 2025. The original source says management expected third-quarter Electrification revenue of $3.8 billion to $4 billion after the segment's margin reached 18.4% in the second quarter. Sustained orders and margins would show that grid constraints are translating into profitable business rather than only a long pipeline.
Wind remains the counterweight. The segment lost $275 million of adjusted EBITDA in the second quarter, and management expected third-quarter results near break-even as onshore service profits improved and offshore costs declined. Missing that mark would show that weakness in Wind is still absorbing part of the gains from Power and Electrification.
The source's analyst compilation points to third-quarter revenue of about $12.0 billion, roughly 20% above the year-earlier period, and earnings per share of $4.02. It also says the EPS estimate has declined from $4.33 over the past 90 days. These are market estimates, not company guidance.
GE Vernova shares closed at $814.58 on October 23, down 14.37% over one month but still up 24.93% in 2026, according to the source. That combination leaves little room for vague assurances. A larger firm backlog, evidence that turbine output is scaling, solid Electrification demand and free cash flow consistent with the raised outlook would support the long-term case. Slower conversion or another Wind setback would make the $176 billion headline look less reassuring.