



Caterpillar's $800 Target Requires More Than Record Backlog
Freedom Capital kept a Buy rating on Caterpillar but cut its target to $800. Record sales and a $78 billion backlog support the case, while the implied valuation and soft fourth-quarter setup leave little room for disappointment.
Freedom Capital Markets cut its Caterpillar price target to $800 from $980 on November 2 while keeping a Buy rating. The new target still implied about 30% upside at the source's reference price, but it also requires investors to pay a premium multiple while near-term margins remain under pressure.
Caterpillar's third quarter provides real support for the bullish case. Sales and revenue increased 17% from a year earlier to $20.7 billion, the company's largest quarter. Reported profit per share rose to $7.13 from $4.88, while adjusted profit per share increased to $7.20 from $4.95. Operating profit margin expanded to 20.4% from 17.3%.
Cash generation was also strong. Enterprise operating cash flow reached $4.4 billion, and Caterpillar ended the quarter with $7.9 billion of enterprise cash. It spent about $1.2 billion on share repurchases and $700 million on dividends during the period.
The backlog is the most important forward indicator in the source analysis. It reached a record $78 billion at the end of September, up 96% from a year earlier. Management said some large reciprocating-engine orders extend into 2029 and turbine orders into 2030, reflecting demand for power generation, including data centers.
The near-term setup is less comfortable. The source reports that management expects moderate year-over-year sales growth in the fourth quarter and about $1.6 billion of inventory reduction by construction dealers, with roughly a $1 billion effect on Construction Industries sales volume. It also says adjusted operating margin, excluding tariff refunds, is expected near the bottom of the company's target range.
Valuation ties the two sides together. Using the source's $29.95 estimate for next-12-month earnings, an $800 target implies about 26.7 times earnings. That is well above the cited five-year average of 19 times. The calculation is straightforward: $800 divided by $29.95 equals 26.71. The target therefore depends not only on profit growth but also on investors accepting a higher multiple than Caterpillar's recent norm.
The next major evidence will come with fourth-quarter results and management's initial 2027 outlook. Sustained power demand, backlog conversion and improving margins could justify a premium. Dealer destocking, higher freight costs or delayed capacity additions would make the $800 target harder to reach even if revenue continues to grow.
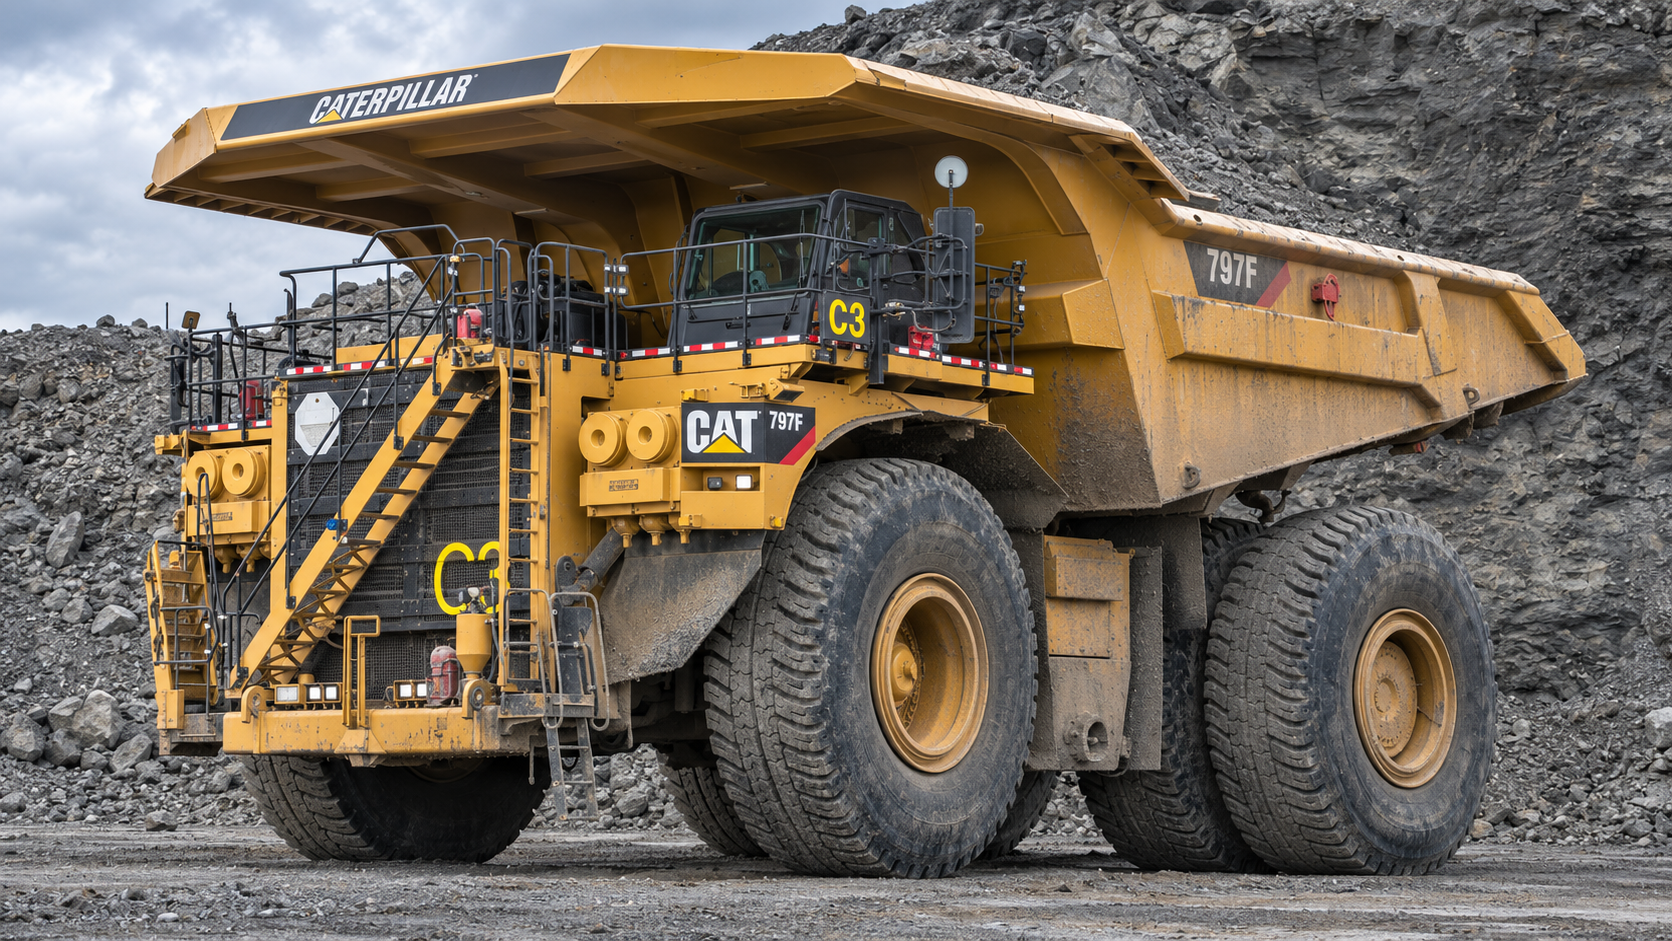
Image references: · Finning Cat official 797F dealer product photograph (Reference copyright retained by its owner; factual visual research, no CC grant claimed.)
Frequently asked questions
What is "Caterpillar's $800 Target Requires More Than Record Backlog" about?
Caterpillar posted record sales and a $78B backlog, but Freedom's $800 target implies about 26.7 times forward earnings as margins stay pressured.
What is the market context?
Freedom Capital Markets cut its Caterpillar price target to $800 from $980 on November 2 while keeping a Buy rating. The new target still implied about 30% upside at the source's reference price, but it also requires investors to pay a premium multiple while near-term margins remain under pressure. Caterpillar's third quarter provides real support for the bullish case. Sales and revenue increased…
When was this article published?
It was published on 04 / 11 / 2026 by Be The Investor Research.